Brent's Three Percent Answer to a Four Million Barrel Hole
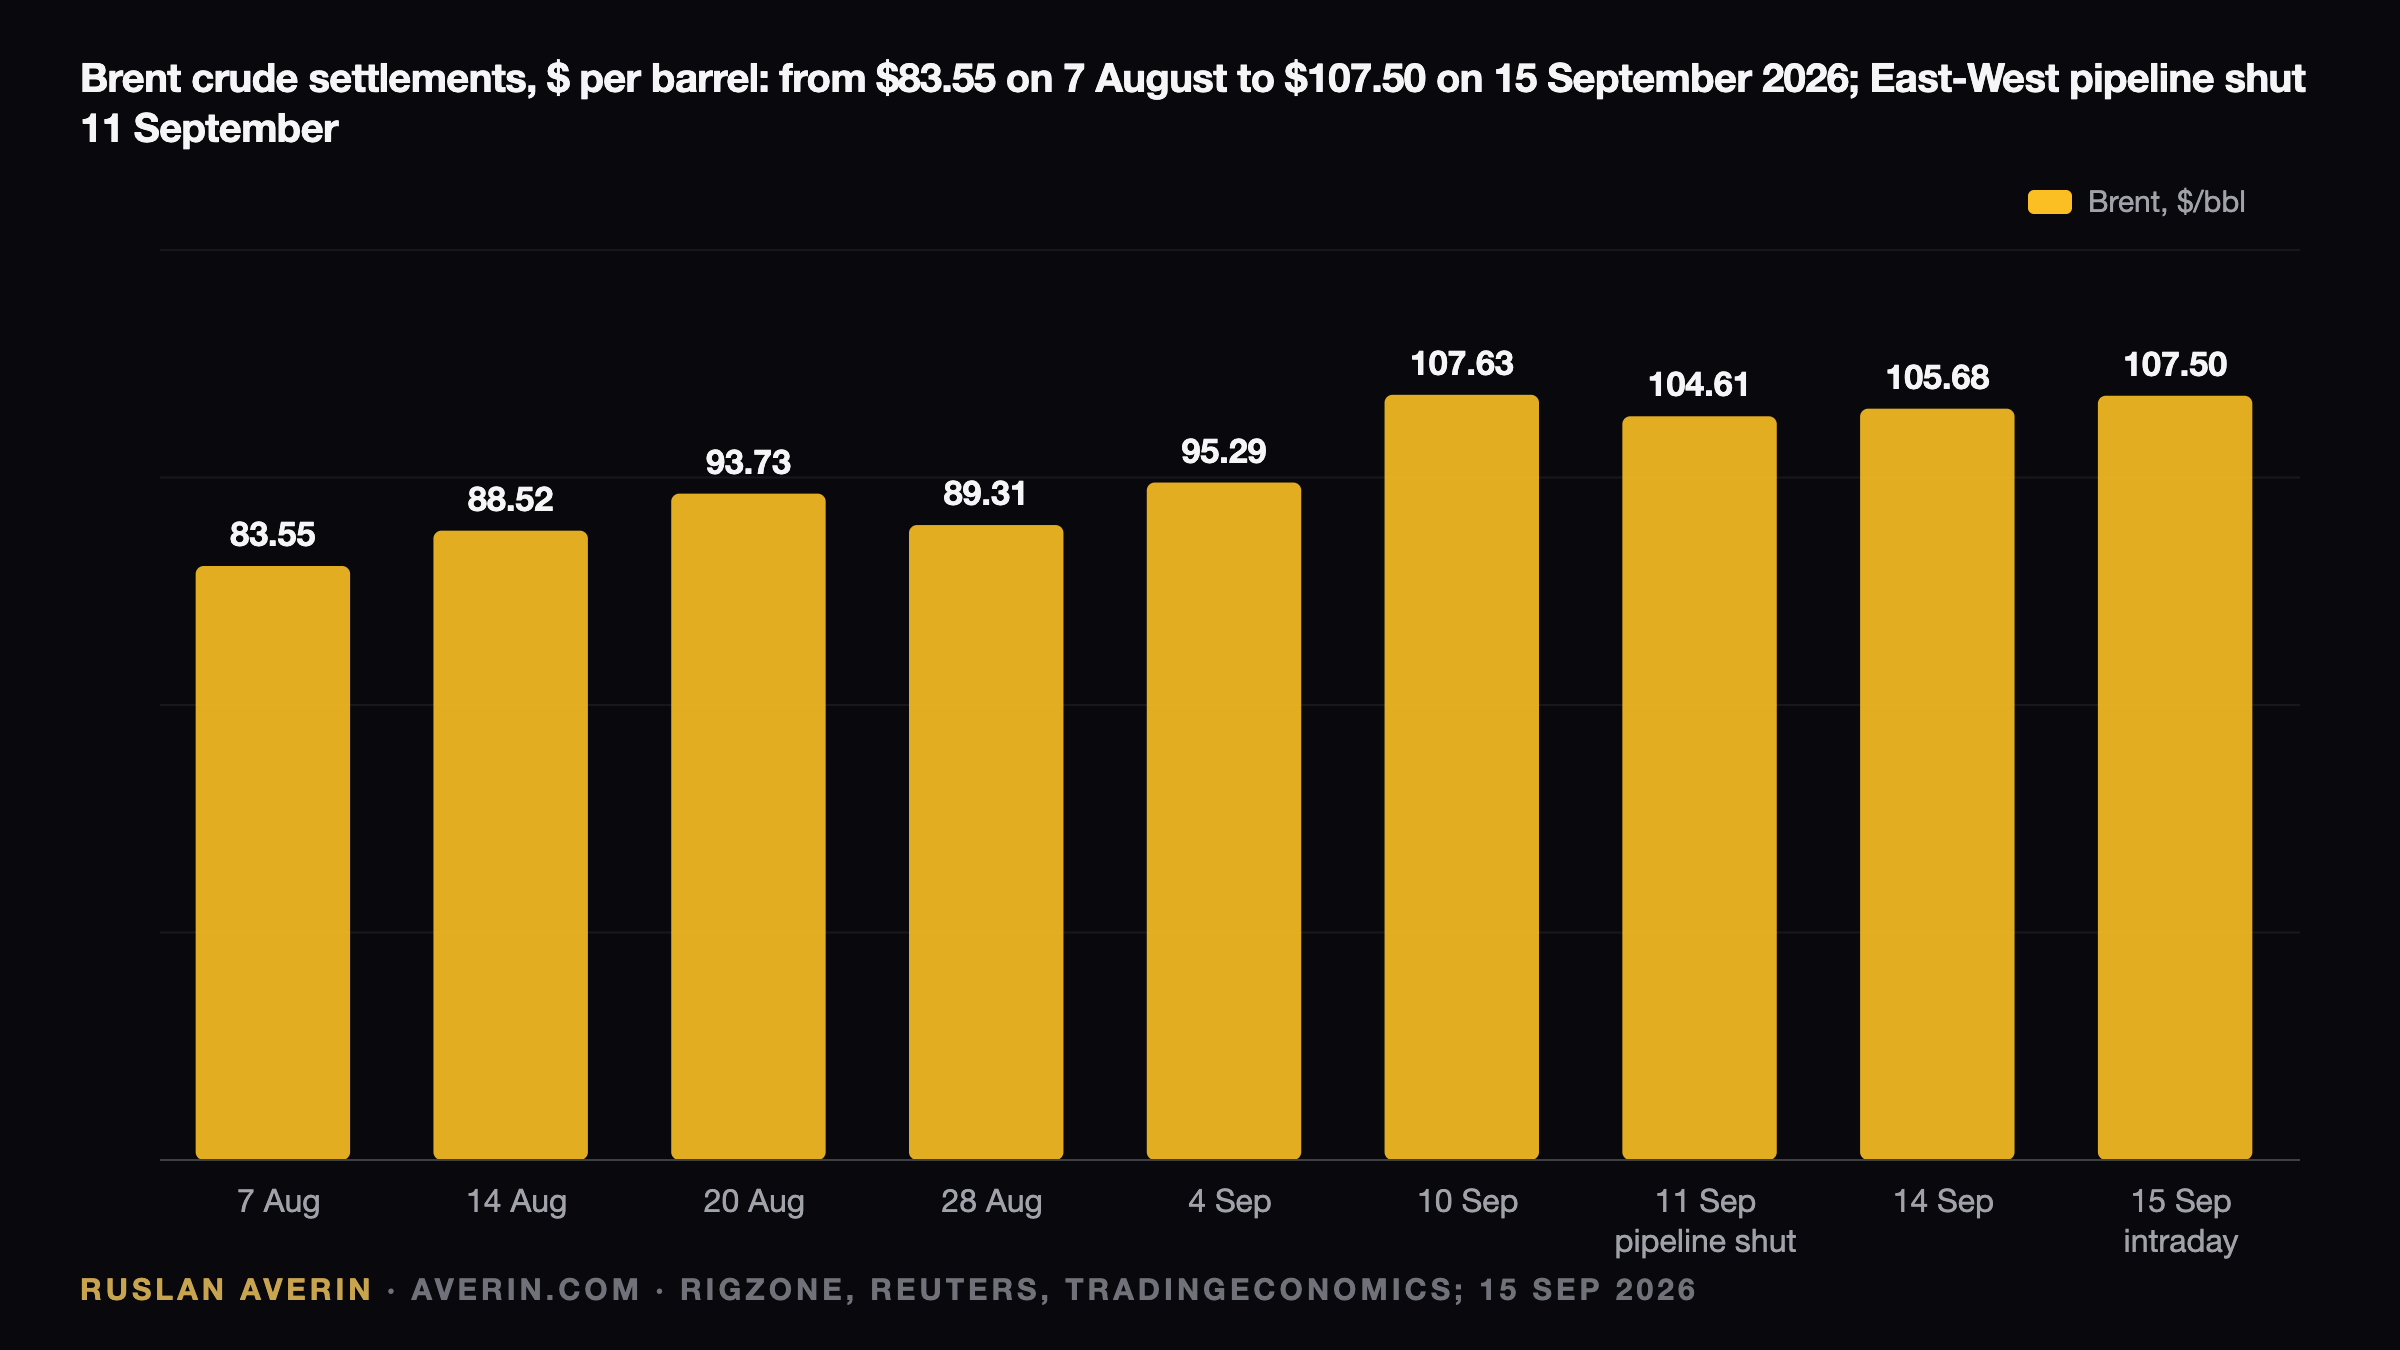
Saudi Arabia's East-West pipeline has been shut since Friday 11 September 2026, and price action suggests traders have filed the event as a five-day inconvenience. Brent settled at $104.61 on the day of the announcement, $105.68 on Monday 14 September, and traded near $107.50 on Tuesday. A move of about 3% for roughly 4 million barrels a day of stranded exports is a bet on tank bottoms at Yanbu.
What Petroline Carried, and the Yanbu Bottleneck
Petroline runs about 1,200 km from Abqaiq in the Eastern Province to Yanbu on the Red Sea. Nameplate capacity was 5 million barrels a day; since the 2019 Abqaiq attack Aramco has been able to push 7 million by converting parallel NGL lines, and the line ran at that record from the first quarter of 2026. Yanbu's two terminals load only about 4.5–5 million, capping exports near 4 million.
Hormuz Was Closed, So the Bypass Was the Whole Story
Saudi production fell to 6.2 million barrels a day in August from 10.9 million in February, the lowest since 1990 on the IEA's count, because the Strait of Hormuz has been effectively closed since 28 February. It reopened under a US-Iran memorandum from 17 June to 18 August, when flows reached 6.1 million a day. Since expiry, trackers count 5–9 million against roughly 20 million before the war.
| Route | Capacity, mb/d | Status mid-September 2026 |
|---|---|---|
| Strait of Hormuz | ~20 crude and products before the war | 5–9; about 8 transits a day against 85 |
| Saudi East-West to Yanbu | 7 design, Yanbu terminals 4.5–5 | shut since 11 September; was carrying ~4 |
| UAE Habshan–Fujairah | 1.5–1.8 | operating; expansion above 3 in 2027 |
| Iraq Kirkuk–Ceyhan | ~1.6 | about half used |
| Ras Tanura and Ju'aymah | ~7 Saudi Gulf exports before the war | reopened late June, limited by Hormuz |
Eight Fire Clusters Along the Madinah Section
Multiple drones launched from Iraq's Maysan province struck pump stations in the Riyadh and Madinah regions on the morning of 10 September. Satellite data show eight fire clusters and a smoke plume of about 100 km, with Maxar imagery showing a blackened pumping station. Nobody claimed the strike. Riyadh blames Iran-backed militias in Iraq; Baghdad sacked the Maysan commander and closed the Shalamcheh crossing with Iran.
Saudi Arabia said it would not retaliate "at this stage". The comparison point is April, when a strike on a single pump station cost about 600,000 barrels a day and full throughput of 7 million returned within a week. This time officials describe the damage as more serious, and Verisk notes that shipping disruption is delaying the import of repair parts.
Restart Guesses Set Against Tank Bottoms
US Energy Secretary Chris Wright said on 14 September the line would be "running back soon". Regional officials told AP on 15 September that 3–5 weeks are needed, including a major pumping facility. Reuters industry sources said 5–6 weeks on 13 September, with a partial restart possible sooner. Andy Lipow of Lipow Oil Associates was harsher the same day: "it will take months to repair." Prediction markets sat at 63–85% for a restart by 30 September.
Against that stands the inventory. Yanbu holds about 35 million barrels of total storage, of which three industry sources told Reuters only five to seven days of exports are usable. Suvro Sarkar of DBS repeated that number on Bloomberg and warned of "huge disruption" beyond it, with Brent testing $120. Kpler's Matt Smith framed a month's loss at 120 million barrels into a market "already starved of barrels".
The Buffers That Carried Six Months Are Gone
The IEA's September report explains why the safety net is thinner than in March. Global output fell 1.6 million barrels a day in August to 100.1 million, with more than 10 million of Gulf production shut in. Observed inventories fell 95 million barrels in August and 507 million since February, an average draw of 2.8 million a day.
The US Strategic Petroleum Reserve stands at 285.4 million barrels, 40% of capacity and the lowest since 1982, after the 172 million barrel American share of the IEA's 400 million release in March. No new release has followed the pipeline attack. Paul Gooden of Ninety One said on 15 September that roughly a billion barrels have been drawn globally, with "another ~1bn to go before we hit tank bottoms" and risk "asymmetrically to the upside". Ben Cahill of the Atlantic Council: the key buffers "have basically been worn away".
Demand Destruction Is Doing the Capping
The IEA now has 2026 consumption down 2.5 million barrels a day, 940,000 worse than a month earlier. The world is burning less because it cannot source barrels. Meanwhile the spare supply OPEC+ agreed to hold flat for October, 31.1 million barrels a day across seven core members, physically cannot leave the Gulf.
Freight, Cracks and the Airline Mirror
Tanker owners captured the rent. The Middle East to China VLCC benchmark hit a record $759,969 a day on 9 September, and a Frontline fixture through Hormuz was reported at $601,771 a day. War-risk cover is 40 times pre-crisis levels, insuring a single VLCC voyage for about $10 million against $250,000 in peacetime. Crude-tanker equities are up roughly 120% in 2026, with International Seaways at an all-time high and Frontline at its highest since 2011.
Marathon Petroleum and Valero have more than doubled on record crack spreads, with diesel futures near $200 a barrel and US pump diesel at a record $6.27 a gallon on 15 September against $3.71 a year earlier. Airlines mirror the move: IATA has cut 2026 industry profit to $23 billion from $45 billion on jet fuel up 70%.
A Five Percent Risk-Free Rate Changes the Trade
This week's new variable is the bond market. August PPI printed 5.4% year on year with diesel the largest single contributor, CPI is 3.4%, and the 10-year Treasury went through 5% on 14 September for the first time since 2023. The Fed decides Wednesday with a hike priced above 90%. In March the 10-year was under 4.5%; the Dow fell about 500 points Tuesday, energy among the laggards.