Dollar Headlines Flatter Every Seller
A seven-year price table quoted in dollars overstates what Ukrainian owners actually earned. Between the end of 2019 and August 2026 consumer prices in the country rose 97%, while the hryvnia weakened from 25.15 to 44.55 per dollar — a 77% gain for the American currency. Both filters have to be applied before any of the headline percentages mean much.
The inflation path itself explains the scale of the distortion: 5.0% in 2020, 10.0% in 2021, 26.6% in 2022, 5.1% in 2023, 12.0% in 2024, 8.0% in 2025 and 6.1% so far this year. Compounded, that is roughly a doubling of the general price level in the same window in which flats supposedly doubled.
What Survives the Recalculation
Kyiv's 42% dollar gain converts to 152% in hryvnia and about 28% in real terms — positive, but unremarkable for a seven-year hold. Ivano-Frankivsk's 189% becomes 412% in hryvnia and roughly 160% in real terms, the only tier that beat inflation by a wide margin.
Kharkiv illustrates the other end. A fall of 29% in dollars still reads as 26% growth in hryvnia, yet that is a 36% real loss, and the calculation ignores seven years of forgone rent. The dollar column rewards everyone; the real column separates the west from the capital and the capital from the east.
Twelve Cities, One Dataset
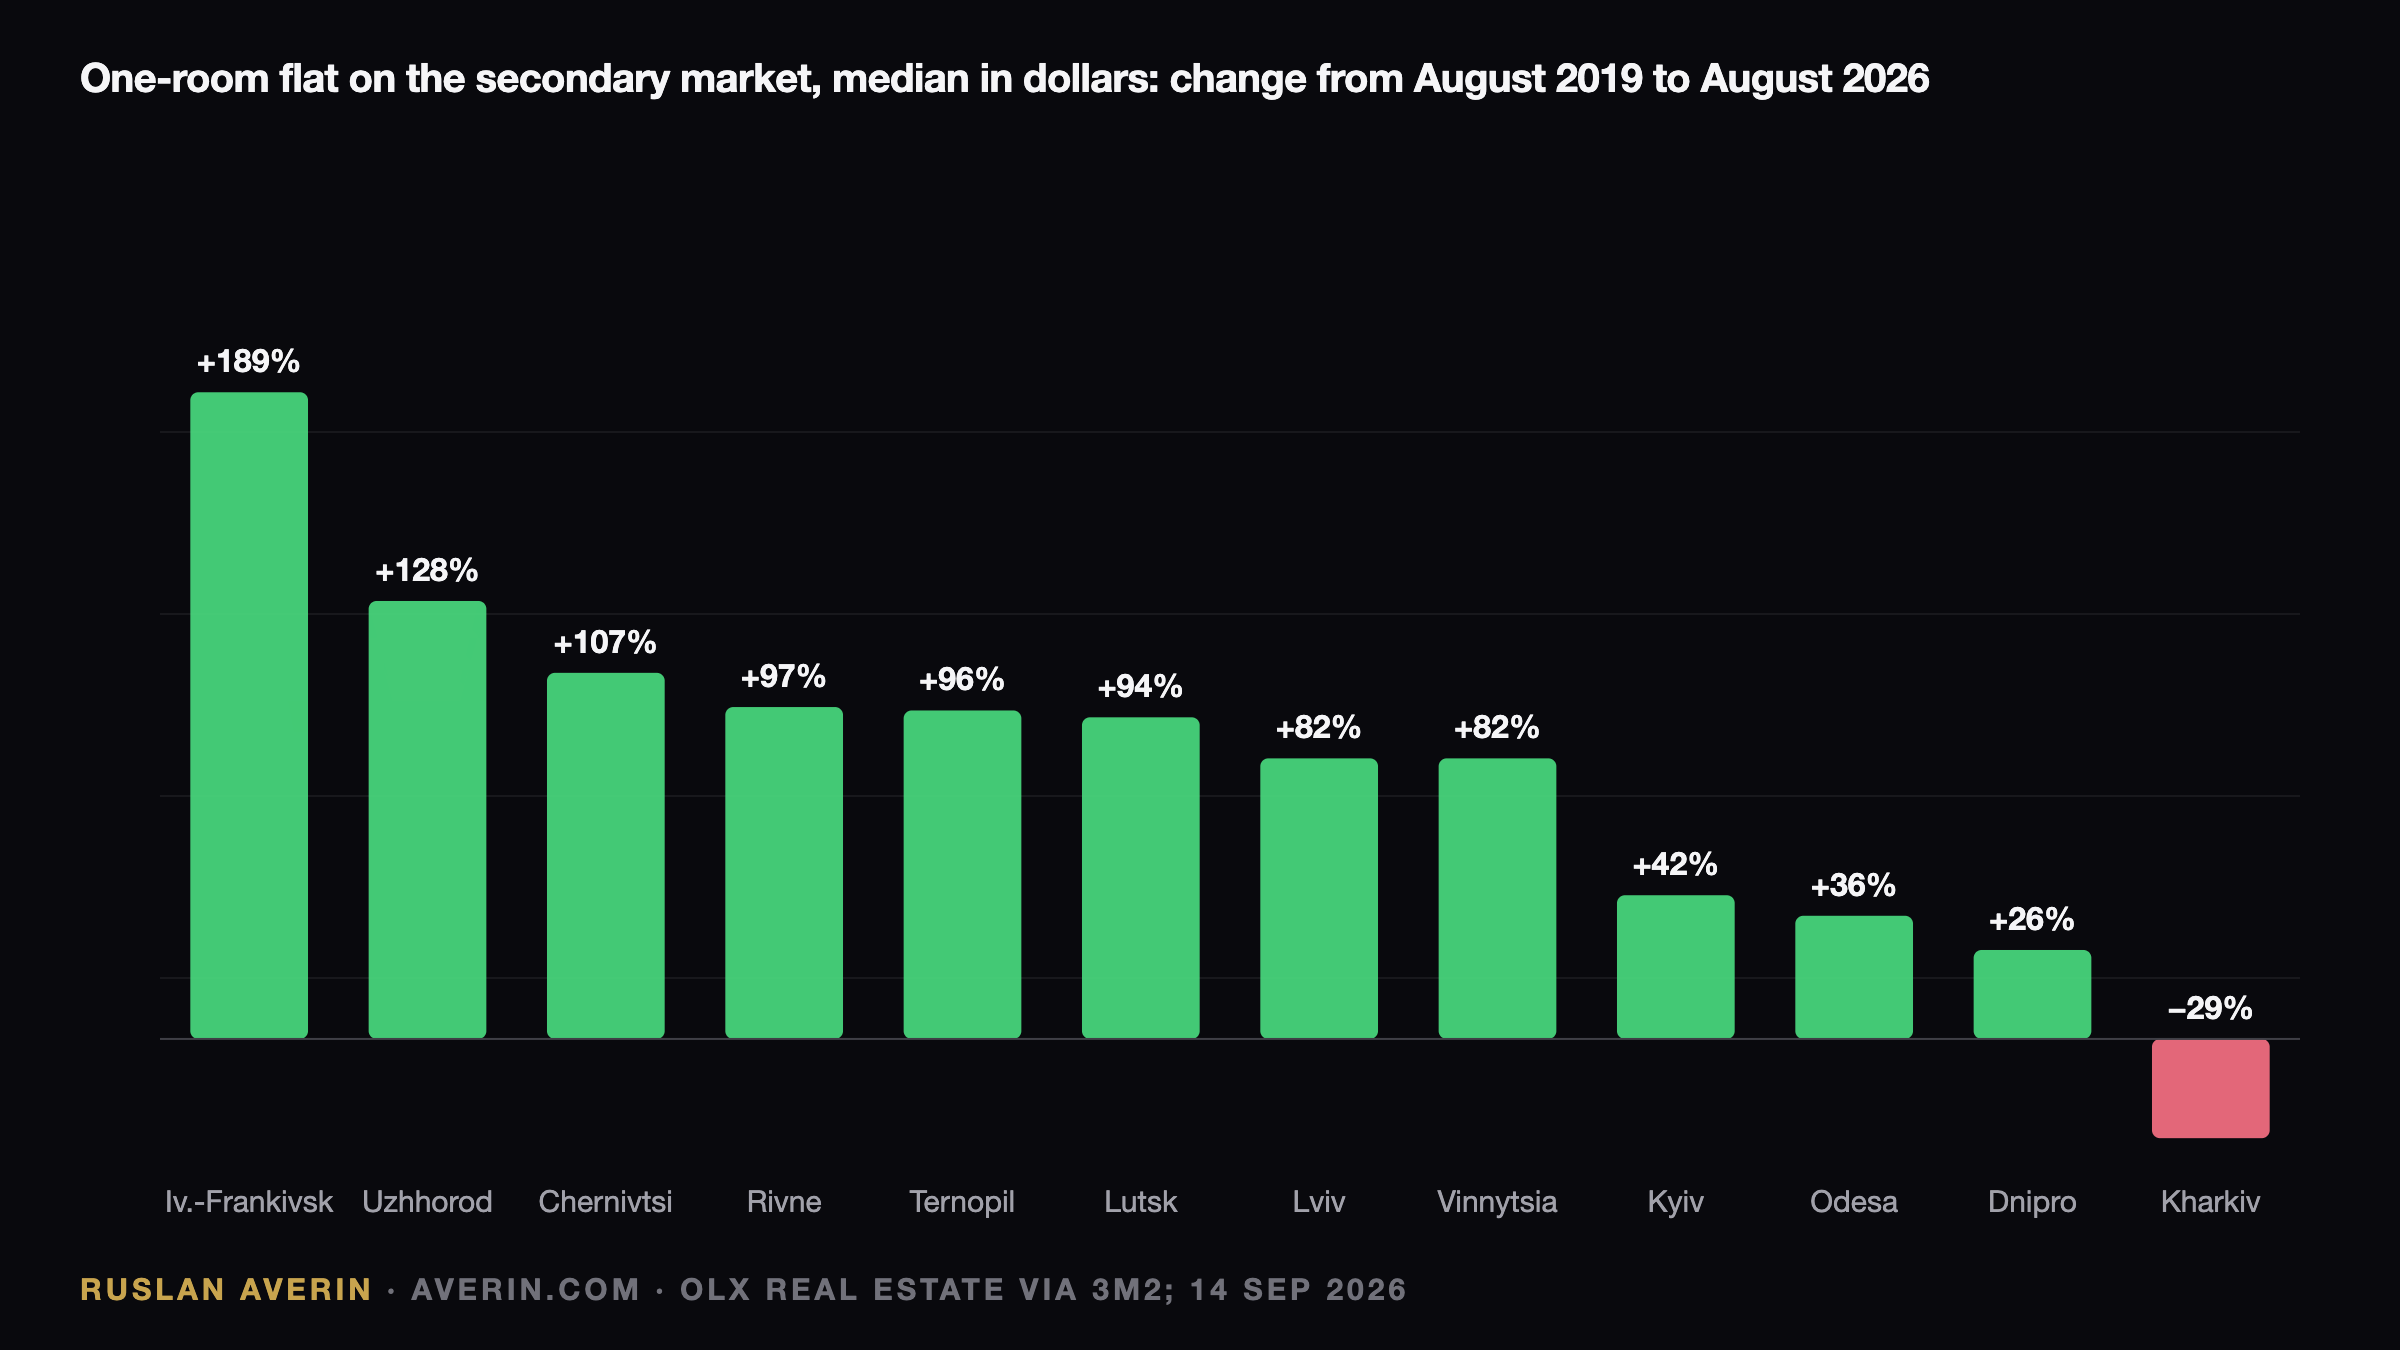
The nominal figures come from an OLX Real Estate study published on 14 September, covering median asking prices for one-room flats on the secondary market.
| City | August 2019 | August 2026 | Change |
|---|---|---|---|
| Ivano-Frankivsk | $17,200 | about $50,000 | +189% |
| Uzhhorod | $33,700 | $77,000 | +128% |
| Chernivtsi | $29,000 | $60,000 | +107% |
| Rivne | $28,000 | $55,000 | +97% |
| Ternopil | $26,500 | $51,800 | +96% |
| Lutsk | $31,000 | $60,000 | +94% |
| Lviv | $42,000 | $76,400 | +82% |
| Vinnytsia | $32,500 | $59,000 | +82% |
| Kyiv | $50,800 | $72,000 | +42% |
| Odesa | $36,800 | $50,000 | +36% |
| Dnipro | $25,000 | $31,500 | +26% |
| Kharkiv | $35,400 | $25,000 | −29% |
The geography is the war. West of the Dnipro, prices at least doubled on internal migration, relocated business and an absence of new supply. Kyiv and Odesa added between a third and a half. Dnipro barely moved. Front-line cities fell: Kharkiv and Zaporizhzhia −29%, Mykolaiv −32%, Sumy −12%, Kherson −8%. On this series Uzhhorod, a border centre facing Slovakia, now ranks second in the country, above the capital.
Wages Tell the Opposite Story to Prices
The average wage was UAH 10,537 in August 2019, about $419, and UAH 32,243 in July 2026, about $724 — up 206% in hryvnia, 73% in dollars and 53% in real terms. A Kyiv one-room flat therefore cost 121 monthly wages in 2019 and 100 in 2026. The capital became more affordable over seven years, not less.
LUN's affordability index points the same way: 7.6 years of the average local wage for a Kyiv one-room flat in March 2026, down from 8.0 a year earlier, against 8.8 in Lviv and 7.1 and climbing in Ternopil. Relative to earnings, western housing got dearer while Kyiv got cheaper.
Two Series, Never Blended
The seven-year change belongs to OLX. LUN's current levels sit lower and must be read separately: Lviv $75,400, Uzhhorod $70,000, Kyiv $68,000, Lutsk $63,500, Chernivtsi $60,000, Vinnytsia $57,000, Ternopil $54,000, Odesa $49,900, Ivano-Frankivsk $45,200, Dnipro $33,000, Kharkiv $24,000.
Momentum now shows up in LUN's annual changes: Ternopil +31%, Lutsk and Vinnytsia +27% each, Uzhhorod +18%, Ivano-Frankivsk +17%, Lviv +16%, Kyiv +4%, Dnipro −6%. Official data confirms the direction — the State Statistics Service records secondary prices up 82% and new builds up 87% since the fourth quarter of 2021, with new builds up 20.5% year on year in the second quarter of 2026, the fastest in five years, against construction costs up 30–50% this year.
The Rental Market Has Already Flipped
Prices doubled over seven years; western rents added 40% or more in the last twelve months alone. LUN's median one-room rent in Lviv is UAH 26,900, up 43% on the year and 9% in a month, with Uzhhorod up 40%, Ivano-Frankivsk 42% and Kharkiv 89% from a depressed base. Kyiv stands apart at UAH 18,000, unchanged for a year, with secondary supply up 43% in August.
That reverses the yield map. UAH 18,000 on a $68,000 Kyiv flat is 7.1% gross; UAH 26,900 on a $75,400 Lviv flat is 9.6%. The ceiling is visible: rent takes 75% of the average local wage in Uzhhorod, 66% in Lviv, 65% in Ivano-Frankivsk and 51% in Kyiv, while Ternopil region counts 20 tenants per listing. Two consecutive years of 40% rent growth are not available.
Which Drivers Expire and Which Remain
Western regional centres gained 82% to 189% on migration and relocation, and their limiting factor is affordability already at 65–75% of wages, plus any post-war reversal of population flows. Kyiv's 42% rests on capital status and new supply — six projects launched in seven months — and its rents are flat. Odesa and Dnipro, at 26% to 36%, keep a risk premium until the front moves. Kharkiv, Zaporizhzhia and Mykolaiv, down 29% to 32%, form the one segment already priced for war and the only one with a recovery option.
The arithmetic of ownership follows from that. A 2019 buyer in Ivano-Frankivsk more than doubled real capital and holds an asset yielding 9–10% gross. A Kyiv buyer merely matched inflation and nets 4%. According to analyst Ruslan Averin, the seven-year table maps where people relocated rather than where value now sits — and in 2026 value is concentrated where prices have not yet moved, provided the buyer can wait for the reason behind that stillness to end.