The revenue line is thinner than the headline suggests
Most previews of BlackRock focus on the earnings number. The more revealing exercise for the third quarter of 2026 is building the revenue line from its parts, because that is where the consensus looks stretched.
Assume average assets under management rise about 4% sequentially. Base fees would land close to $5.95 billion. Add roughly $580 million of technology revenue, about $400 million of distribution fees and some $85 million of advisory and other revenue, and the total reaches approximately $7.0 billion.
That leaves a gap. The $7.52 billion consensus implicitly requires around $500 million of performance fees, compared with $305 million in the second quarter and $516 million a year earlier. Performance fees from HPS and liquid alternatives, in other words, carry the burden of the revenue estimate.
Date, price and where the stock stands
BlackRock reports before the New York Stock Exchange opens on Wednesday 14 October, with the conference call at 7:30 a.m. New York time, as the company confirmed in a Business Wire release on 30 September. Morgan Stanley follows the next day.
Shares closed on Monday 12 October at $1,083.92, up 1.3% from the 2025 year-end close of $1,070.34 and 8.4% below the closing high of $1,182.84 set on 13 August. The stock jumped 6.6% on 15 July, the day of the second-quarter report, closing at $1,093.40, then slid with financials as yields rose, finishing 30 September at $1,058.29. That still represented a 10.1% quarterly gain from $961.56 on 30 June. At $1,083.92 the shares trade at about 19.3 times the Yahoo Finance consensus of $56.11 for full-year 2026 EPS.
A beat streak that keeps widening
BlackRock has exceeded the EPS consensus in each of the last four quarters, and the margin of outperformance has expanded rather than compressed.
| Quarter | Surprise vs Yahoo Finance estimate |
|---|---|
| Q3 2025 | 2.3% |
| Q4 2025 | 7.9% |
| Q1 2026 | 9.4% |
| Q2 2026 | 9.6% ($13.91 vs $12.69) |
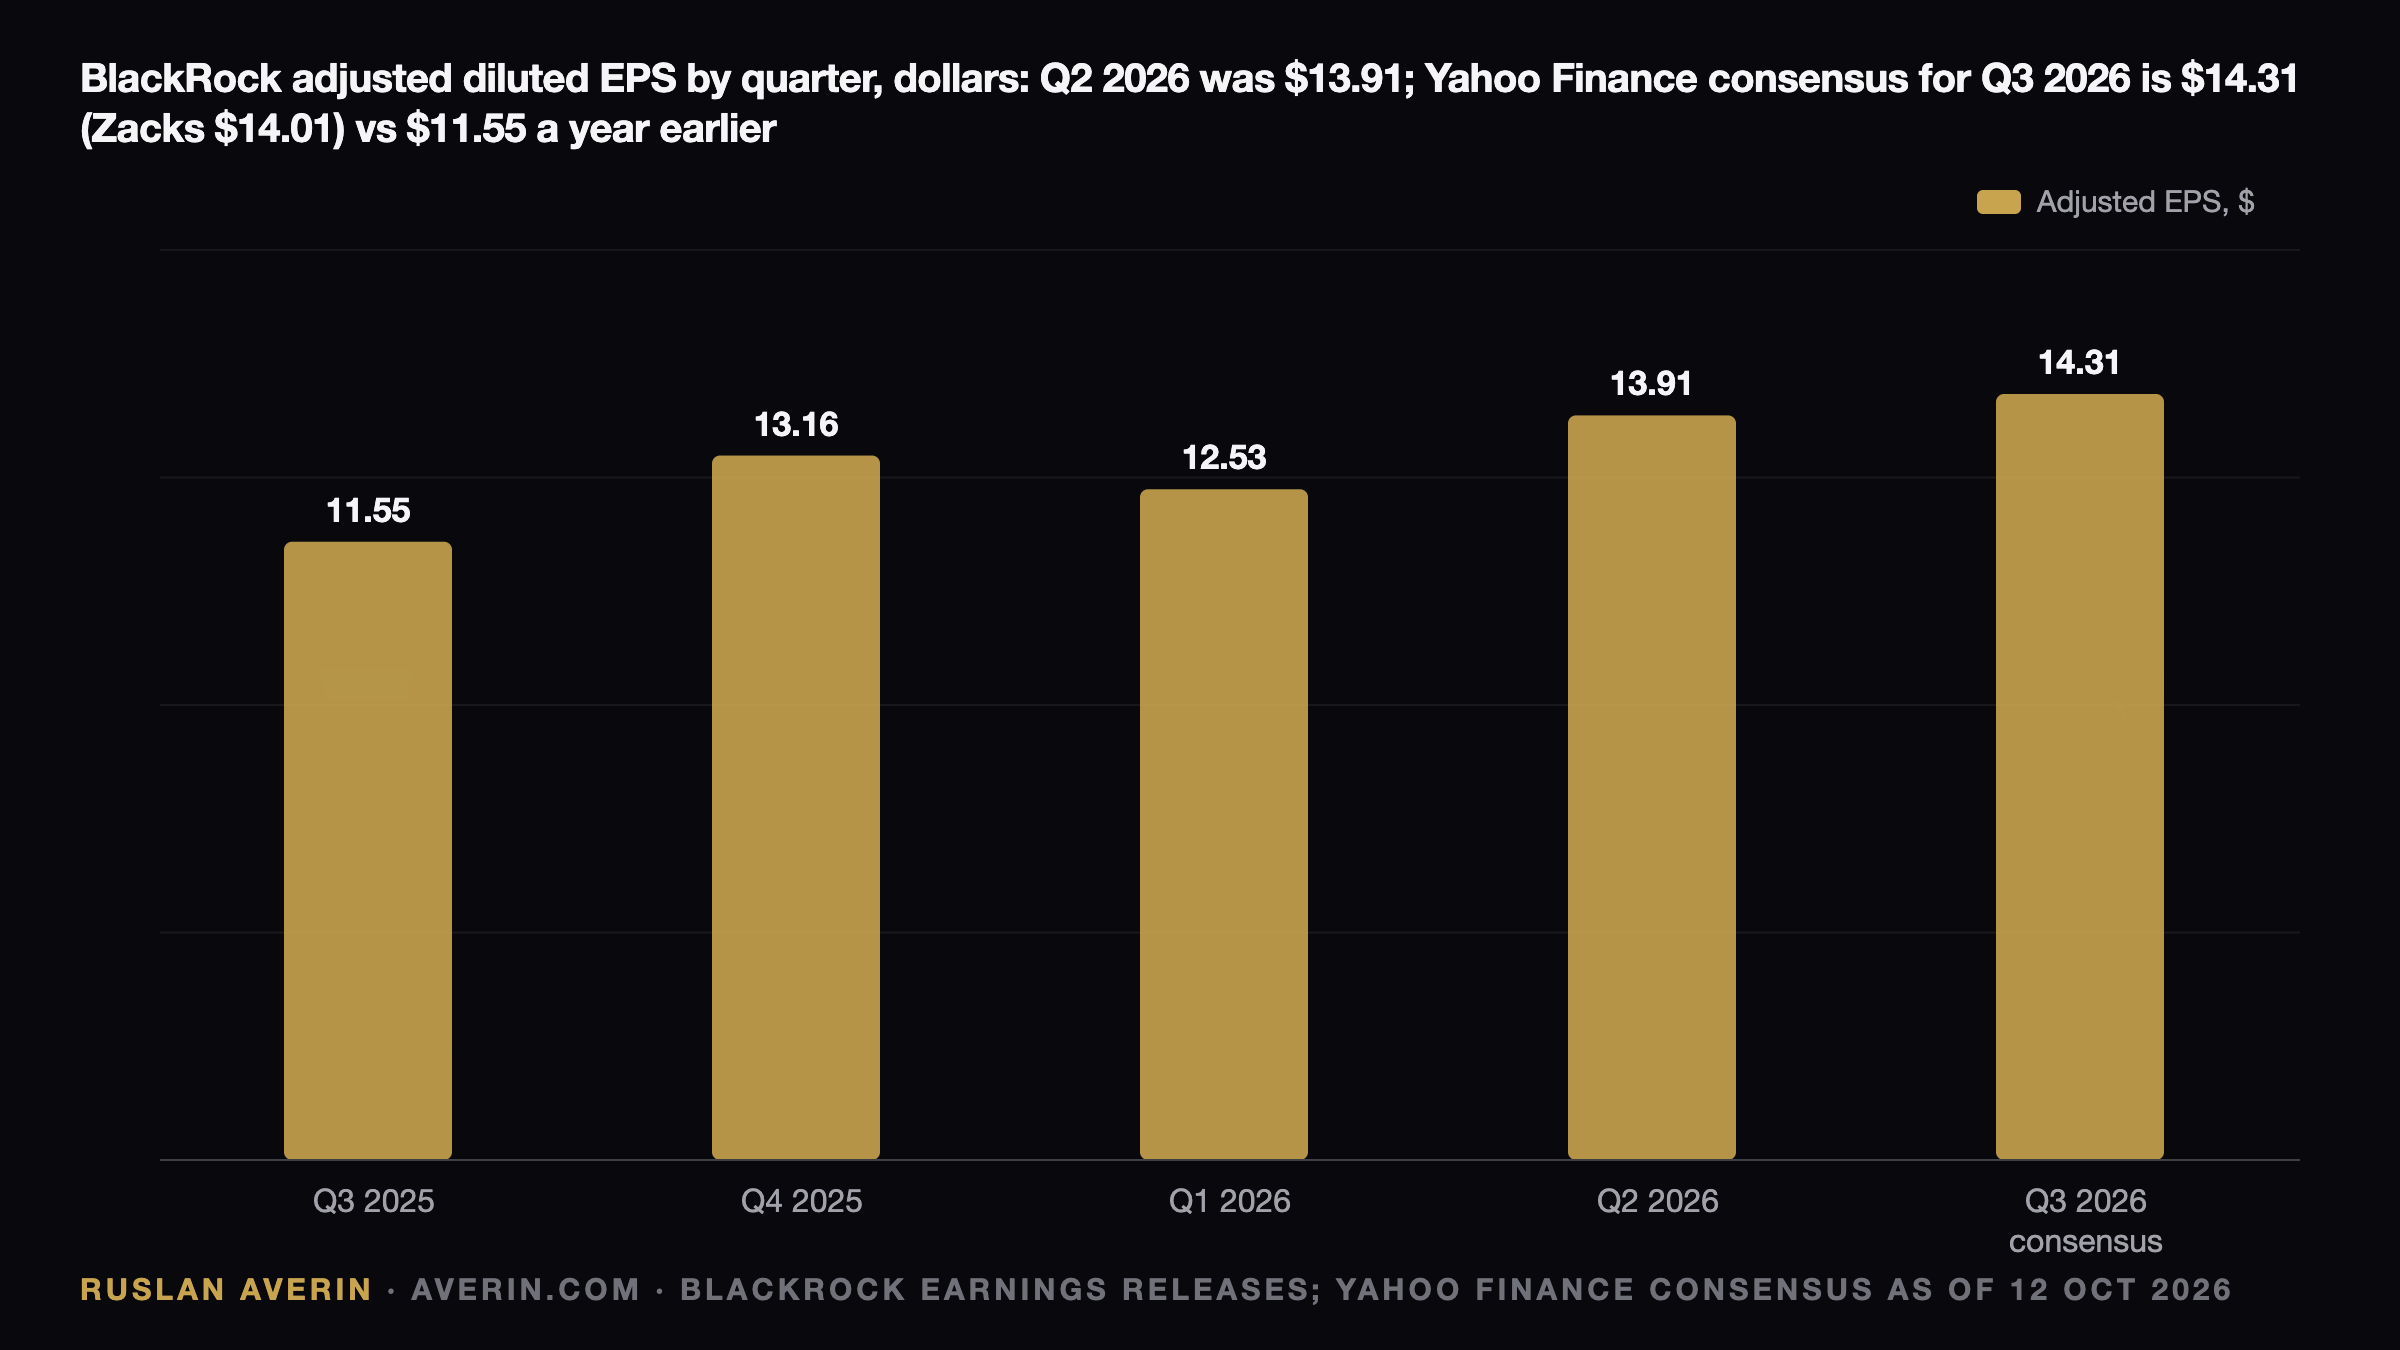
Against that record, the sequential move implied by consensus looks cautious: $13.91 to $14.31 is only about 3%. A year ago BlackRock earned $11.55 a share as adjusted on revenue of $6.51 billion, so $14.31 implies EPS growth of roughly 24% and $7.52 billion implies revenue growth of 15.5%.
The fee rate question behind every flow headline
Organic base fee growth was 8% annualised in the second quarter and 10% over the trailing twelve months. Laurence Fink described the quarterly figure as "well in excess of our target". A reading near 8% again would preserve the premium multiple; a slip to the mid-single digits would revive the long-running claim that BlackRock gathers assets faster than it gathers revenue.
The arithmetic sits in the fee rate. Base fees and securities lending revenue of $5.73 billion on average AUM of $14.85 trillion annualise to roughly 15.4 basis points in the second quarter, against about 15.6 basis points a year earlier. Low-fee ETFs and cash drag the rate lower; private markets and active ETFs lift it. Holding near 15.4 basis points would show the mix shift is working.
Technology services and subscription revenue, mostly Aladdin plus Preqin data, was $566 million in the second quarter, up 13% year on year, with annual contract value growing 15%. The year-ago base of $515 million points to roughly $580 million this time. Preqin now sits in both comparison periods, which explains why growth decelerated from 22% in the first quarter.
Flows: the engine and its weak spots
Over the twelve months to June, net inflows totalled $868 billion. The comparison quarter is demanding: in the third quarter of 2025 BlackRock took in $205 billion, including a then-record $153 billion into ETFs and $34 billion into cash, delivering 10% annualised organic base fee growth. Since then quarterly net inflows ran $342 billion, $130 billion and $192 billion.
iShares remains the platform's engine, pulling in $178 billion in the second quarter as ETF assets passed $6 trillion and first-half ETF inflows reached $310 billion. Weak spots were institutional index, with net outflows of $41 billion, and digital-asset ETFs, with outflows of $3 billion. Fixed income ETFs took in $66 billion in the second quarter, making bond ETF demand during a quarter of falling bond prices worth close attention.
Private markets held $329 billion at the end of June — only 2% of AUM but 11% of base fees and securities lending revenue. Net inflows of $15.4 billion were offset by $6.2 billion of realisations. The quarter laps the 1 July 2025 closing of HPS, which added $165 billion of client AUM, so private credit growth is now organic rather than acquired. Commentary on HPS flagship fundraising and GIP infrastructure pace will be read as the test of the $400 billion target for 2030.
The starting base and the market crosscurrents
BlackRock finished June with a record $15.34 trillion under management, after net inflows of $192 billion and market appreciation of $1.28 trillion. The mix was $8.89 trillion in equities, $3.39 trillion in fixed income, $1.35 trillion in multi-asset and $1.07 trillion in cash.
Markets then moved in opposite directions. The S&P 500 rose 2.0% between the closes of 30 June and 30 September, and the iShares MSCI ACWI ETF rose 1.2%. The iShares Core US Aggregate Bond ETF returned about minus 3.5% including distributions, as the 10-year Treasury yield climbed above 5% following the Fed's September hike.
On rough arithmetic those gains and losses largely cancel, leaving period-end AUM dependent on flows: with net inflows similar to recent quarters, the figure would land around $15.5–15.6 trillion. That is an RFC Capital Research estimate, not a company figure. Average AUM matters more for revenue, and the quarter opened at $15.34 trillion versus a second-quarter average of $14.85 trillion.
Margin, capital returns and the four markers
The adjusted operating margin reached 45.9% in the second quarter, the highest in almost five years. BlackRock also lifted planned buybacks to $550 million a quarter and to $2 billion for 2026, alongside a quarterly dividend of $5.73.
In the view of analyst Ruslan Averin, four lines will drive the reaction: organic base fee growth at or above roughly 8%; total net flows measured against about $200 billion, with the year-ago $205 billion as the visible comparison; performance fees near $500 million, on which the revenue consensus quietly depends; and private markets fundraising commentary from HPS and GIP.
Should flows and organic growth track recent quarters, Averin expects a muted share price response, since the stock has already recovered from its September dip and consensus assumes 24% EPS growth. The asymmetric outcome is a quarter where the EPS beat arrives via performance fees while organic growth falls below 5% — a strong headline resting on a weakening recurring base.