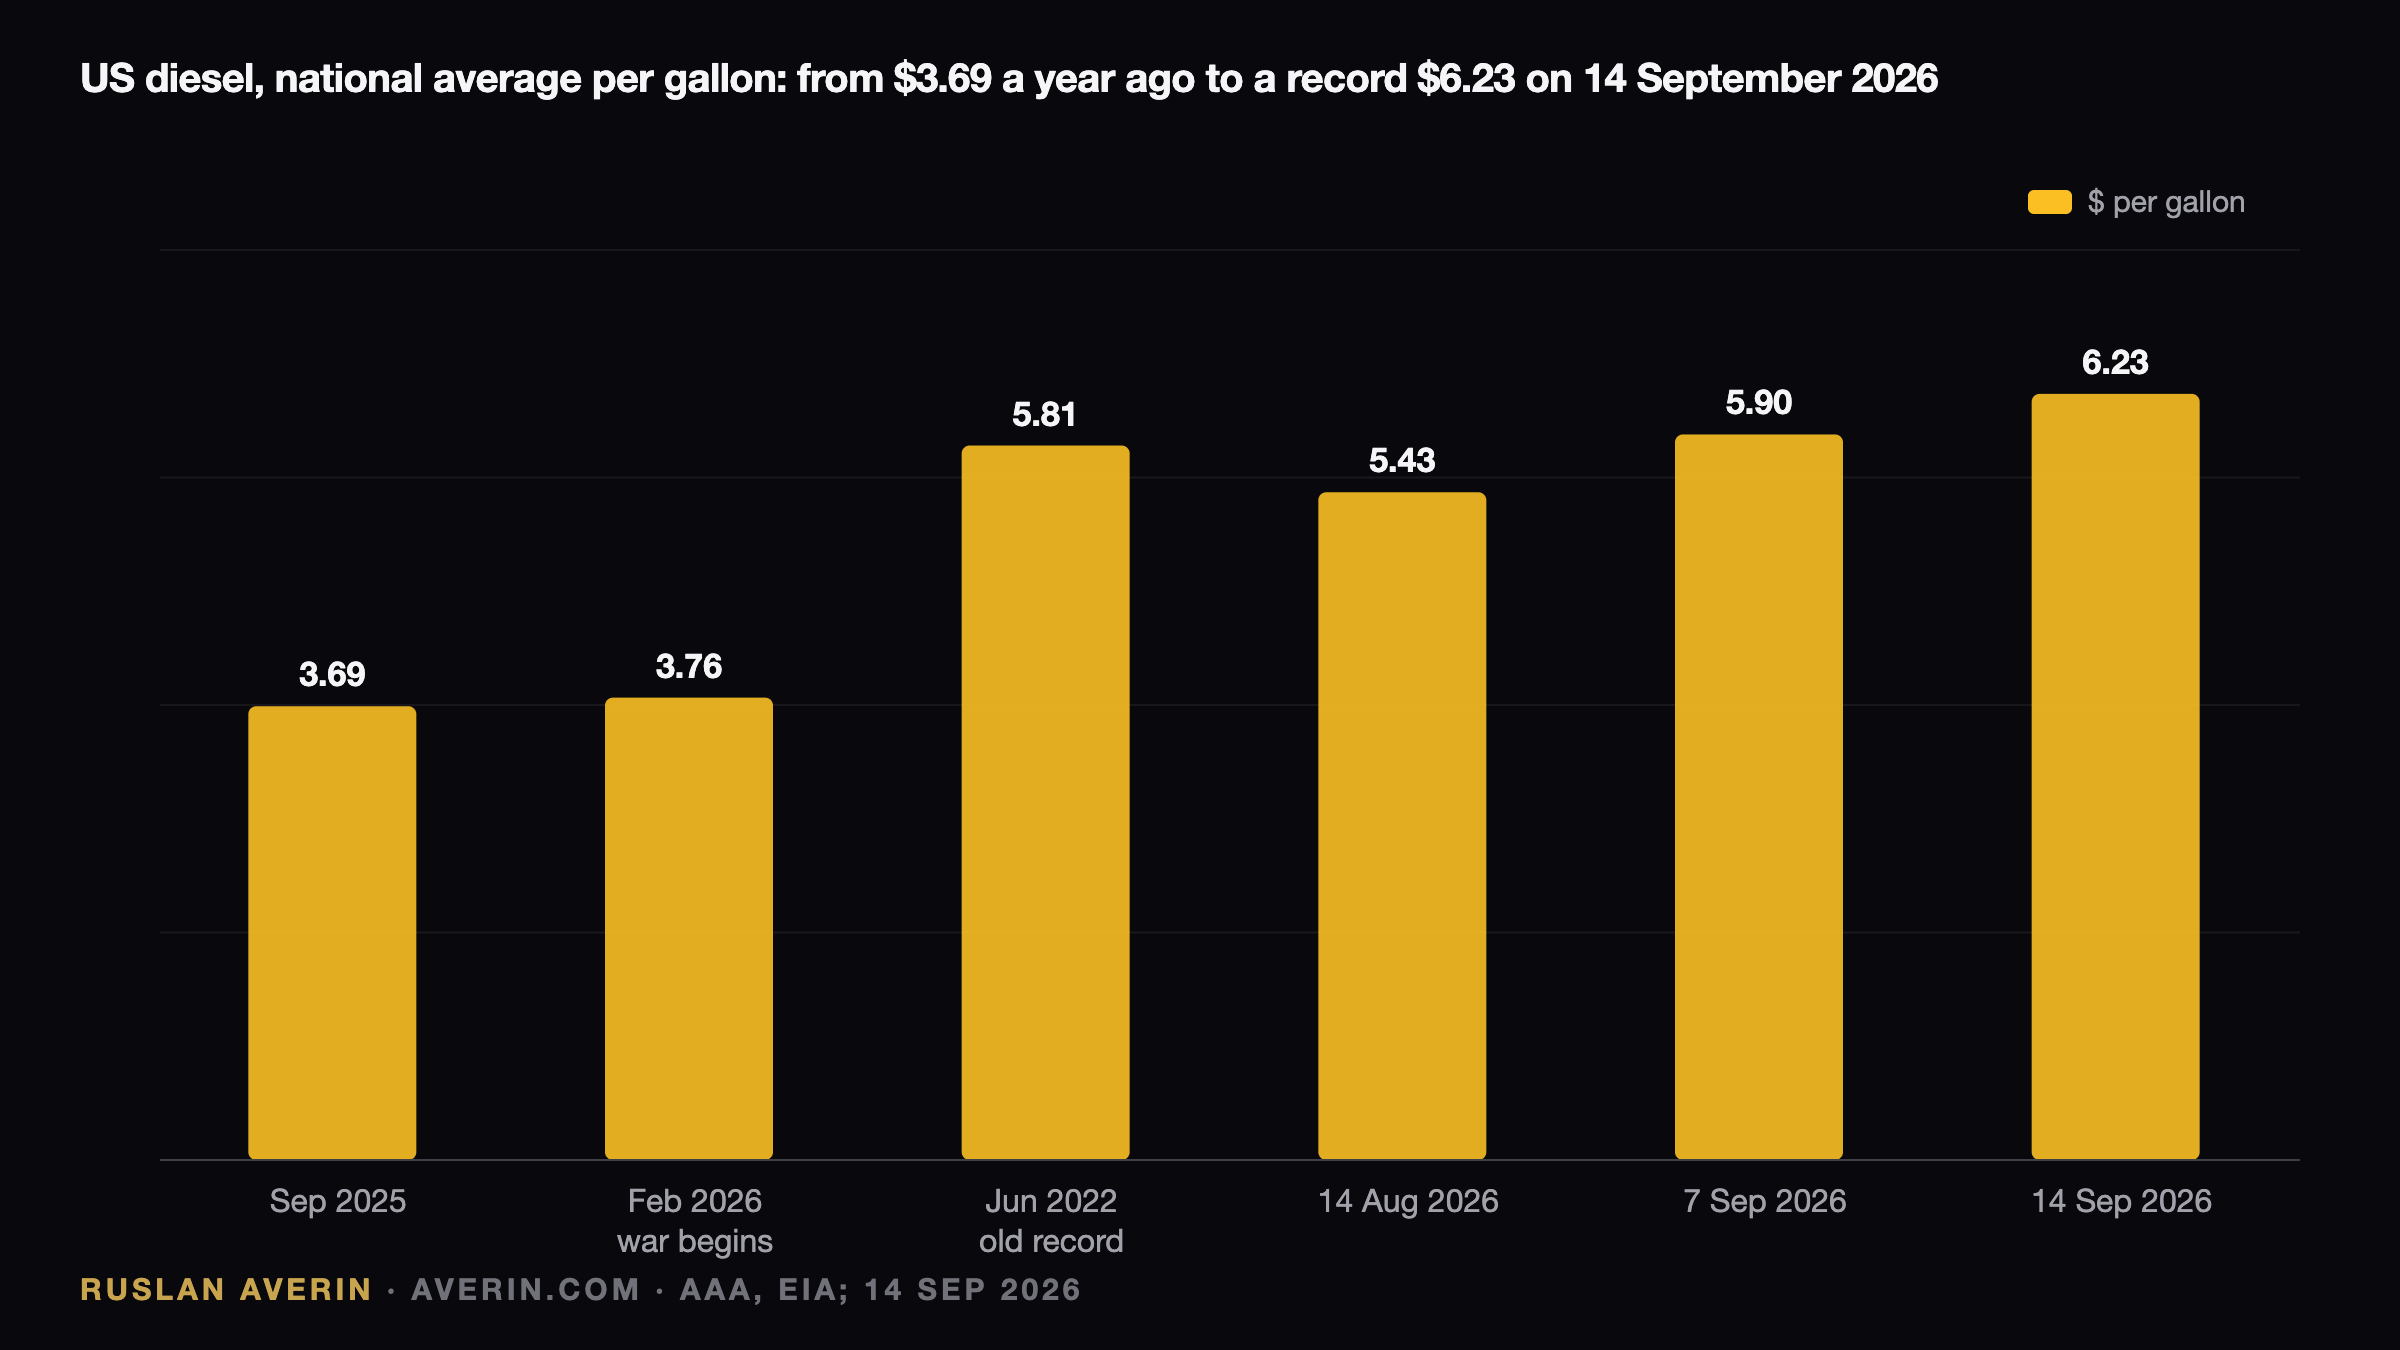
A product crisis wearing a crude costume
Two events landed on the same morning of 14 September 2026: US diesel hit a record $6.23 a gallon, and the President of the United States publicly asked Kyiv to stop striking Russian refineries. The link between them is the defining story in energy markets this week. Crude is cheaper than it was in June 2022, when diesel last set a record. The refined barrel is not.
The split between fuels makes the diagnosis obvious. Gasoline sits at $4.32, up 36% year on year — expensive, but no record. Diesel is up roughly 60% since the war began and 69% year on year. Gasoline tracks crude; diesel tracks refining capacity and shipping routes, and both of those have been physically damaged.
The record, week by week
| Date | US diesel, AAA average | Note |
|---|---|---|
| September 2025 | $3.69 | one year ago |
| Late February 2026 | $3.76 | start of the Iran war |
| June 2022 | $5.81 | previous all-time record |
| 14 August 2026 | $5.43 | one month ago |
| 4 September 2026 | $5.85 | 2022 record broken |
| 11 September 2026 | $6.05 | first close above $6 |
| 14 September 2026 | $6.23 | record; Pennsylvania $6.35, California $7.98 |
The margin data confirms the bottleneck. The diesel crack spread — the refiner's spread between crude and product — reached $108 a barrel on 3 September, more than double 2022 peak territory. Brent traded at $108 on 14 September after a 3.5% jump, WTI at $103. Crude is $28 a barrel below its 2022 record while diesel clears the old high by 42 cents.
Three broken supply lines
The Gulf accounts for the first. Following the Strait of Hormuz attacks and the Bab al-Mandab closures, Gulf diesel exports in August ran at just over a quarter of their February level, roughly 390,000 barrels a day short. On 10 and 11 September drones launched from Iraq struck pump stations on the Saudi East-West pipeline, the 1,200 km link from Abqaiq to Yanbu that moved four to five million barrels a day around Hormuz. It is shut.
Russia accounts for the second. Ukrainian drones have hit all eleven of the largest Russian refineries during 2026: Omsk, Kirishi, Ryazan, Kstovo, Yaroslavl, Volgograd, Perm, Moscow, Novokuibyshevsk, Syzran and Bashneft. Kstovo went down again on 26 August, Kirishi on 30 August. Reuters put halted or reduced capacity at nearly a quarter in May, the IEA at more than 20%, Ukraine's General Staff at 42.7%. Together the Gulf and Russia supplied about 45% of seaborne diesel trade before the war.
Moscow's domestic response shows the strain: diesel exports by non-producers were banned from 8 July, with the ban extended to 30 September, and 55 of 83 regions have reported shortages or rationing.
Why no refinery can fix it quickly
The third constraint is the refining system itself. Andy Lipow's assessment on 11 September was blunt: refiners have already maximised diesel output and "simply can't get any more diesel out of the system." Nothing in the chain offers fast relief. Europe illustrates the consequence — the EU average is €2.03 a litre, up 35% year on year, with Germany at €2.33 and the Netherlands at €2.44, and inventories well below normal heading into autumn.
The political arithmetic in Washington
The Brown University cost tracker frames the domestic pressure: the diesel spike has cost Americans more than $46 billion since the war began, over $350 per household, on top of $55 billion for gasoline. August PPI printed +5.4% year on year with the diesel component at +24.1%. UPS lifted its ground fuel surcharge to 28.5% this week.
That is the backdrop to Doonbeg. Trump told reporters that Zelenskyy "has to stop knocking out diesel fuel in Russia," insisting "there are plenty of other targets" because the strikes are "hurting the world." With midterms on 3 November, he had already predicted on 11 September that "right after the election, oil prices are going to be tumbling downward."
Kyiv's counter-argument
Ukraine's position is that refineries are legitimate military targets and that Russian oil "funds and directly fuels" the invasion. Foreign Minister Sybiha described the shortage as "Putin's terror knocking directly on the doors of the EU and NATO." For Kyiv the campaign is the only instrument that reaches the Russian budget without waiting for sanctions; Western pump prices are that instrument becoming visible.
The same squeeze at Ukrainian pumps
Ukraine pays too. On 14 September the average price of A-95 was UAH 85.01 a litre, up 1.05 in three days, while diesel stood at UAH 95.94, up 1.31. Fuel is 38.7% dearer than a year ago and pushed August inflation to 8.1%. The National Bank raised its policy rate to 15.5% on 30 July citing that shock, and has sold more than $1 billion a week for nine weeks to hold the hryvnia at 44.6.
Where the trade has moved
Refining equities captured the windfall first. Marathon Petroleum and Valero roughly doubled this year and Phillips 66 gained about 60%, against 11% for the S&P 500, with $12.6 billion in combined second-quarter earnings. Then came 14 September: Valero fell 1.9%, Marathon 1.1%, Phillips 66 1.0% — while crude rose 3.5%. Rising crude against a static product price narrows the crack.
Shipping diverged. Scorpio added 0.3% and Frontline 1.4%, because diesel still has to sail from South Korea to Rotterdam and someone is paid to move it. In analyst Ruslan Averin's view the refiners have banked their year and tankers are the remaining expression, while the sharper implication belongs to bondholders: a fuel price contributing a third of a monthly CPI print is precisely why the Federal Reserve is set to raise rates on Wednesday.