The number that now sits on the NBU website
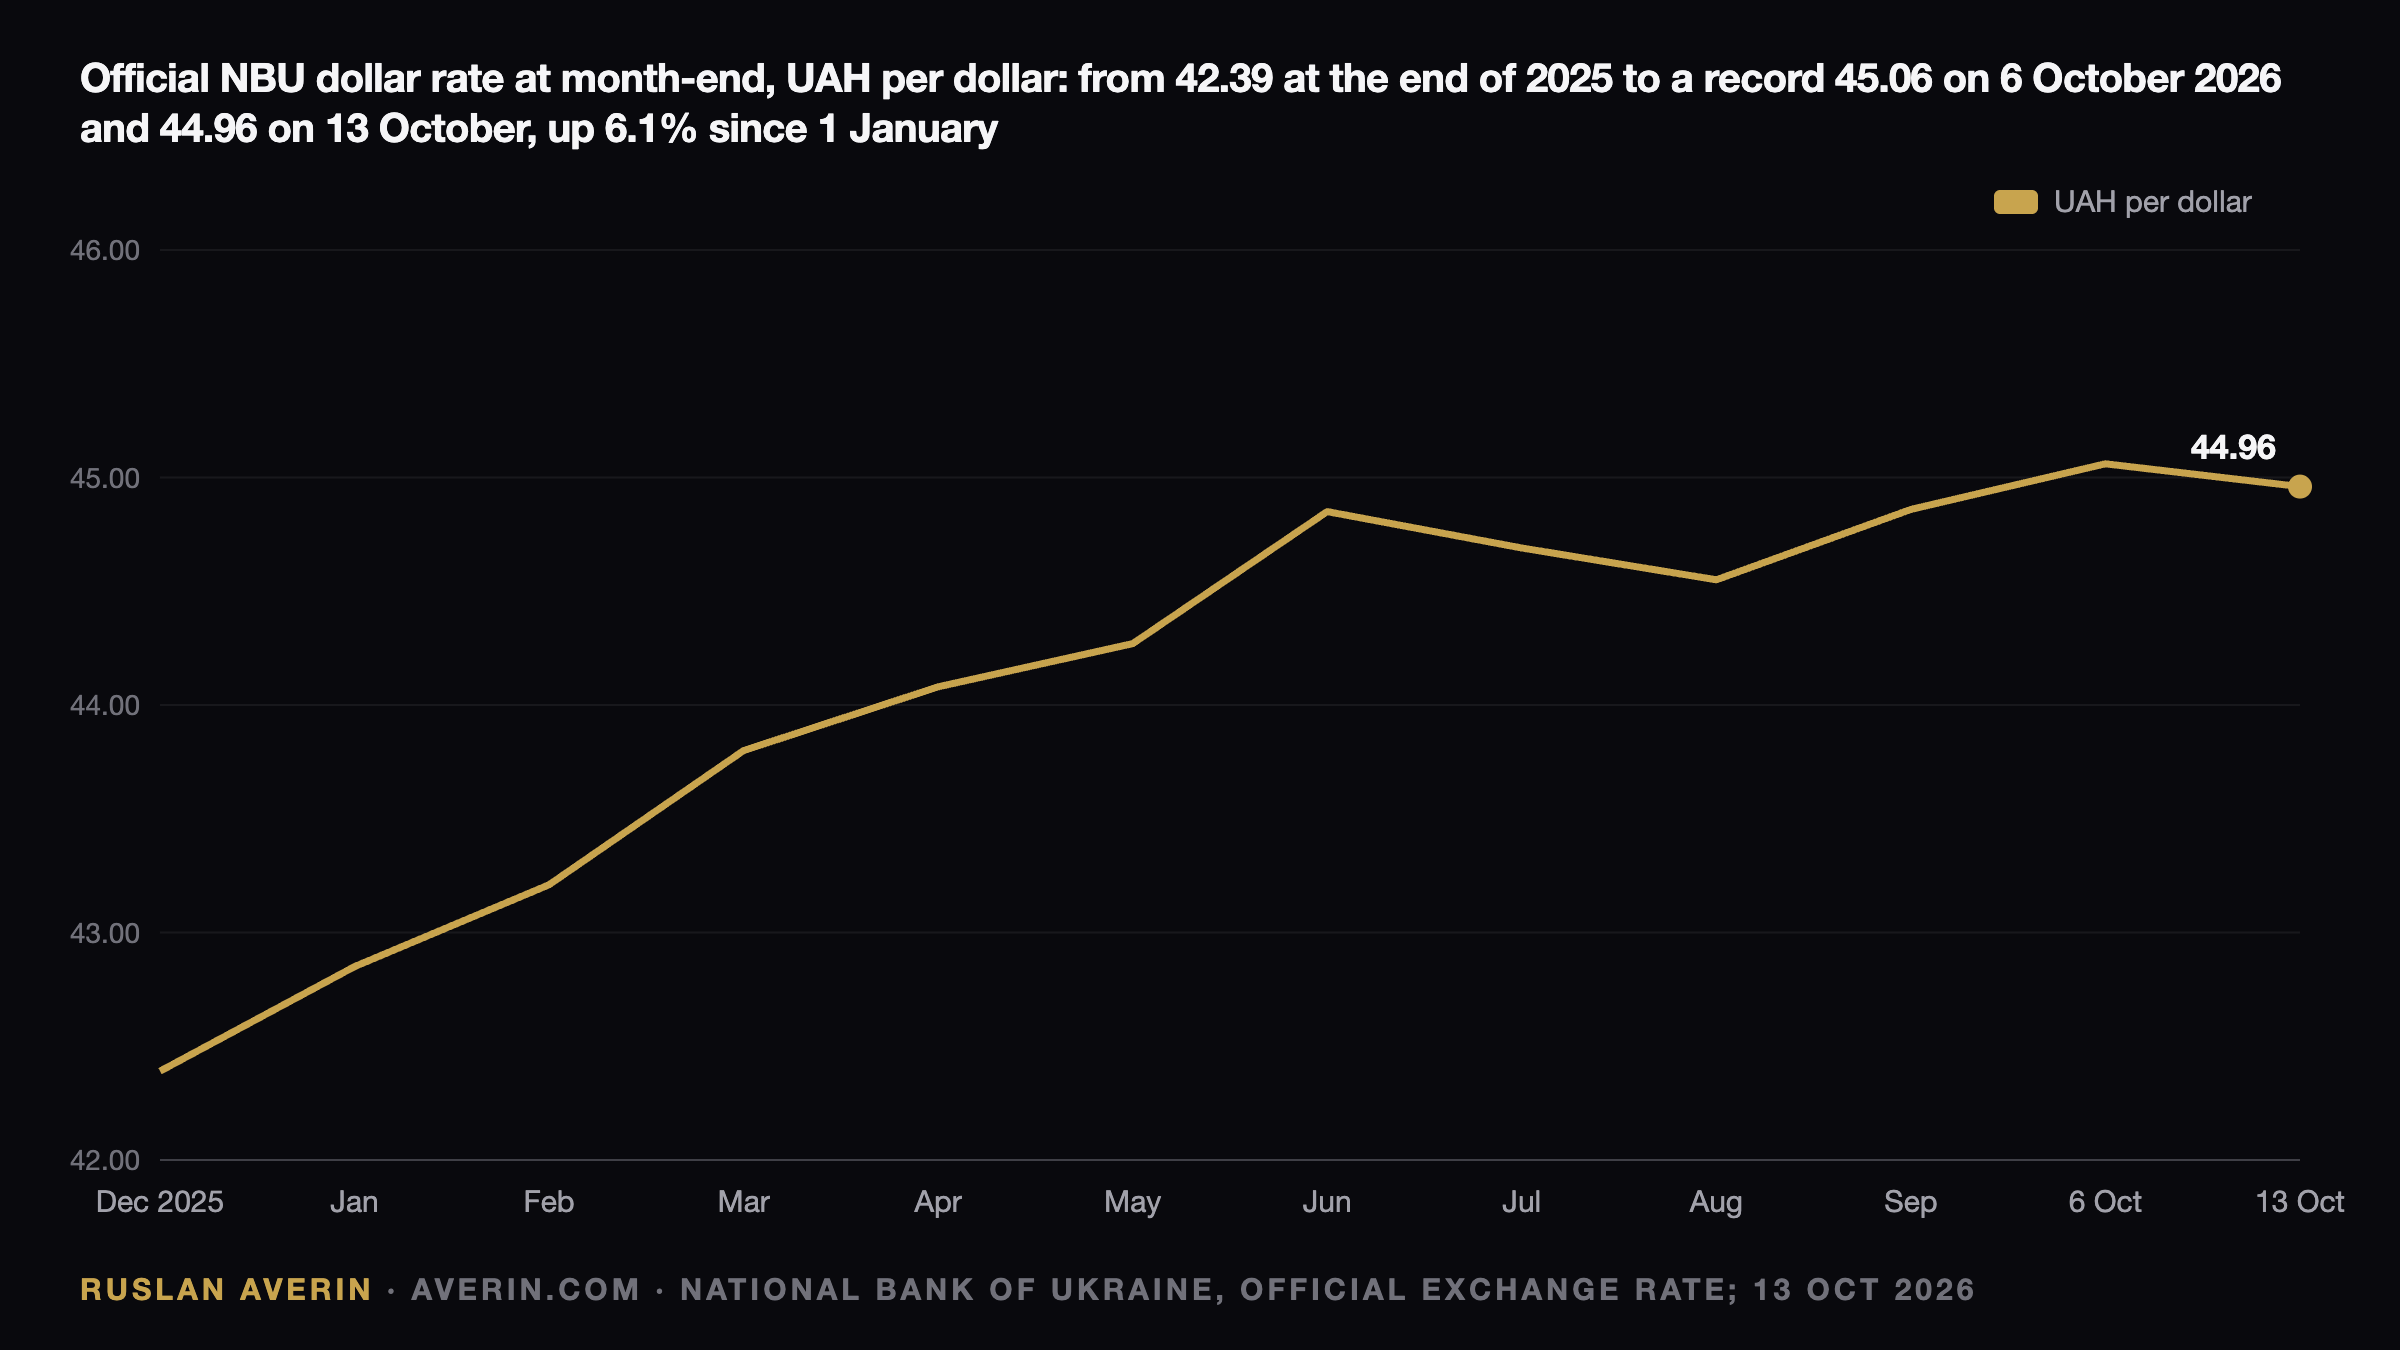
A level that first appeared in exchange-office windows in September has moved into official statistics. On Tuesday 13 October the National Bank of Ukraine fixed the dollar at UAH 44.9567, 7 kopecks weaker than the previous day. Seven days earlier, on 6 October, the official quote touched UAH 45.0564 — the weakest reading in the history of the hryvnia. The rate clawed back to 44.85 by Friday, then slipped once more.
The bill for holding that line
Keeping the figure near 45 rather than above it is not free. Between 5 and 9 October the NBU sold $1,248.8 million on the interbank market and bought just $0.07 million. That was $63.9 million, or 4.9%, below the previous week, and the thirteenth consecutive week with sales above $1 billion. The sequence started on 13 July and now totals roughly $15.3 billion.
The annual picture is sharper still. Net sales since 5 January reach $40.02 billion, already ahead of the $36.06 billion recorded across the whole of 2025. With almost three months left on the calendar, 2026 stands as the heaviest year of interventions since the start of the full-scale invasion.
Where reserves absorbed the pressure
International reserves closed September at $47.1 billion, a decline of 3.2% over the month, after the central bank parted with $5.45 billion. Partners topped up the government's accounts with $890.4 million routed through the World Bank. A separate $3.81 billion arrived from the EU under the Ukraine Support Loan, but it financed defence and never entered reserves. The NBU frames $47.1 billion as four months of future imports and "sufficient to maintain the stability of the currency market".
Official, cash and euro quotations compared
The official rate has weakened 6.1% since 1 January, when it stood at UAH 42.35, and 8.1% over twelve months from UAH 41.60 on 13 October 2025. It crossed 44.8 at the end of June, firmed to 44.55 by late August and reached 44.86 in September.
Cash trades slightly wider. For the week to 9 October, Interfax-Ukraine put the average cash quote at UAH 44.66 to buy and UAH 45.09 to sell, meaning $1,000 in notes costs around UAH 45,090. The euro moved in the opposite direction, at UAH 50.24 on 13 October versus a record 52.25 on 24 August, reflecting dollar strength abroad.
Three engines behind corporate demand
Companies dominate the buying side. From Monday to Thursday of the reporting week legal entities purchased a net average of $156.6 million a day, down from $217.2 million in the comparable days a week earlier. Households took $46.9 million a day, against $50.5 million.
Energy comes first. The NBU's inflation commentary shows fuel prices 46.2% higher in September than a year before, and most fuel, plus part of winter gas and electricity, is imported and settled in foreign currency. Taras Lesovyi of Globus Bank points to energy risks and "gradual growth in import demand" as October's main pressure.
External accounts come second. Minfin.com.ua reports a balance-of-payments deficit of $9.66 billion for January to August, the worst for that period since at least 2010, including $3.1 billion in August alone.
Budget mechanics come third. Finance Minister Serhiy Marchenko told the Verkhovna Rada on 12 October that Ukraine needs almost $27 billion from partners by year-end, part of it conditional on laws still unpassed. To protect cash for defence, pensions, wages and social payments, the government suspended UAH 18 billion of VAT refunds, deferred about UAH 39 billion of spending and left UAH 46 billion of payments unprocessed on the treasury account.
That freeze works in both directions. Exporters awaiting refunds lack hryvnia and sell more of their foreign earnings, which supports the currency this month. The underlying signal is less comfortable: until aid lands, every $1.2 billion week is financed out of reserves.
What the forecasters and the budget assume
The NBU publishes no exchange-rate forecast, operating a regime of managed flexibility and smoothing swings in both directions. The key rate is 16% after the 17 September hike. A new rate decision and macroeconomic forecast are due on 29 October, with the full Inflation Report on 5 November. September inflation of 10.0%, well above the July path, keeps a further increase on the table.
Globus Bank's Lesovyi expects the interbank dollar at UAH 44.7–45.3 and cash at 44.8–45.4 until 18 October, with the euro at 50–51.5 on the interbank market. The 2026 state budget was drafted on an average rate of UAH 45.7, while the actual average from 1 January to 13 October is near UAH 44.10, leaving the assumption comfortably above reality. The 2027 draft uses an average of UAH 47.1 and UAH 48.3 at end-2027.
In the view of analyst Ruslan Averin, the base case for December is a rate between 45 and 46 rather than a jump: the NBU has both the reserves and the demonstrated willingness to keep selling into the new year. The risk case is a delay in the $27 billion, which would force a choice between faster reserve losses and a weaker hryvnia during peak winter imports.
Savings arithmetic on 12–13 October
| Instrument | Headline yield | After tax | Note |
|---|---|---|---|
| Hryvnia deposit, 12 months (UIRD) | 14.03% | about 10.80% | 23% tax: 18% income tax plus 5% military levy |
| OVDP maturing September 2027 | 15.14% | 15.14% | 6 October auction, interest untaxed |
| OVDP maturing March 2029 | 16.49% | 16.49% | same auction |
| Dollar deposit, 12 months (UIRD) | 1.13% | about 0.87% | no FX bonds placed in September or October |
| Euro bonds, 30 June and 7 July | 3.18% and 3.08% | — | last foreign-currency placements |
Households held a record UAH 167.5 billion of OVDP on 1 October. The comparison reduces to a breakeven: a hryvnia deposit at 10.80% net wins unless the dollar ends the year above about UAH 49.4, and an OVDP at 15.14% wins unless it passes about UAH 51.3. Both thresholds exceed every forecast cited here, including the 48.3 pencilled in for the end of 2027, fourteen months away.
Inflation supplies the second test. With prices up 10.0% in a year, a net deposit return of 10.80% leaves a real gain under 1%, while OVDP at 15.14% leave roughly 4.7%. The dollar itself added 8.1% against the hryvnia over twelve months and paid almost nothing on top.
Analyst Ruslan Averin reads the numbers as favouring hryvnia instruments for money that will be spent in hryvnia within a year, with dollars retained as a hedge against sharp devaluation and for costs priced abroad, such as travel or tuition. The breakeven maths argues for splitting savings rather than betting on a single rate. Two events would change the calculation: a 29 October decision that falls behind inflation, or a further slip in partner financing.