The Long End Hiked First
On 14 September 2026 the 10-year Treasury touched 5.00% intraday, the first time since October 2023, while the two-year traded at 4.65%. The Federal Reserve has not raised rates in three years and two months, yet the curve has already delivered the increase. The decision due on Wednesday 16 September at 2:00 pm New York time is, in pricing terms, a confirmation rather than a surprise.
Six Weeks That Rewrote the Odds
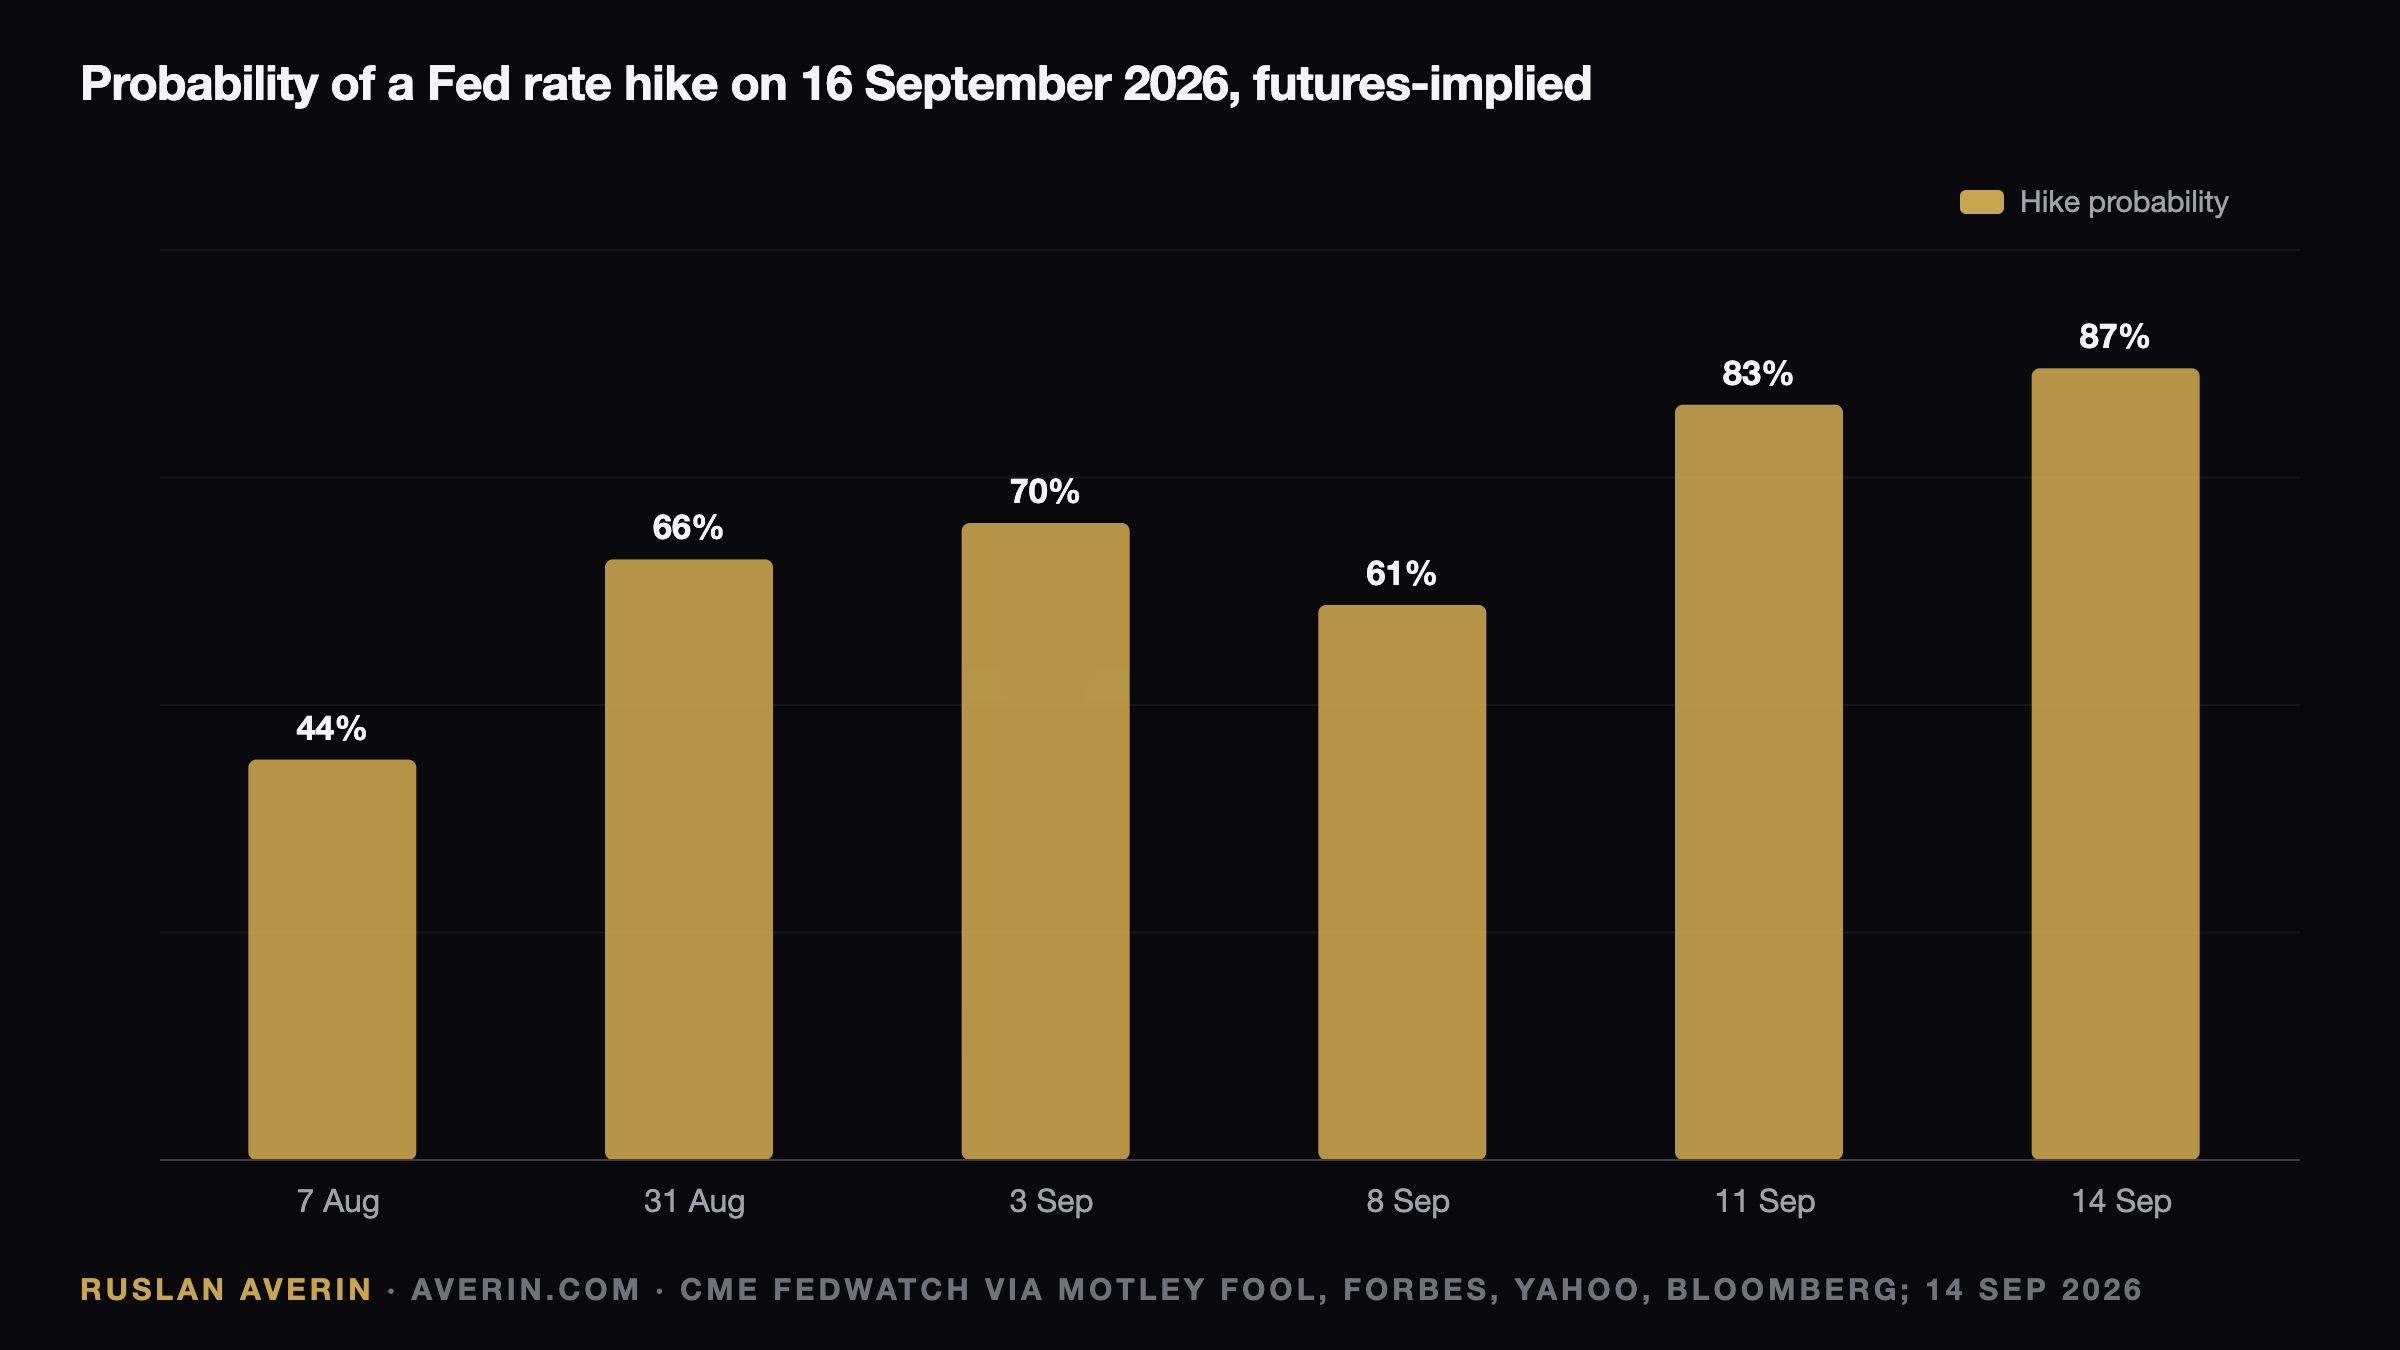
Futures now put the probability of a hike at about 87%. A week earlier the figure sat closer to 60%, and on 7 August, in the aftermath of a weak July jobs report, it was 44%. Three releases moved the market in the same direction, and the Reuters poll published on 14 September showed 86 of 101 economists expecting a 25 basis point increase against 70% forecasting a hold seven days before.
| Date | Release | Number | Consensus |
|---|---|---|---|
| 28 Aug | Warsh at Jackson Hole | PCE 3.7% over 12 months, 4.1% over 6 annualised | "committed to a discipline, not to a decision" |
| 4 Sep | August payrolls | +162,000, unemployment 4.1% | +53,000 |
| 11 Sep | August CPI | headline +0.4% m/m, 3.4% y/y; core +0.3%, 2.4% y/y | core +0.2% m/m |
| 14 Sep | Reuters poll | 85% expect +25 basis points on 16 Sep | 30% a week earlier |
How the Range Got to 3.50–3.75%
The target has been unchanged since the cut of 11 December 2025. Before that the committee eased six times from the 5.25–5.50% peak: 50 points in September 2024, then 25 in November and December 2024, followed by 25 each in September, October and December 2025. The last tightening move was on 26 July 2023. Wednesday's expected step takes the range to 3.75–4.00%.
An Energy Shock the Committee Refuses to Look Through
Gasoline accounted for a third of the August CPI increase on its own, rising 3.9% for the month and 27.4% year on year, with energy overall up 16.3%. That reflects the Strait of Hormuz oil shock and, since last week, the shutdown of the Saudi East-West pipeline, with Brent above $106. The July statement itself described the overshoot as partly a supply shock "including energy".
Textbook practice is to look through such shocks. The July vote, however, was 9–3, with Hammack, Kashkari and Logan all pushing for a hike — the first three-way dissent in the same direction since 2016. Warsh framed the rationale in August: "Inflation is running above our 2 percent target. So the Fed's predominant focus right now should be on prices."
He added that while summer readings beat expectations, "they do not tell me that underlying trends have meaningfully improved." Core CPI at 2.4% is a five-year low, but the chair chose to cite six-month annualised PCE at 4.1%. Scott Anderson of BMO argued on 14 September that the Fed's inflation-fighting credentials are on the line and hawkish rhetoric must be backed by action.
What Duration Holders Are Absorbing
Treasury par yields on 14 August stood at 4.17% for two years, 4.51% for ten and 5.25% for thirty. By the 11 September close they were 4.35%, 4.96% and 5.38%. The long end outrunning the front end inverts the usual hiking-cycle pattern, where the two-year leads. Futures now imply roughly four increases by July 2027, and 53% of Reuters respondents expect at least one more by end-March.
For holders of duration, the arithmetic is uncomfortable. A 30-year at 5.38% pays a coupon unavailable through most of the last two decades, yet another 25 basis points at the long end costs roughly 3.7% of price. The 30-year has been the least sensitive maturity this month, adding 13 points, precisely because it already carried the inflation premium.
Mortgages, Gold and the 5% Competitor
Mortgages track the 10-year with a lag. Freddie Mac's 30-year average was 6.76% for the week of 10 September, against 6.71% the prior week and 6.35% a year earlier — a print that predates the post-CPI move, so the 17 September reading should be higher.
Gold recorded three consecutive weekly declines and traded below $4,300 on 14 September, its lowest in over a month. As long as four hikes remain priced, the headwind persists regardless of Middle East headlines. Equities were down under 1% at midday: S&P 500 −0.7%, Nasdaq −0.8%, Dow −0.4%, with the VIX up 10% to 17.5, alongside an AI sell-off in chips and oil above $100.
Three Ways Wednesday Can Land
The most likely outcome is a 25 basis point hike with dots showing two more in 2026: the front end sells, the long end holds steady, gold falls and the dollar firms. A hike paired with a one-and-done dot plot would rally the curve, push the 10-year back under 4.90%, and give gold a relief bounce with the dollar flat.
The third path, priced at about 13%, is a hold with hawkish language. In analyst Ruslan Averin's view this is the scenario worth watching: after the August speech and with 87% priced, a pause would read as the Fed blinking at a supply shock, steepening the curve and pushing 30-year yields through 5.50%.
Positioning Into the Dot Plot
A patient stance ahead of 2:00 pm is defensible. Long Treasuries at a 5.38% coupon compound regardless of the next 25 points, and a move through 5.50% argues for adding rather than selling. Cash earmarked for short-dated paper can wait on the dot plot: if the median shows two more hikes this year, six-month bills at 4.3% and rising beat a two-year locked at 4.65%.
Averin frames the week's real event as the press conference rather than the statement. Warsh has said the Fed is "committed to a discipline"; Wednesday will show what that discipline is expected to cost through 2027.