A quarter that tests volume over price
Eli Lilly's growth over the past year has rested on one trade: sell far more tirzepatide and accept lower realized prices for it. Third-quarter 2026 results, due before the US open on Thursday 29 October with the conference call at 10:00 ET (16:00 Kyiv), will show whether that trade still clears. The company confirmed the schedule on 15 October.
The numbers the market carries into the print
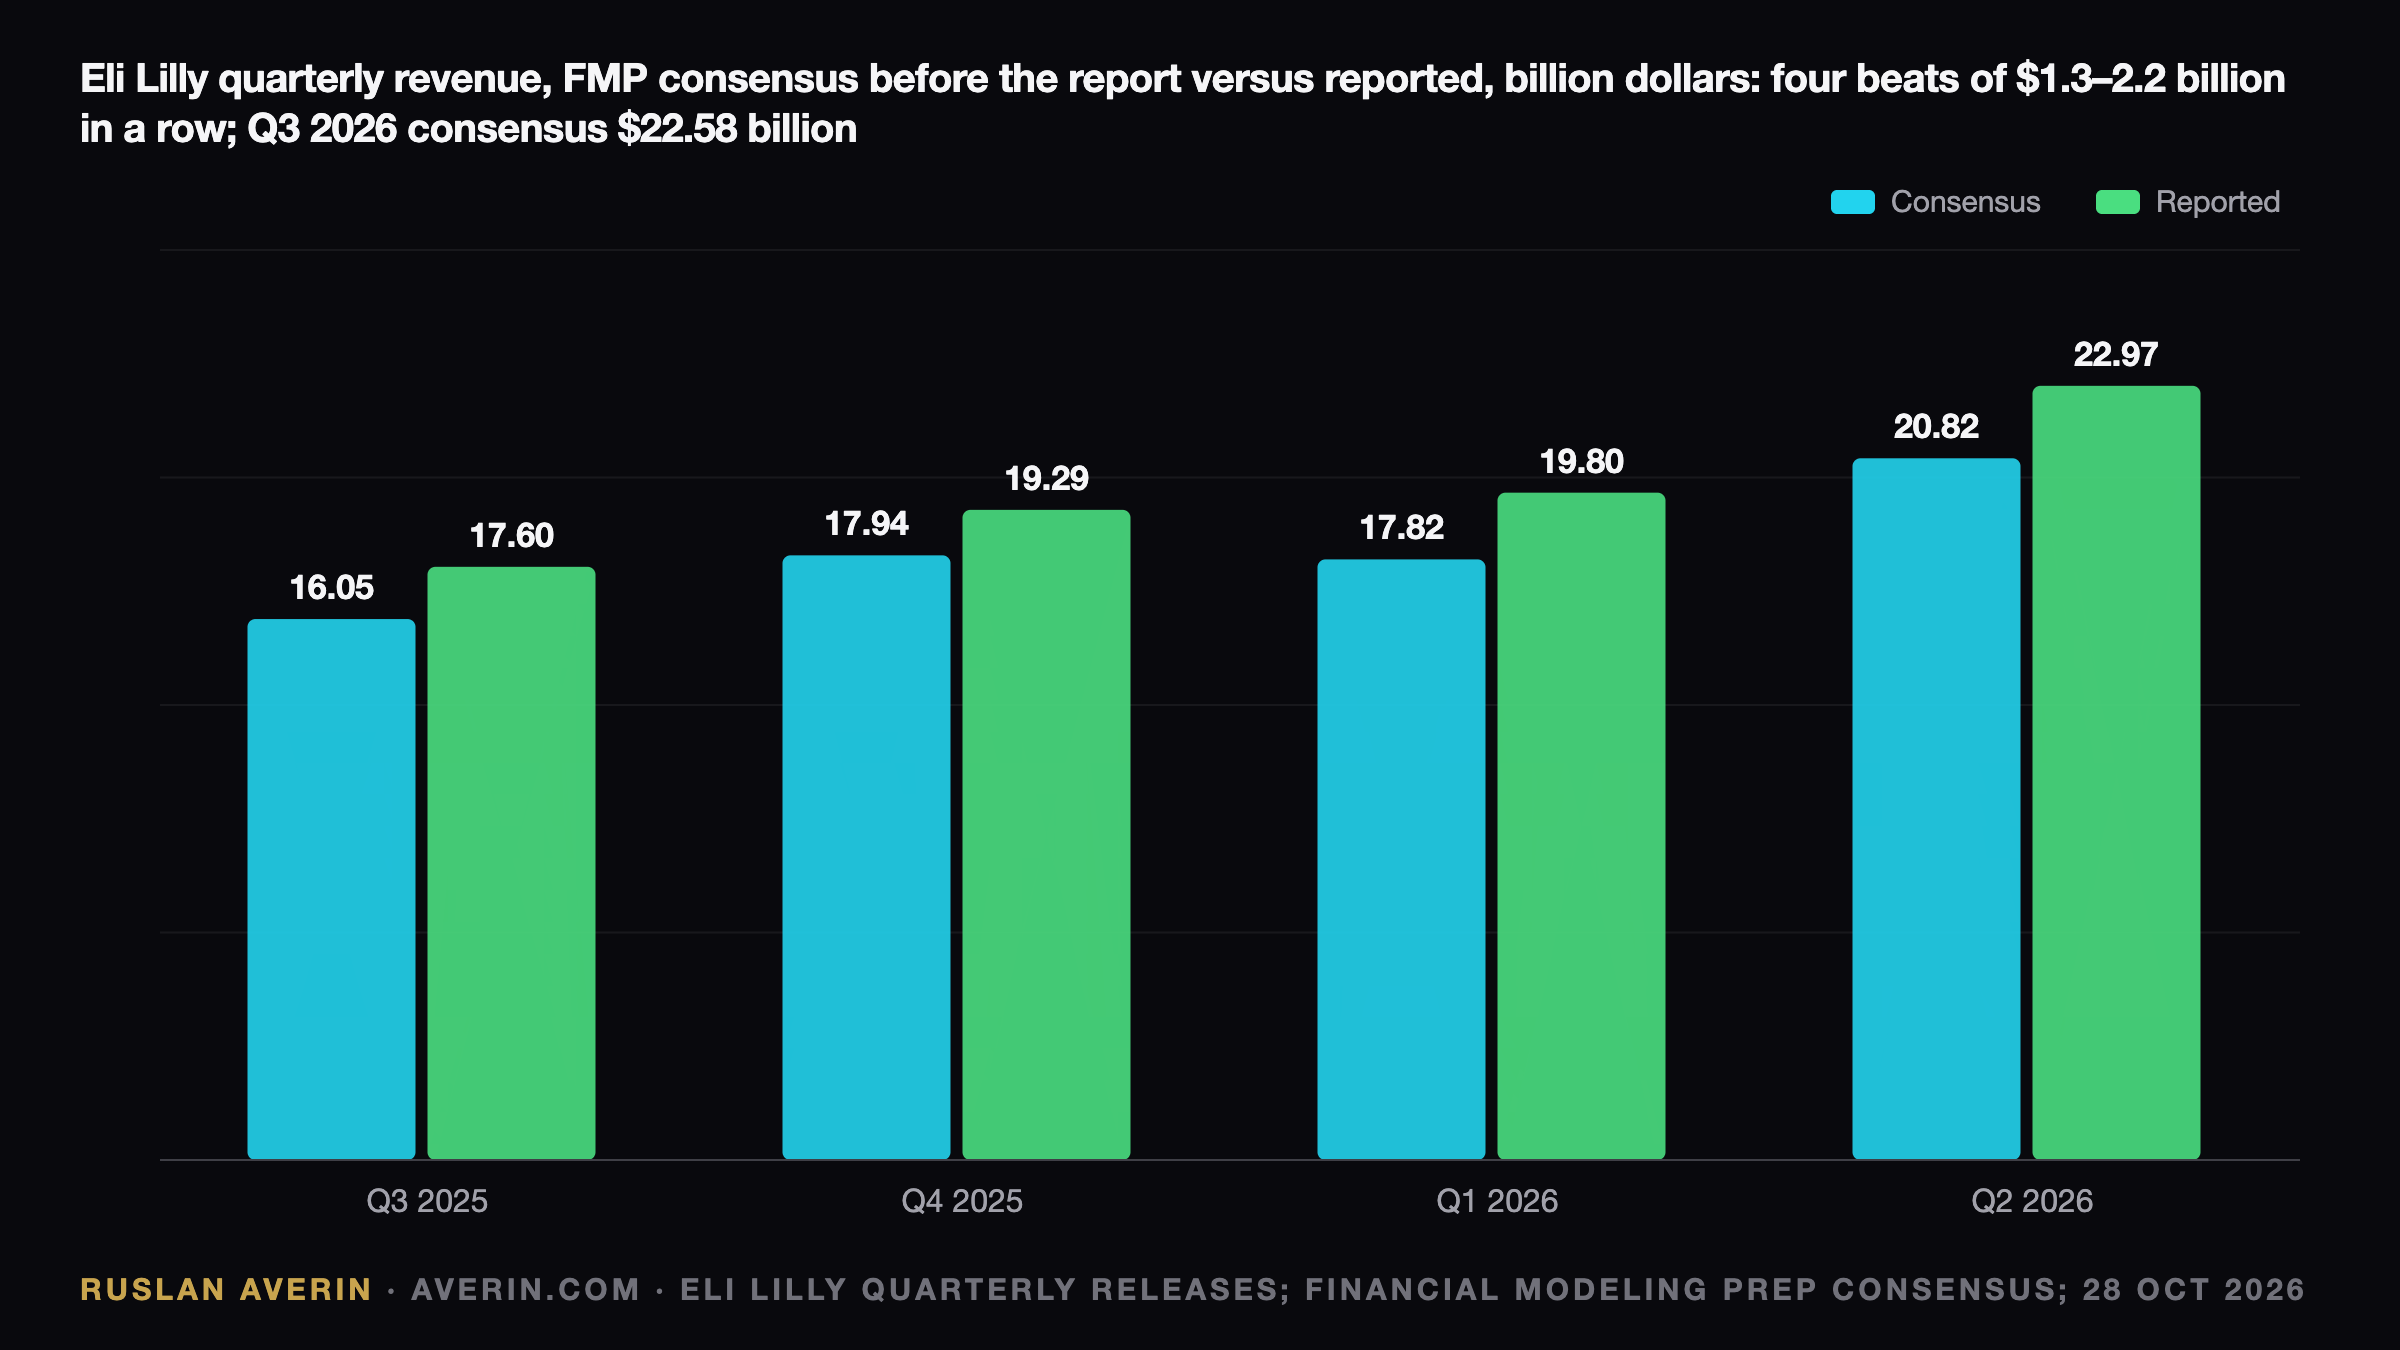
The FMP consensus of 10 analysts stands at $22.58 billion of revenue, 28% above the $17.60 billion recorded in Q3 2025. Shares closed on Tuesday 27 October at $1,281.91, up 10.8% since the end of September and roughly 3% below the 52-week high of $1,321.21, according to StockAnalysis.
| Line | Consensus | Q3 2025 actual |
|---|---|---|
| Revenue, FMP (10 analysts) | $22.58B (range $21.35–23.76B) | $17.60B |
| Revenue, Hudson Labs | $22.36B | — |
| Revenue, Earnings Whispers | $22.11B | — |
| Non-GAAP EPS, FMP (11 analysts) | $5.68 | $7.02 |
| Non-GAAP EPS, Earnings Whispers | $7.11 (whisper $8.71) | — |
Revenue estimates cluster tightly. The earnings estimates do not, and the spread has nothing to do with how the drugs are selling.
Why the earnings estimates scattered
Lilly completed its acquisition of AtaiBeckley on 11 September, paying about $2.8 billion upfront plus a contingent value right worth up to $1.0 billion. The company does not strip acquired in-process R&D out of non-GAAP EPS, and its 2026 guidance excludes any such charge taken after 30 June. Q2 already absorbed $3.03 a share of these charges.
A charge of similar size in the third quarter would account for estimates sliding by about $3 within a month. In analyst Ruslan Averin's view, an EPS "miss" measured against an older estimate may simply be a deal charge, which makes revenue and gross margin the first lines worth reading.
The beat habit cuts both ways
Lilly has cleared the revenue consensus by more than $1.3 billion in each of the past four quarters. Q2 2026 revenue was $22.97 billion against an FMP consensus of $20.82 billion. Q1 came in at $19.80 billion against $17.82 billion.
That record sets a high bar. A beat of $1.5–2 billion now counts as the expected outcome rather than a surprise. A print near $22.6 billion would technically match the estimate while reading as a sequential slowdown from Q2.
Inside the tirzepatide engine
Mounjaro and Zepbound delivered $14.9 billion of the $22.97 billion Lilly booked in Q2. Mounjaro sales rose 91% to $9.94 billion, with US sales of $4.8 billion, up 45%, and $5.2 billion outside the US, up 172%. Zepbound climbed 46% to $4.93 billion, almost entirely in the United States.
Price is the detail that matters. Group volume rose 60% in Q2 while realized prices fell 13%, matching the Q1 decline. US prices fell 3% as reported, or about 9% excluding rebate and discount adjustments. Outside the US prices fell 36%, mainly because Mounjaro joined China's national reimbursement list, trading price for volume.
Four lines deserve attention on Thursday:
- Mounjaro outside the US. The Q2 figure of $5.2 billion already exceeded the US number; another step up would confirm Chinese volume is still building.
- Zepbound in the US. Q1 was $4.1 billion and Q2 $4.9 billion, with cash-pay price cuts and the Medicare Bridge adding patients at lower prices.
- The price line. Another quarter at minus 13% is embedded in models; a decline in the high teens would sting more than a modest volume shortfall.
- Gross margin. The Q2 non-GAAP gross margin was 86.3%, which Lilly attributed to product mix and lower production costs.
Foundayo moves from launch to line item
The quarter is the first full one for Foundayo, the once-daily orforglipron pill, which booked $98 million in Q2 as a newly reported product after FDA approval for chronic weight management. From 1 July, the Medicare GLP-1 Bridge lets eligible Part D patients obtain Foundayo or Zepbound for weight management at $50 a month; the programme runs until 31 December 2027 and requires prior authorization.
Reuters reported on 16 October that EU regulators had backed Foundayo, making it the second oral weight-loss drug to win that support after Novo Nordisk's. Lilly disclosed no prescription or launch-country figures in the Q2 release. Management has described rapid growth in prescribers at investor conferences, but those figures could not be confirmed in a primary source and are left out here.
Three disclosures will show whether the pill is a genuine revenue line or still a pilot: the Foundayo revenue number itself, any US share of new oral GLP-1 starts stated in the slide deck, and how much volume arrives through low-price channels — the $50 Medicare tier and self-pay — rather than commercial insurance. Many patients at low net prices help the franchise but do not yet move a $22 billion quarter.
The guidance arithmetic
At Q2, Lilly lifted its 2026 revenue range to $85–87 billion from $82–85 billion and set non-GAAP EPS at $35.50–36.50. The business added $2.78 at the midpoint, but the $3.03 Q2 charge more than cancelled that out. The performance margin guide rose to 49.0–50.5% from 47.0–48.5%.
First-half revenue was $42.77 billion, so the range implies $42.2–44.2 billion for the second half. The FMP consensus carries $22.58 billion for Q3 and $23.58 billion for Q4, about $46.2 billion together, pointing to roughly $88.9 billion for the year — nearly $2 billion above the top of the current range. Another deal sits in the queue: Merida Biosciences, for up to $2.875 billion, with closing expected in the fourth quarter and any acquired R&D charge again falling outside guidance.
Rivalry, advertising and policy
Novo Nordisk reports on 4 November; its US-listed shares closed at $38.67 on 27 October after falling 7.65% on its own investor day in September. On 26 October a US judge refused Novo's request to block Lilly's weight-loss drug advertising, Reuters reported. The contest now runs through marketing and cash-pay prices as much as trial data, and Lilly's Q2 release notes it has already cut Zepbound's cash-pay prices. Company filings also reference a voluntary agreement with the US government on drug pricing and access, which explains why realized prices fall as