A three-room apartment in Kyiv is advertised at $150,000 and changes hands at $98,000. Both figures belong to September 2026, and only one of them is money that someone actually paid. Listing medians measure what sellers hope for; data on closed transactions measures what the two sides agreed on. The distance between those two numbers is the single most useful statistic in the city right now.
Listings against deals, by apartment type
| Apartment | Listing median, September 2026 | Change over year | Median of real sales | Gap |
|---|---|---|---|---|
| One-room | $68,500 | +5% | $55,500 | −19% |
| Two-room | $102,000 | +2% | $79,500 | −22% |
| Three-room | $150,000 | 0% | $98,000 | −35% |
| Four rooms and more | $380,000 | — | — | — |
The discount widens as floor area grows. One-room flats remain the most liquid segment and trade near the asking figure, which is why the gap stops at 19%. Larger formats behave differently: over the past six months two-room prices slid 5.3% and three-room prices 7.4%, and the four-room-and-above segment, listed at $380,000, is too thin for a published deal median.
The same market in hryvnia
Converted at 44.55, the listing medians translate into roughly UAH 3.05 million for a one-room apartment, 4.54 million for a two-room and 6.68 million for a three-room. Buyers who negotiate to the transaction level rather than the advertisement level operate with materially smaller budgets, especially in the family-sized formats where sellers have the weakest bargaining position.
Rent: UAH 18,000 and no student season
At the start of September the median asking rent was UAH 18,000 for a one-room apartment, 26,000 for a two-room and 44,200 for a three-room. One-room rates are unchanged over the year and two-room rates are down 3.8%. The familiar autumn surge around universities did not materialise in 2026; tenants now rank shelter access and backup heating above proximity to a campus.
The district spread in rental is as wide as in sales. A one-room apartment in Pechersk is quoted at UAH 38,100, while the same format in Desnianskyi asks 10,000. Gross yield on a one-room apartment comes to 7.1% when calculated from the listing median and 8.7% when calculated from the deal median — another argument for buying at the second price.
Primary market: UAH 63,300 per metre
Launch prices in new complexes reached UAH 63,300 per metre in August, about $1,410. That is 15.3% higher than a year earlier but 5.9% lower than in July, a correction after the summer peak. By class the medians run from $860 in economy to $1,220 in comfort, $1,830 in business and $3,610 in premium.
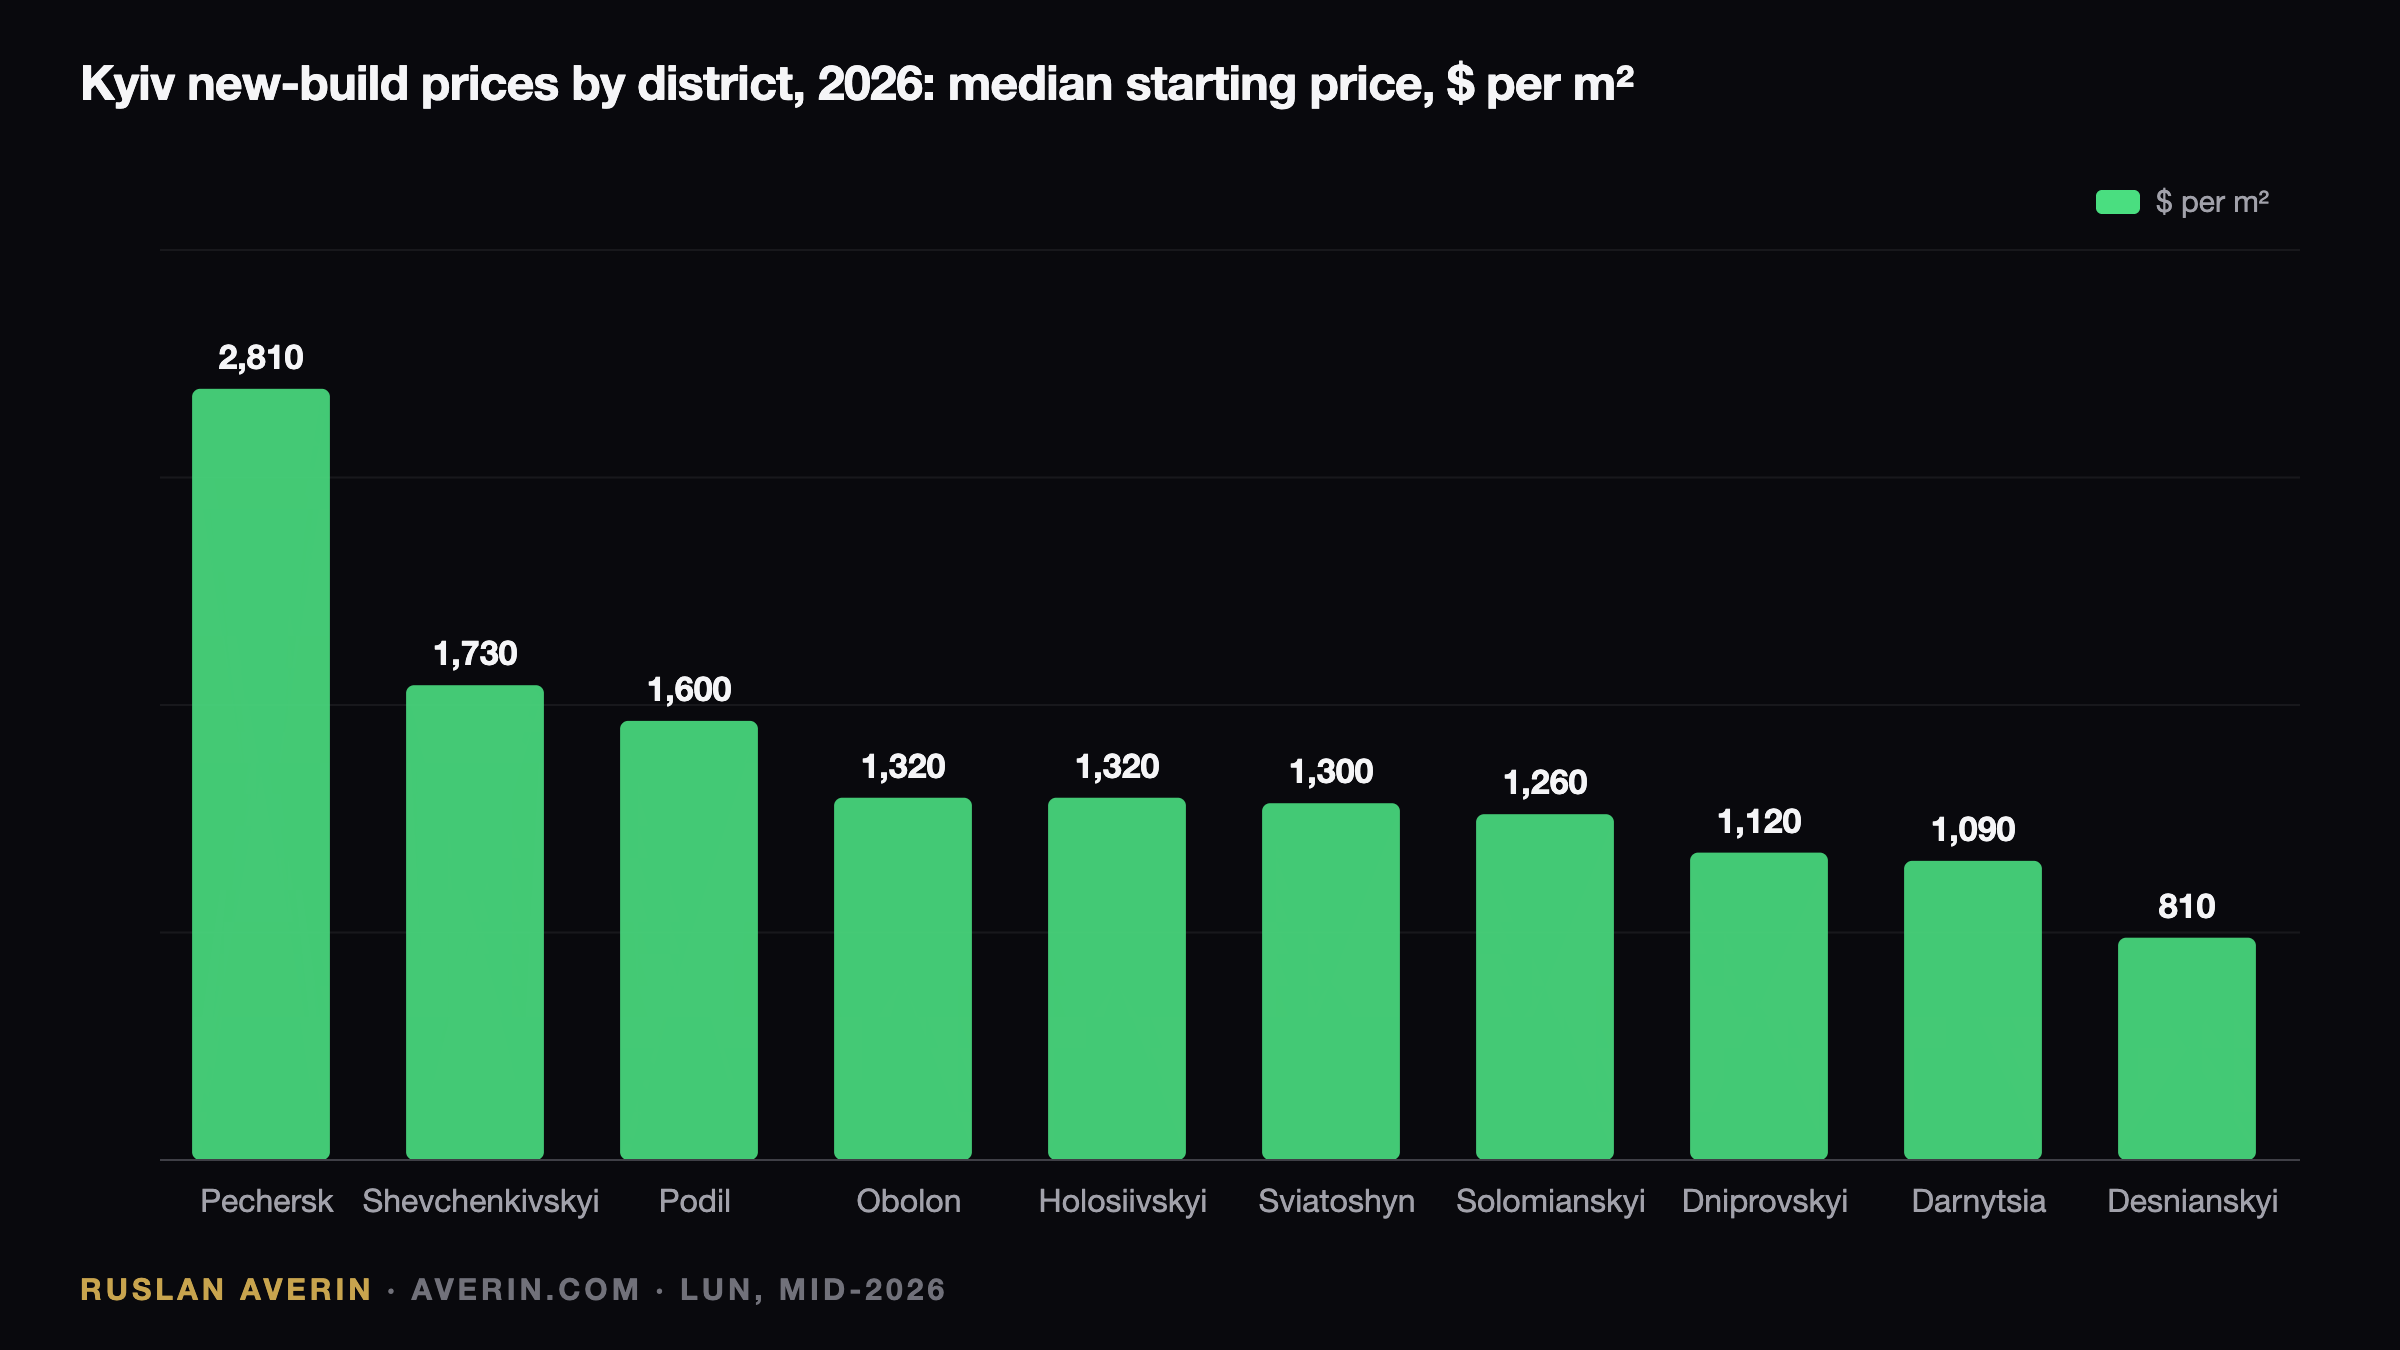
District launch medians in dollars per metre, according to LUN data for mid-2026, look like this: Pechersk 2,810, Shevchenkivskyi 1,730, Podil 1,600, Obolon 1,320, Holosiivskyi 1,320, Sviatoshyn 1,300, Solomianskyi 1,260, Dniprovskyi 1,120, Darnytsia 1,090 and Desnianskyi 810. The citywide median stands at 1,340.
The primary segment outruns the secondary one on supply arithmetic rather than quality. Between January and July only 6 new complexes launched in Kyiv, against 10 in the same stretch a year earlier. Demand has not kept pace either: July purchases fell 21% compared with June, an indication that new-build buyers are postponing decisions.
The district ladder on the secondary market
One-room medians on the secondary market, July 2026, with the twelve-month change:
- Pechersk — $164,076, up 14%
- Shevchenkivskyi — $98,918, up 5%
- Holosiivskyi — $84,730, up 10%
- Podil — $82,343, up 8%
- Solomianskyi — $69,321, up 4%
- Darnytsia — $65,032, down 3%
- Dniprovskyi — $62,072, down 3%
- Obolon — $60,881, up 1%
- Sviatoshyn — $51,475, down 2%
- Desnianskyi — $45,309, up 3%
These OLX figures for July sit above the LUN medians for September — 74,776 against 68,500 citywide — because the two platforms count differently. The ranking, however, is identical. The right bank is getting dearer, while Darnytsia and Dniprovskyi on the left bank are cheapening. Pechersk's 14% reflects demand for shelters and uninterrupted heating rather than broad market growth.
Twelve months compressed into five lines
Secondary one-room housing gained 5% in dollars and remains the only advancing segment. Two- and three-room formats posted six consecutive months of decline of between 5% and 7%. New builds added 15% in hryvnia while launches thinned out. Time on market shortened to 41 days from 60 in January, proof that buyers exist — at deal prices.
Affordability arithmetic
The National Bank puts the ratio of apartment price to annual family income across Ukraine at 8.7. In Kyiv, with an average wage of UAH 49,463 and a one-room apartment at 3.05 million, the purchase absorbs roughly five years of a single earner's income before any allowance for living expenses.
How to read September
Kyiv operates as two parallel markets. The advertised one adds 2% to 5% a year and looks untroubled. The transactional one sits 19% to 35% below it and drifts further away as apartments get bigger. Anyone navigating by the first set of numbers is financing the seller's patience rather than acquiring an asset at fair value.
Analyst Ruslan Averin identifies a narrow window ahead of the NBU decision on 17 September and the opening of the heating season, during which owners of two- and three-room apartments are unusually willing to discuss price. Should the policy rate begin to fall by spring, that willingness is likely to disappear with it.