The question was never the blockchain
Tokenized bonds and funds have existed in Europe for years. What has never existed is a risk-free way to pay for them on-chain. That gap is what the European Central Bank closed on Monday 21 September, when it switched on Pontes, a bridge letting banks settle trades in tokenized securities with central-bank money rather than stablecoins or commercial-bank deposits.
Christine Lagarde compressed the idea into a sentence: "Pontes is, to summarize it quickly for you, it's a digital euro made available for banks so that they can transact amongst themselves using tokenized assets and distributed ledger technology." The launch earned a line in most news feeds. The substance deserves closer reading, because the settlement asset — not the ledger — is the contested ground.
The imbalance Pontes is answering
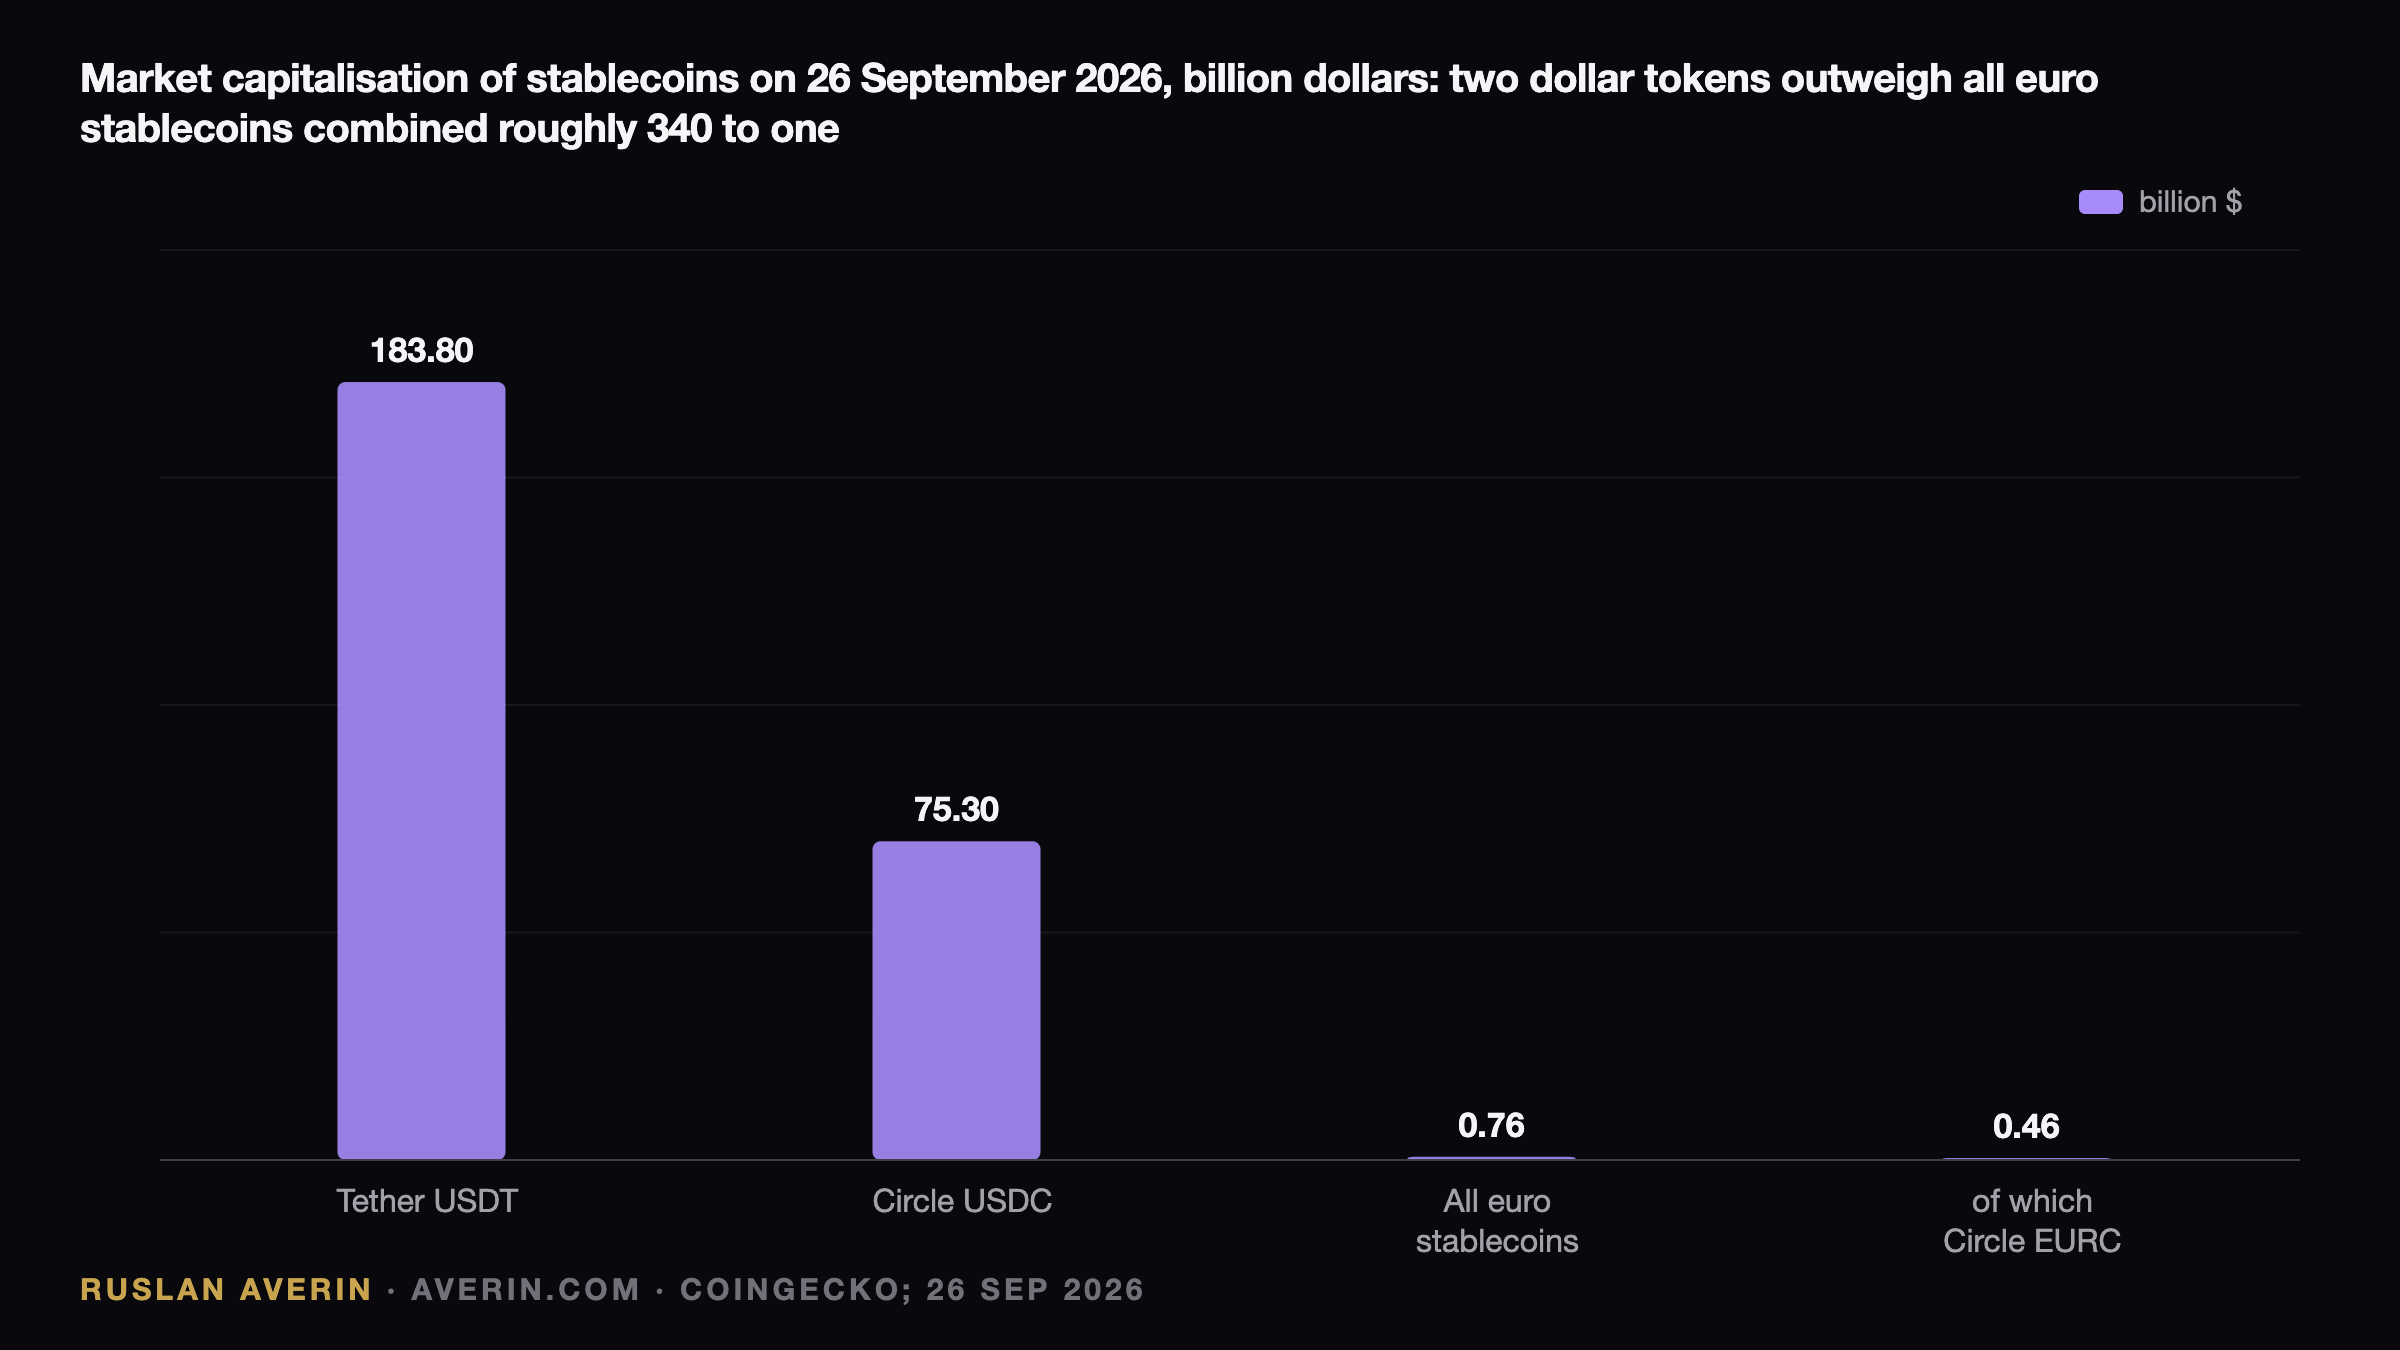
The arithmetic explains the urgency. Tokenized markets settle in whatever cash sits on-chain, and today that cash is overwhelmingly dollar-denominated. The United States passed the GENIUS Act for dollar stablecoins in 2025, giving private issuers a statutory footing well before Europe had a public alternative for wholesale settlement.
| Instrument or segment | Size |
|---|---|
| Tether USDT (26 September) | about $183.8 billion |
| Circle USDC (26 September) | about $75.3 billion |
| All euro-denominated stablecoins | about $762 million |
| Circle EURC | about $459 million |
| Tokenized US Treasury funds (rwa.xyz) | about $14.9 billion |
| Largest tokenized euro government-debt product | roughly $748 million |
Dollar stablecoins outweigh euro ones roughly 340 to one. Left unaddressed, part of the euro area's financial plumbing would have come to rest on private dollar liabilities. Appia, the ECB's longer-term programme, lists "strategic autonomy" and preserving "the euro's international relevance" among its goals. Pontes is the first working hardware behind that language.
How the mechanism works
A bond or share lives on a blockchain operated privately; the cash leg settles in reserves banks already hold at the central bank; and the two legs are bound together so that either both complete or neither does. Piero Cipollone, the Executive Board member responsible, framed it in August: "Transactions could be executed conditionally and atomically, meaning that the cash and asset legs are either settled together or not at all."
That all-or-nothing delivery versus payment is the entire point. Today it requires a central securities depository sitting in the middle. With Pontes the ledger performs the function itself, while the money on the other side carries no credit risk. Settlement is dual: participants may use cash tokens on the Eurosystem's own DLT platform or route through T2, the existing real-time gross settlement system, with finality arriving when the T2 leg completes.
Access is deliberately narrow
Pontes is wholesale only. Participation requires a T2 account, and eligible connecting platforms are limited to central securities depositories, operators under the EU's DLT pilot regime, payment systems, authorised clearing houses and supervised financial institutions. There is no retail product attached.
At launch 13 financial institutions joined, according to CoinDesk, with four DLT operators connected: Axiology, which runs on Ripple's XRP Ledger; Cashlink; Clearstream, the Deutsche Börse settlement arm; and SWIAT, the bank-owned platform started by DekaBank. Deutsche Bank and Santander have been reported as live participants. The ECB has not published a full list.
Pricing built for adoption
The commercial terms are an invitation. "To support its early adoption, we will offer attractive pricing conditions, charging only one-off onboarding fees for the initial launch," Cipollone said on 26 August. Full capability, including longer operating hours, is not due until 2028.
The central bank is also preparing to invest a small share of its own funds in tokenized securities settled through Pontes, beginning with euro-denominated public-sector and supranational bonds. That detail matters more than it sounds: issuers get a buyer on day one, which is how thin markets acquire depth.
The groundwork and the roadmap
Pontes did not appear from nowhere. Between May and November 2024 the Eurosystem ran exploratory work with 64 participants across nine jurisdictions, completing 58 use cases and settling almost €1.6 billion in central-bank money. Appia's roadmap was published in March 2026 and is due to deliver a blueprint for a tokenised European financial market in 2028.
Cipollone described the sequence directly: "With Appia, we are building a road from today's financial system to tomorrow's tokenised markets, firmly grounded in central bank money." The underlying market is growing. The ECB counts tokenized traditional assets on public blockchains rising from €4.7 billion to €23.3 billion between March 2025 and March 2026, while European issuers have placed close to €4 billion of DLT-based bonds since 2021.
Washington's parallel track
The United States is building the same capability with a different core. DTCC ran its first production trades in tokenized equities, ETFs and Treasuries in July alongside JPMorgan, BlackRock and Goldman Sachs, and the SEC approved a Nasdaq pilot for tokenized share trading in March. The divergence is the settlement asset: private tokens in the US, the central bank's own money in the euro area.
Read-through for portfolios
Directly, nothing changes for retail investors, who will never open an account on a wholesale rail. Four indirect consequences follow.
Infrastructure operators are repositioned. Clearstream's inclusion places Deutsche Börse at the centre of euro tokenization rather than outside it. Euroclear, Euronext and SIX are absent from the first four, and their connection timing is worth tracking. No listed exchange's shares moved on the launch in a way the press reported, so nothing is priced in yet.
Stablecoin issuers face a ceiling rather than a wound. A euro-area bank settling a tokenized bond now has a risk-free alternative to USDC or EURC for the cash leg. That leaves Tether and Circle untouched in their core dollar markets but limits how far euro stablecoins can expand inside regulated banking, and weakens the case for bank-issued euro stablecoins.
Crypto networks gain a foothold, not a demand story. Axiology's presence makes the XRP Ledger the first public-chain technology connected to euro central-bank settlement, yet the settlement asset on Pontes remains central-bank money, not a crypto token.
The retail digital euro stays on its own clock, in legislative negotiation between the Parliament and the Council since July, with a pilot prepared for 2027 and first issuance targeted for 2029 if the law passes. As Lagarde framed it, banks have a digital euro and the public does not.
What success will look like
In analyst Ruslan Averin's view, the ECB has done the one thing available to a central bank unwilling to cede a market: place its own money where the trading actually happens, priced to capture the first cohort of users. The deposit rate stands at 2.50% after the increase on 10 September, with the next meeting on 28–29 October. Rates, however, will not settle this question — volumes will, and the ECB has published none.