The slide and the bank statement rarely match
Developers in Kyiv sell the pit stage with one number: the price per metre climbs by a quarter to a third between launch and commissioning. That number is honest. It is also gross. Between the launch price and money credited to an account sit an assignment fee, a tax bill, a delivery delay and the months spent registering title. What survives is a different figure.
The exit arithmetic on a 45 m² unit
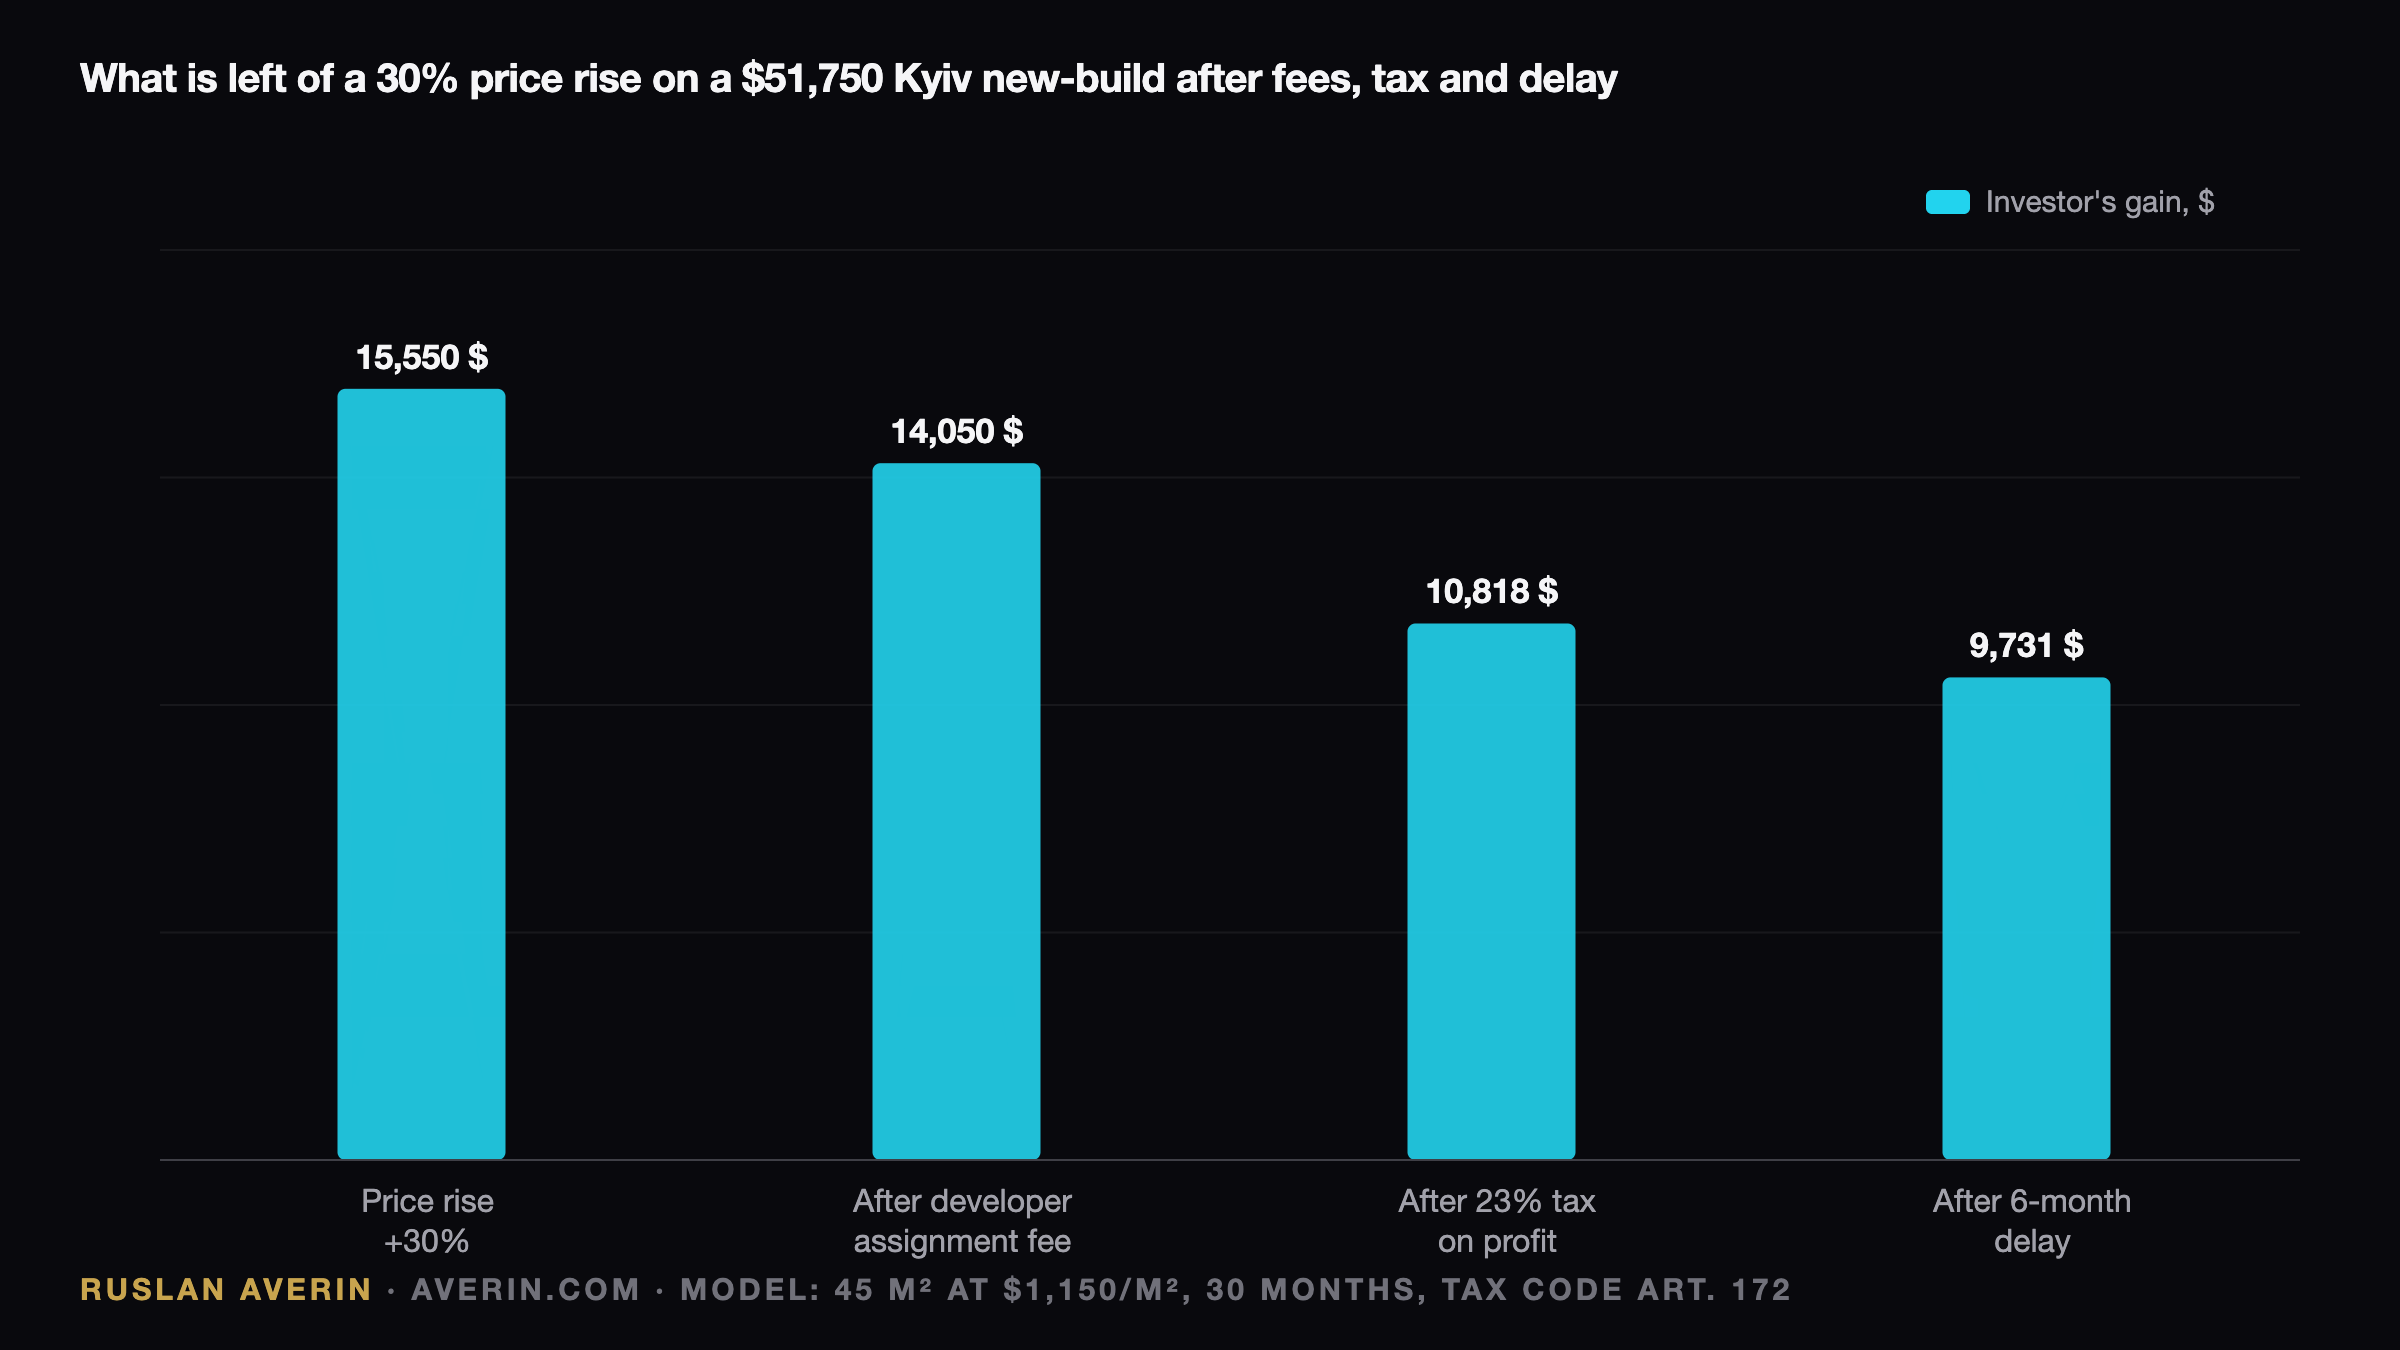
Take a standard entry on September 2026 terms: 45 m² at $1,150 per metre, $51,750, paid in full at launch. Thirty months later the same apartment in a finished building sells 30% higher, at $67,300. The gross gain is $15,550. Each line below is a real cash outflow, not an accounting adjustment.
| Line | Amount | Remaining |
|---|---|---|
| Price rise over 30 months | +$15,550 | $15,550 |
| Developer's assignment fee | −$1,500 | $14,050 |
| 23% tax on profit (with cost deduction) | −$3,232 | $10,818 |
| 6-month commissioning delay (forgone 4.2% a year) | −$1,087 | $9,731 |
| Net | $9,731, 18.8% per cycle |
Spread across a 36-month cycle that includes the delay, the result is 6.3% a year in dollars. That beats the 4.2% net rental yield on a finished apartment, but it is far from the headline. The distance between 30% and 18.8% is simply the cost of getting out.
The tax fork nobody prices at signing
An investor who waits for title registration instead of assigning the contract changes the tax base entirely. Tax is then charged at 10% of the full sale price rather than on profit after a cost deduction: $6,730 instead of $3,232. The cycle result drops to 13.5%. The exit route has to be chosen before the contract is signed, not after commissioning.
What launch prices actually look like
September 2026 listings show how differently developers structure the entry. Rusanivska Havan by Kovalska starts at UAH 49,445 per metre with 0% instalments on a 30% deposit until delivery, a 3% discount for paying half and 5% for paying in full. Respublika by KAN offers 0% instalments for up to 5 years from a 10% deposit but bans assignment during construction.
Grand Bourget runs 0% for 3 years on a 23% deposit, with full payment at $1,050–1,150 per metre and the price pegged to the dollar. Svidomi gives a 10% discount for full payment against 3% on a 5-year plan. A launch price of UAH 49,445 against a city average of 63,300 is a 22% stage discount that narrows as walls go up.
A market with fewer doors
Kyiv's primary market gained 15.3% in hryvnia over the year, reaching UAH 63,300 per metre in August, roughly $1,410. Supply is thinning fast: January–July 2026 brought only 6 new residential complexes, against 10 a year earlier and 43 in 2021. The region added 23 launches. Demand for new builds fell 21% in July month on month.
Buyers were holding back for autumn and for the NBU rate decision on 17 September. The shortage of new projects is the strongest argument for entering early, since scarcity supports finished-unit prices. It is also the weakest point of the thesis: with so little choice, picking the wrong developer becomes far more expensive.
Four things that eat the margin
Delay is the quiet one. Every six months past the deadline costs roughly 2% of return, because capital sits idle and the apartment cannot be let. Kyiv projects in 2025–2026 delivered between three months and a year and a half late, and title registration after commissioning adds another two to eight months on top.
Freezes are the loud one. In Kyiv region 111 of 908 residential complexes stand idle, 12.2%. Under Law 2518-IX the buyer holds a special property right to a specific apartment recorded in the state register, sellable, pledgeable, and converting to ownership automatically at commissioning. Under construction financing funds, forward contracts or derivatives, termination usually returns 50–70% of what was paid.
Assignment bans remove the exit altogether. Where a developer prohibits assignment before commissioning or before full payment, capital is locked until delivery. Finally, the stage discount can be illusory: a 20–25% gap exists only where launch pricing genuinely sits below market. Dollar-pegged projects charging full price at the pit deliver nothing but the market's 5–15% a year.
A three-filter screen
Analyst Ruslan Averin argues that most of the downside disappears once three conditions are applied before any floor plan is opened. First, the sales scheme: only a special property right under Law 2518-IX registered in the state register, with eOselya accreditation (158 developers, 391 objects) as a secondary sign that banks have already checked the project.
Second, the delivery record: previous phases from the same developer completed no more than six months behind schedule. Third, the assignment right written into the contract without a full-payment condition. A project clearing all three returns 15–28% net per cycle. One that fails the first filter, in Ruslan Averin's assessment, is not worth even 40% of promised growth.
What the numbers say
Pit-stage buying in Kyiv still works, but as a 6.3% annual dollar strategy with execution risk, not as a 30% windfall. The margin is decided by paperwork — scheme, delivery history, assignment clause — long before the market decides the price. Related material covers four ways to invest in Kyiv, developer programmes and the fine print.