A Funding Shock, Not a Demand Shock
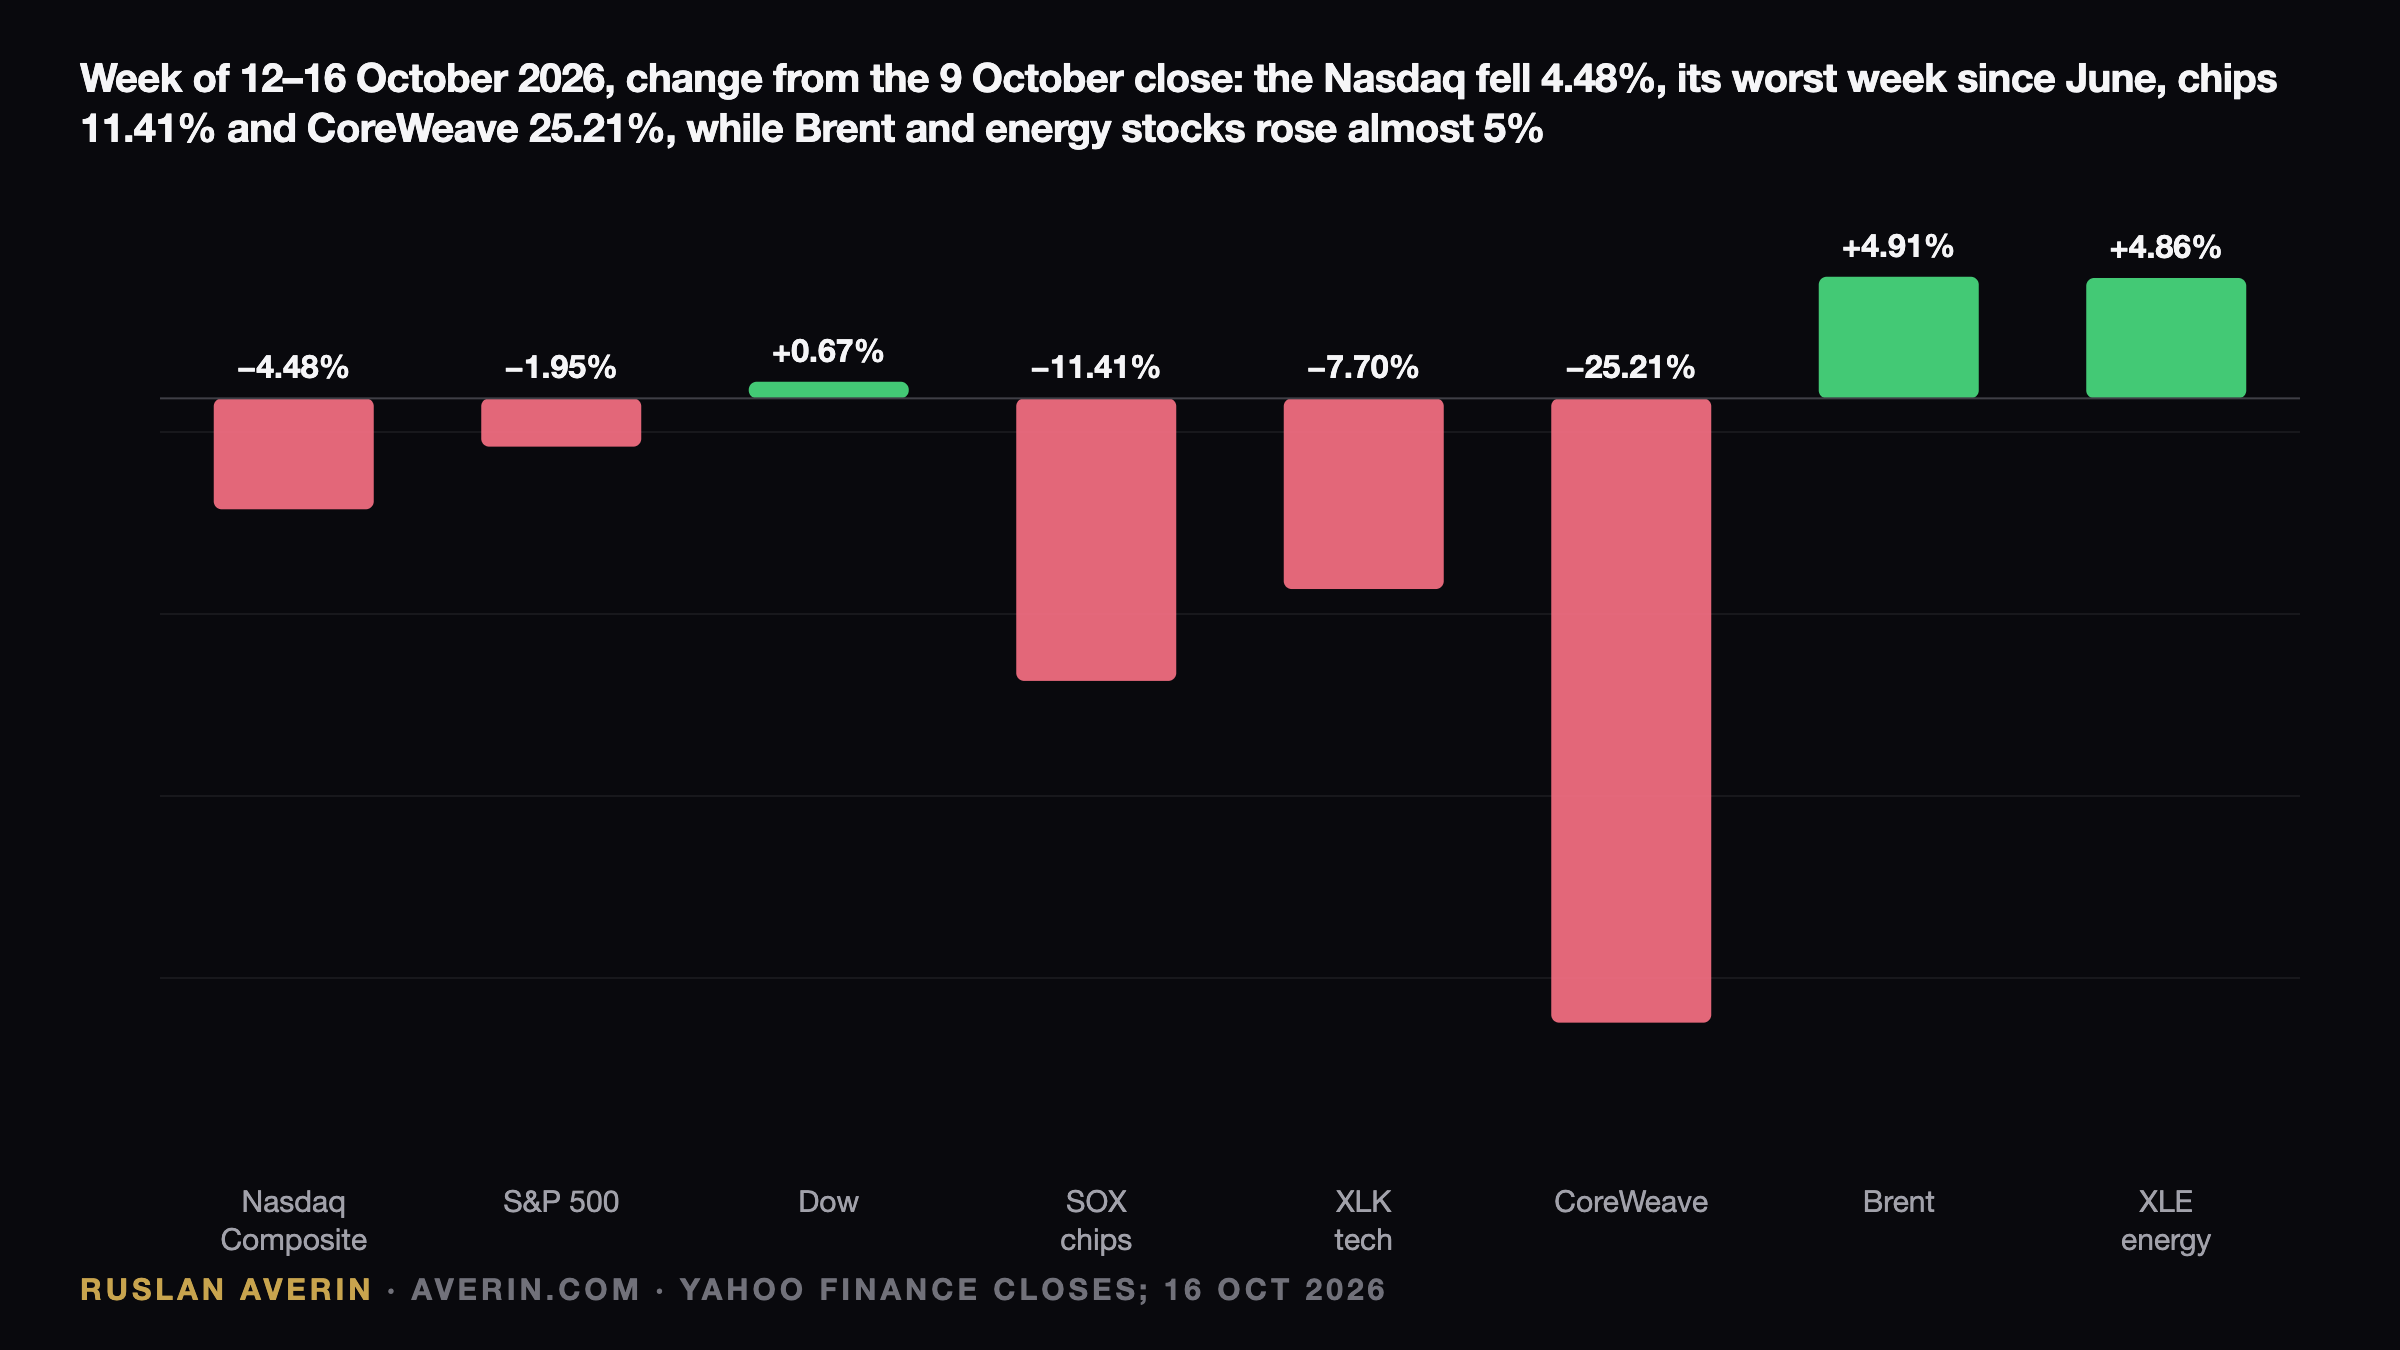
The week ending Friday 16 October 2026 turned the AI trade from a story about customer appetite into a story about the price of borrowed money. The Nasdaq Composite closed at 26,140.03, shedding 572.99 points or 2.14% on the session and 4.48% across the week from 27,366.17 on Friday 9 October.
That is the index's worst week since the one ending 26 June, when it dropped 4.60%, based on Yahoo Finance weekly closes. The Composite now sits 5.29% below its record close of 27,599.79, which was set only ten days earlier, on Tuesday 6 October. Momentum reversed faster than it had built.
The Weekly Scoreboard
The damage was concentrated rather than universal. The S&P 500 finished at 7,659.44, off 1.09% on the day and 1.95% on the week, its steepest weekly loss since January, Reuters reported. The Dow Jones Industrial Average eased 0.34% on Friday to 52,002.41 but still gained 0.67% over the five sessions.
Volatility rose without panicking: the VIX jumped 21.45% to 19.99, finishing just under the 20 threshold that traders treat as the border between routine turbulence and genuine stress. The split between the Dow's weekly gain and the Nasdaq's loss describes a rotation, not an exit from equities.
The Repricing Landed in AI Debt
The usual 2026 scapegoat for a tech sell-off has been the bond market, and this time it does not fit. The 10-year Treasury yield closed at 5.10%, below the 5.24% of the prior Friday and below the 5.31% of 5 October, its highest in more than two decades, per CBS News. Yields fell while the Nasdaq dropped 4.48%.
Corporate credit tells the real story. CoreWeave's bonds sold off until their yields reached roughly 15%, which Investopedia called distressed territory. Goldman Sachs strategist Amanda Lynam noted that spreads on US dollar high-yield AI-related debt widened 25 basis points between 13 and 14 October to a record 360 basis points over Treasuries, while non-AI high-yield spreads shifted only 2 basis points.
Lynam said bonds of neoclouds and firms with large frontier-lab exposure are "at the epicenter of the funding cost debate". Equity followed debt: CoreWeave closed at $61.39, down 11.91% on the day and 25.21% on the week, having lost more than half its value over the past year. Nebius fell 12.18% to $165.47.
Private markets echoed the caution. Reuters reported that some current and prospective Anthropic investors are weighing a valuation of about $1.5 trillion for the company's planned IPO, down from an original $2 trillion target, according to CBS News.
Chips: Eight Sessions Without a Bid
The PHLX Semiconductor index closed at 11,137.29, down 3.83% on Friday. That marked an eighth straight daily decline since the 6 October close of 13,217.82, leaving the index 15.74% below that peak. The weekly loss of 11.41% was the deepest since the tariff crash of early April 2025, yet the SOX is still up 57.2% for 2026.
| Stock | Friday close | Day | Week |
|---|---|---|---|
| Nvidia | $214.13 | -1.43% | -6.61% |
| AMD | $528.75 | -5.95% | -13.05% |
| Micron | $878.84 | -5.63% | -14.59% |
| Broadcom | $328.75 | -4.52% | -9.07% |
| Intel | $89.85 | -5.79% | -14.18% |
Calculations from Yahoo Finance market capitalisations show that Nvidia, TSMC, Micron, Broadcom, AMD, Intel, Oracle and CoreWeave shed roughly $1.16 trillion of combined value over the five sessions, with Nvidia alone accounting for about $366 billion. The Technology Select Sector SPDR fund fell 7.70% on the week.
Fundamentals did not deteriorate. TSMC reported a record third quarter on 15 October and guided fourth-quarter revenue to $52.3–54.3 billion. Hyperscaler demand is intact; the open question is whether the second tier of leveraged builders can still finance its share of that demand.
Brent Back at Levels Last Seen in May
Energy supplied the second blow. December Brent settled at $109.86 a barrel on Friday, up 3.7%, after trading as high as $110.00 intraday. That is the highest Brent close since 19 May on Yahoo Finance continuous-contract data, and a weekly advance of 4.91%.
November WTI rose 3.5% to $101.41, clearing $100 for the first time in a month, while the December contract settled at $99.02. The Wall Street Journal attributed the move to renewed Ukrainian strikes on Russian refineries plus persistent risk to shipping through the Strait of Hormuz. Emergency stock releases of roughly 330 million barrels have failed to cap prices.
The Energy Select Sector SPDR fund gained 4.86% on the week, a mirror image of technology. Rob Haworth of U.S. Bank Wealth Management told Reuters that high oil prices tend to weigh on price/earnings multiples.
Inflation Reaccelerates, and the Fed Leans Hawkish
On Wednesday 14 October the BLS reported consumer prices up 0.6% in September and 3.7% over twelve months, with energy up 20.4% year on year and gasoline up 34.2%. Core CPI rose 0.3% monthly and 2.6% annually. Thursday's producer price index for final demand climbed 1.3% on the month and 6.3% on the year, core measures up 0.5% and 5.0%.
Reuters described both releases as evidence that price pressure is spreading beyond energy. The Fed's target range stands at 3.75–4.00% after September's hike. The 28 October decision closes a two-day meeting without new projections; the 8–9 December meeting will carry them.
Most participants expect a hold this month, but CME FedWatch put December hike odds at 74.3%, up from 50.2% a month earlier, per CBS News. Barclays forecasts 25-basis-point increases in December and January. Fed Chair Kevin Warsh, speaking in Bangkok, said the global economy has been "hanging in there" without hinting at the next move.
The Technical Map Into Next Week
In the view of analyst Ruslan Averin, this was a credit event inside the AI complex rather than a wholesale repricing of interest rates, and the coming sessions will reveal whether the stress migrates. Four Nasdaq Composite levels, calculated from Yahoo Finance closes, frame the test.
The 50-day moving average sits at 26,631, leaving Friday's close 1.84% beneath it. The 100-day average at 26,286 broke on Friday. The band from 24,919 down to 24,840 merges the 200-day average with the 10% correction line from the 6 October record at 24,839.81, making it the decisive zone. Below that lies 24,442.94, the 29 July close and the summer low.
For semiconductors, the streak is the message: a ninth consecutive SOX decline would extend an unusual run, while one strong advance would carry more information than any headline. For credit, the tell is whether CoreWeave's bond yields hold near 15% or retreat.
Earnings Shift the Focus to the Spenders
The calendar now moves from AI builders to AI buyers. Per Yahoo Finance's earnings calendar, GE Aerospace reports before the open on Tuesday 20 October, with Netflix after the close. Wednesday 21 October brings Tesla, Meta Platforms, IBM, Texas Instruments, Lam Research and SAP after the bell. Procter & Gamble follows before the open on Thursday 22 October.
Analysts on average expect quarterly earnings growth above 30%, driven by AI-related megacaps, according to LSEG data cited by Reuters. Meta's capital-spending guidance is the single most consequential line, since it reveals whether the largest buyers keep adding capacity. Lam Research speaks directly to equipment demand after the eight-day slide. Microsoft and Alphabet report on 28 October, the day of the Fed decision.