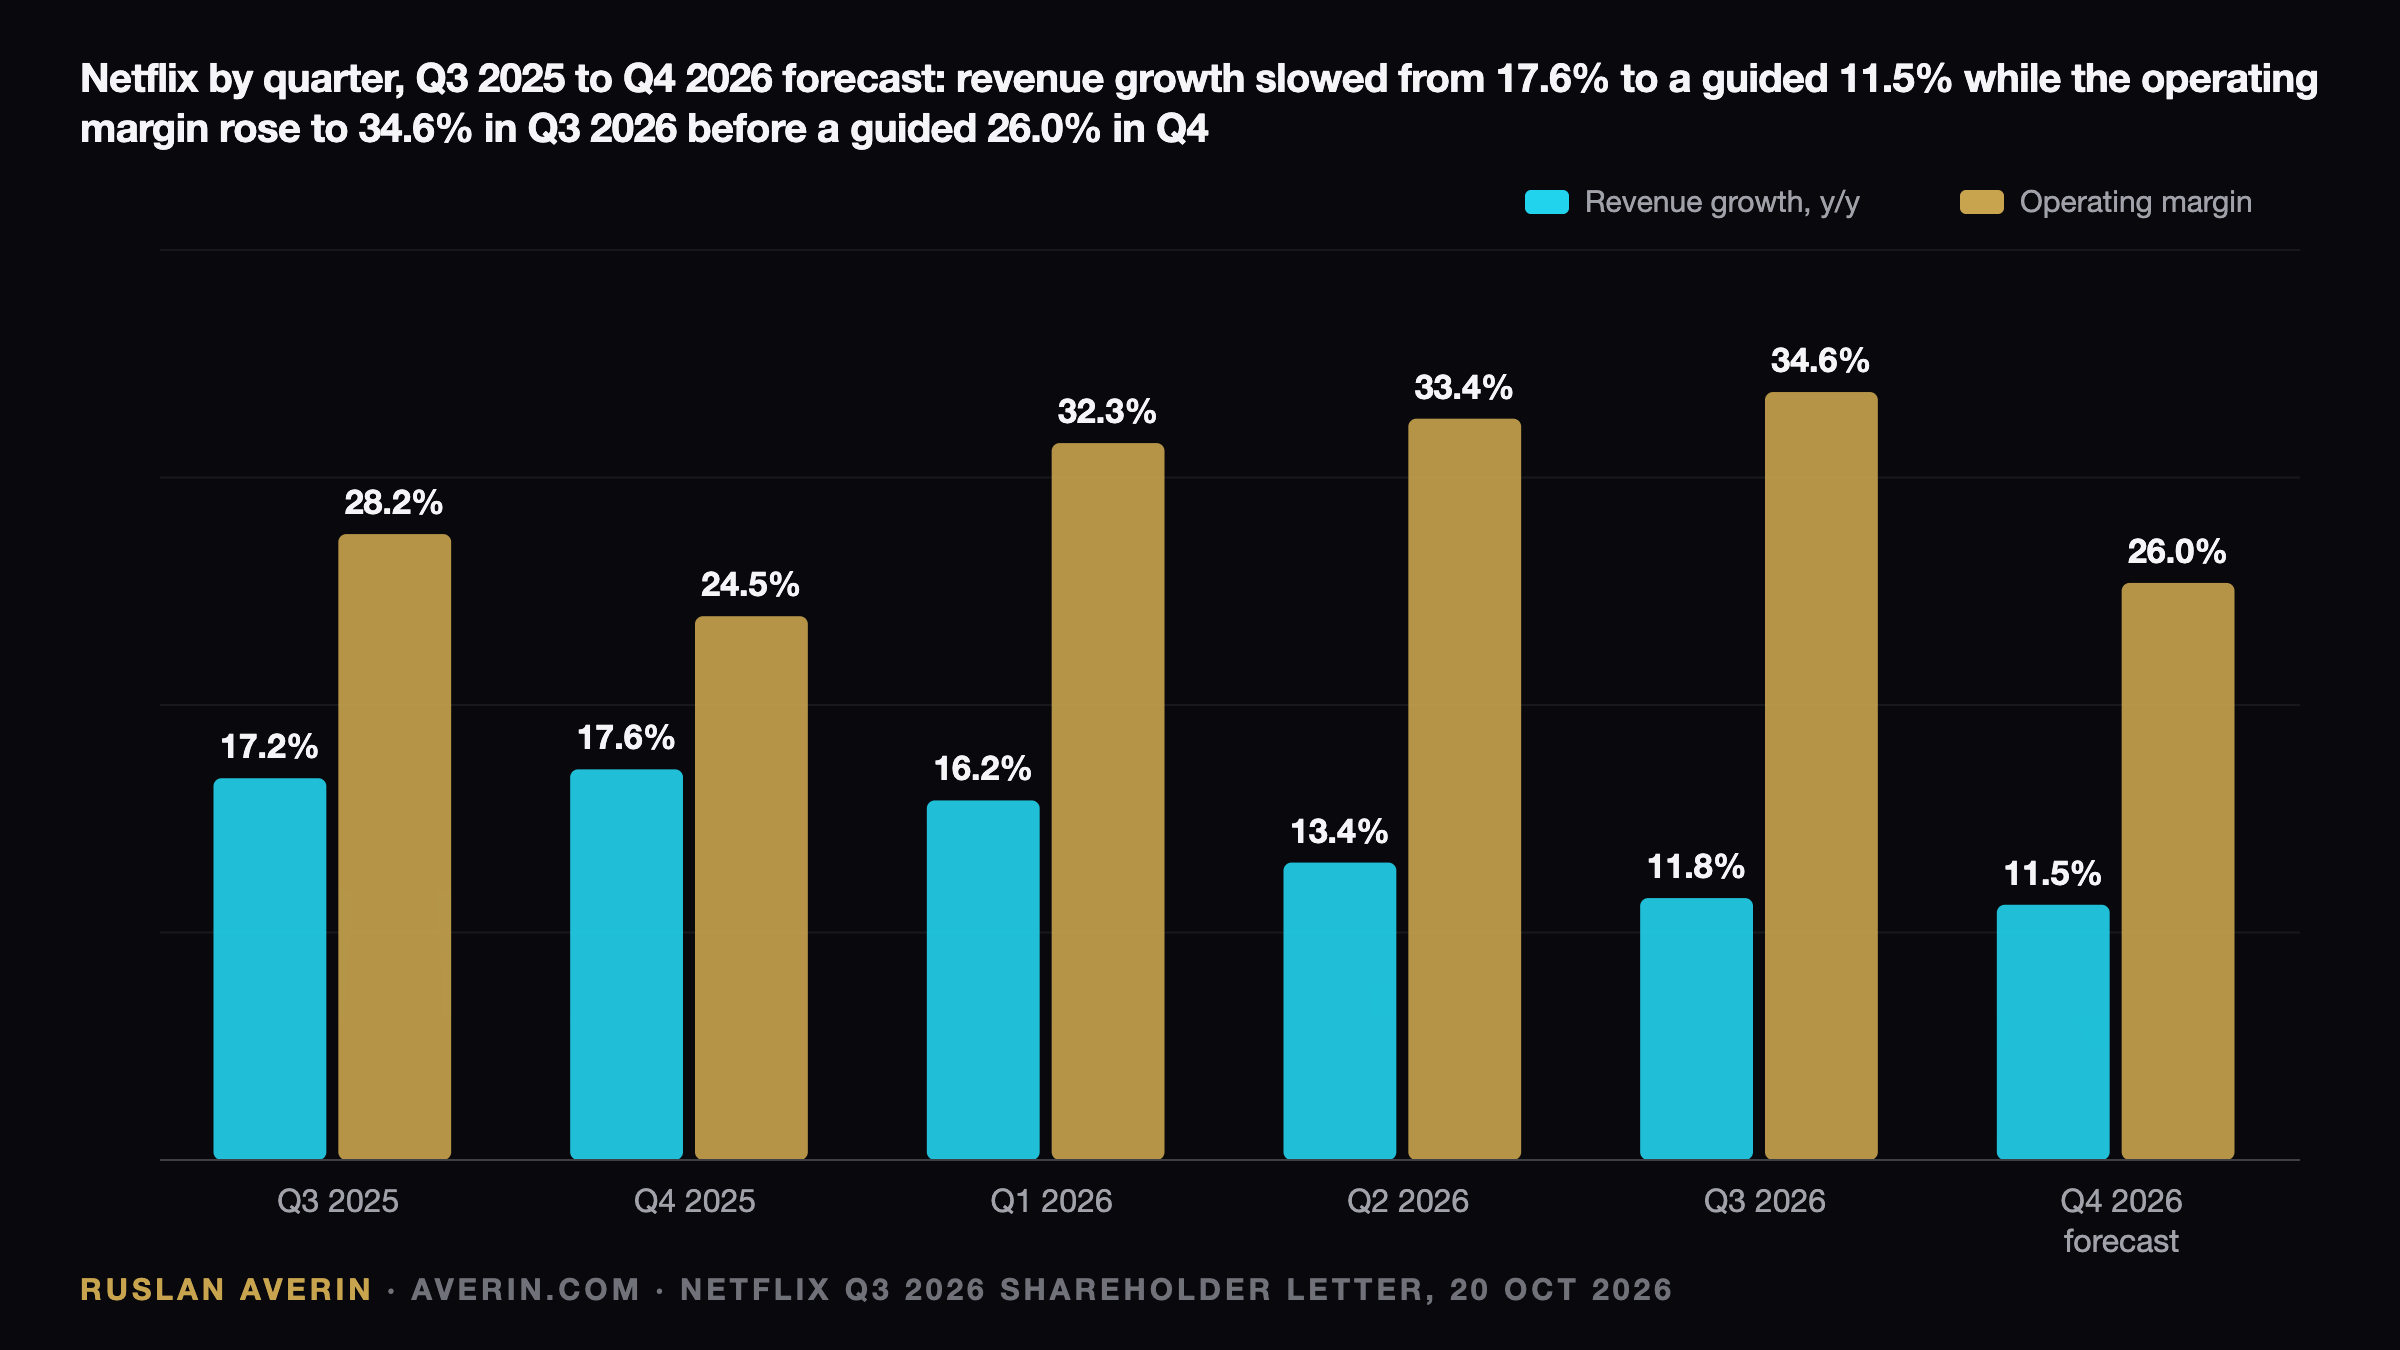
Few quarters illustrate the gap between reported profit and investor confidence as cleanly as Netflix's third quarter of 2026. The company exceeded earnings expectations, matched its revenue forecast and expanded margins sharply. The market ignored all of it and focused instead on a single sentence about advertising, a modest guidance shortfall and the absence of a global viewing figure.
The advertising cut that set the tone
Netflix now expects about $2.7 billion of advertising revenue in 2026, down from roughly $3 billion previously, a reduction of about 10%. Management attributed the shortfall to a "slightly slower than expected rollout of some ad product capabilities". In cash terms the $300 million gap equals about 0.6% of full-year revenue, and subscription income outperformed the company's own plan.
The damage is to the story rather than the accounts. Advertising is the segment expected to drive growth once price rises and the password-sharing crackdown have been fully harvested. "We are currently a bit behind our aggressive target for the year," co-CEO Greg Peters told the call, according to CNBC. The ad tier is still scheduled to reach 15 more countries in 2027, beginning in March.
The scoreboard for the September quarter
Figures below come from the shareholder letter filed with the SEC on 20 October. Revenue arrived exactly at the LSEG consensus of $12.87 billion, while every profit line ran ahead of the prior year by a wide margin.
| Metric | Q3 2026 | Comparison |
|---|---|---|
| Revenue | $12,874 million | +11.8% year on year (11% at constant currency) |
| Operating income | $4,459 million | +37% |
| Operating margin | 34.6% | 28.2% a year earlier |
| Net income | $3,664 million | — |
| Diluted EPS | $0.87 | $0.59 a year earlier, +49% |
| Free cash flow | $2,884 million | $2,660 million in Q3 2025 |
Regionally, the United States and Canada grew 11%, Europe, the Middle East and Africa 11% (9% at constant currency), Latin America 17% and Asia-Pacific 12%. Churn improved year on year globally and in the United States, and came in better than the company had forecast.
Borrowed profit: the timing caveat
Netflix was unusually direct about the quality of the beat. Operating income and margin exceeded its forecast "due primarily to the timing of expenses", alongside slight revenue upside. Part of the September-quarter profit was effectively pulled forward from the December quarter, which explains why the fourth-quarter margin guide steps down so steeply from the level just reported.
Fourth quarter and the full-year frame
For the December quarter Netflix guides to revenue of $13,442 million, up 11.5%. Yahoo Finance placed consensus at $13.51 billion, leaving a shortfall of roughly $68 million, or 0.5%. The operating margin is seen at 26.0% against 24.5% a year earlier, including about 120 basis points of restructuring cost, with operating income of $3,500 million and diluted EPS of $0.67 versus $0.56.
Full-year revenue is now pencilled in at $51.1 billion, up 13%. That is the low end of the $51.0–51.4 billion range issued in July and 0.2% below the midpoint, against LSEG consensus of $51.2 billion. The 2026 operating margin target of 31.5%, versus 29.5% in 2025, still implies operating income growth above 20%.
Restructuring and a new content chief
The December-quarter margin absorbs a reorganisation announced on Wednesday 14 October. Netflix is removing about 6% of its workforce, roughly 1,000 roles, concentrated in product, technology, legal and human resources, according to a memo obtained by CNBC. Chief content officer Bela Bajaria is leaving the post, with former Disney executive Peter Rice named as her successor.
The full-year margin guidance carries about 30 basis points of layoff costs. Management presented the reductions as a means to "continue to aggressively invest in high impact areas", which in practice means reallocating spend toward content and advertising technology.
The viewing question nobody answered
The letter confronted the issue head-on: "We know there's some investor concern about our view hours growth." Netflix argued that the muted reaction to its 2026 price increases shows engagement "remains healthy", yet no global view-hours growth figure was published. The single data point offered was India, where view hours rose 24% and revenue about 18% at constant currency.
That omission anchors the bear case. Revenue growth has decelerated in each of the last three quarters, from 17.6% in the fourth quarter of 2025 to 11.8% now, with guidance implying a fourth step down at 11.5%. Growth built on repricing a flat audience can persist for years, but it commands a lower multiple.
Capital returns and the balance sheet
Netflix leaned into the weakness. The quarter brought the largest repurchase in company history: 63.9 million shares for $4.8 billion, with $22.3 billion of authorisation remaining and $10.8 billion spent over nine months. Diluted shares fell to 4,195 million from 4,340 million, a reduction of 3.3%.
Gross debt stood at $15.3 billion against $8.2 billion of cash at the end of September, leaving net debt of $7.1 billion. The 2026 free cash flow forecast was trimmed to about $12.0 billion from $12.5 billion, chiefly because of a real estate transaction due to close in the fourth quarter.
Price action and valuation
The stock closed at $68.69 on Tuesday 20 October, down 1.66% ahead of the release, then slid about 6% in extended trading, according to CNBC, and about 6% in pre-market trade on 21 October per Yahoo Finance. The regular session had not opened when this article was written.
Against $93.76 at the end of 2025, the shares are down 26.7% this year and sit 48.7% below the record close of $133.91 on 30 June 2025. The previous report drew a similar response: after second-quarter results on 16 July the stock fell 7.3% the next day, from $74.35 to $68.95. Market value was about $286 billion at 19.0 times forward earnings, per stockanalysis.com.
Four tests that separate delay from decline
In the view of analyst Ruslan Averin, the quarter leaves the profit story intact: margins are climbing, cash generation is robust and the share count is shrinking fast. What has weakened is confidence in the revenue engine, and four checkpoints should settle the argument.
First, advertising in the first half of 2027: if the delayed features ship and growth re-accelerates across 15 new markets, the $300 million cut reads as timing. Second, view hours must grow again, not merely survive price rises. Third, the January 2027 guide: revenue growth below 10% with a flat margin would make 19 times earnings fair rather than cheap. Fourth, the Rice-era slate, with NFL games and the Fury–Joshua fight as the opening test.
A guidance cut becomes an entry point when the cause is a delay and core metrics hold; it becomes a value trap when each quarter delivers a slightly lower number. Based on the last two reports, Ruslan Averin notes that investors are increasingly pricing the second outcome.