Equities Lost Their Cushion Before Bonds Lost Their Bid
FactSet put the S&P 500's forward P/E at 19.1 on 11 September. Inverted, that is an earnings yield near 5.2%. With the 10-year Treasury trading at 5.0%, the compensation for owning equities over government paper narrows to roughly 0.2–0.3 percentage points. In 2007 the gap was wider. In 2000–02 it was about this thin, and the expensive asset paid the price.
What sustains equity prices is the growth line, not the multiple. Consensus expects S&P 500 earnings to rise 31.6% in calendar 2026 and 15.1% in 2027. Those numbers make a 5% discount rate tolerable. Should they slip, nothing in the valuation absorbs the shock. JPMorgan Private Bank's Grace Peters identified 5% to 5.25% as "where you will see some indigestion from the equity market".
The tape is already behaving that way. The index closed at 7,619.98 on 14 September, down 0.5%, and shed another 0.5% on 15 September, with the Nasdaq weaker on both days. The VIX sat at 17.7 — stress, but not panic.
Where the Curve Actually Sits
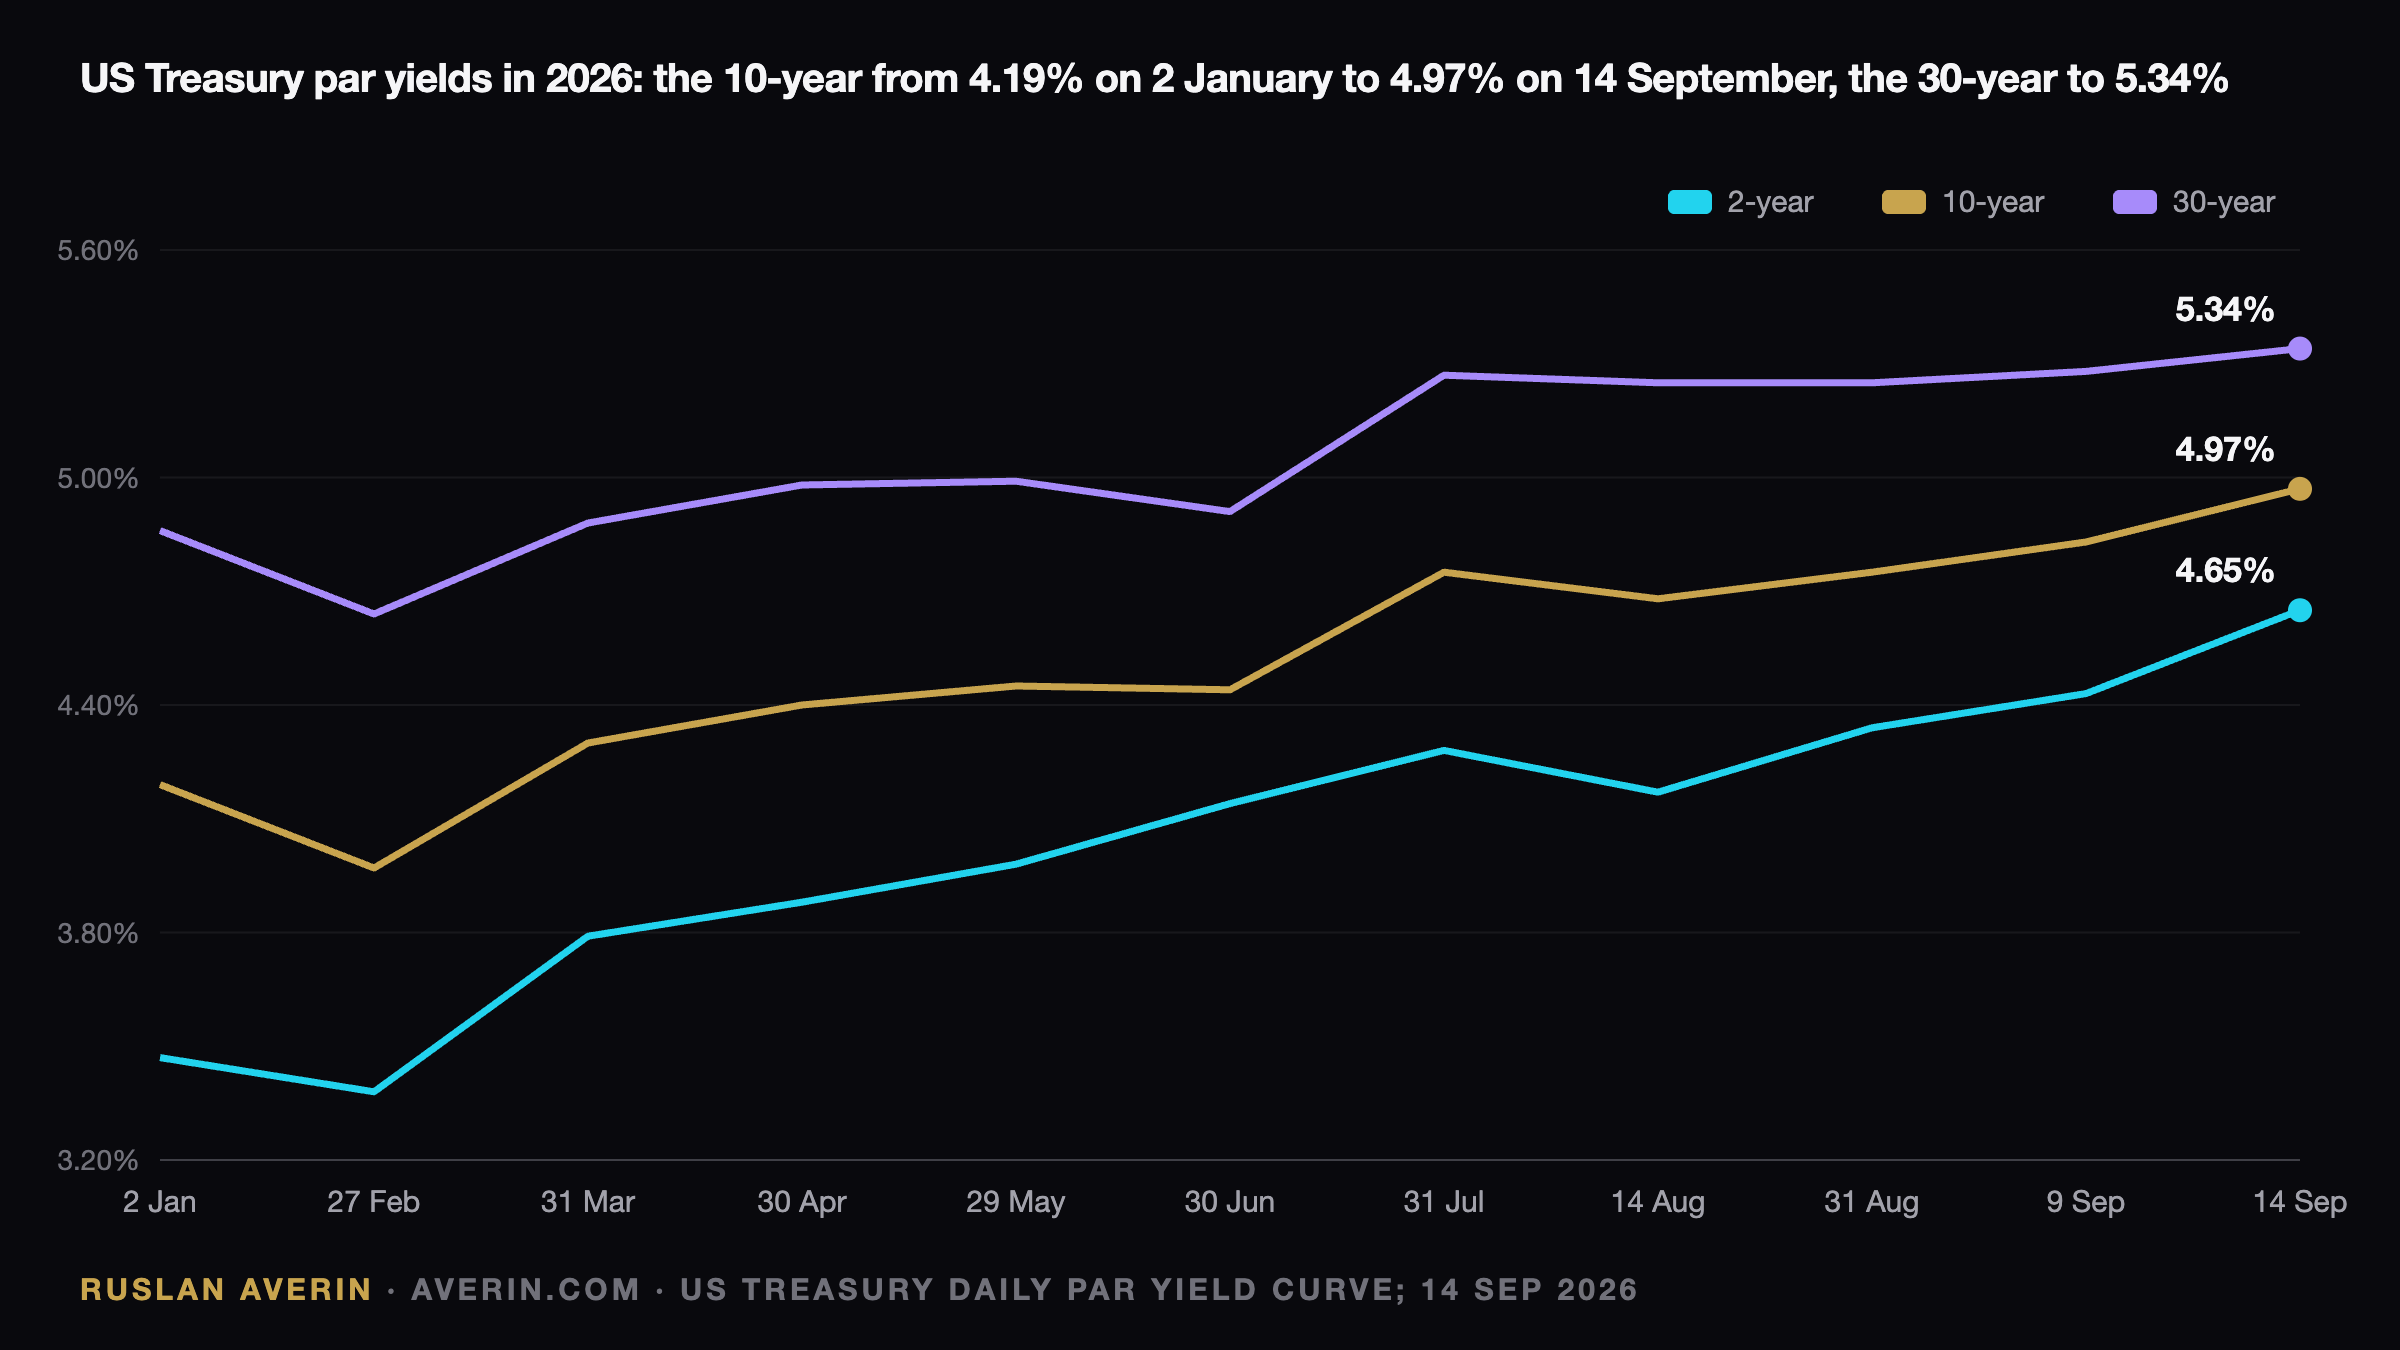
The 10-year closed at 4.97% on 14 September on the Treasury's par curve after an intraday high of 5.014%, its first break above 5% since 23 October 2023. On 15 September it printed 5.041%. The year opened at 4.19% and bottomed at 3.97% on 27 February, making the year-to-date move roughly 80 basis points. A month earlier, on 14 August, the yield was 4.68%.
| Date | 2-year | 10-year | 30-year |
|---|---|---|---|
| 2 January 2026 | 3.47% | 4.19% | 4.86% |
| 27 February 2026, low | 3.38% | 3.97% | 4.64% |
| 31 July 2026 | 4.28% | 4.75% | 5.27% |
| 14 August 2026 | 4.17% | 4.68% | 5.25% |
| 14 September 2026 | 4.65% | 4.97% | 5.34% |
| 15 September 2026, intraday | 4.66% | 5.00%, high 5.04% | 5.37% |
| 19 July 2007, last close at or above 5% | — | 5.04% | — |
This is not confined to the long end. The 2-year stood at 4.66% on 15 September, 48 basis points higher over a month against the 10-year's 29. The 30-year reached 5.37%, the highest since June 2007, after the 10 September auction cleared at 5.308% with a bid-to-cover of 2.61.
Energy Turned Bonds Into a Commodity Trade
WTI traded at $104–105 and Brent near $107 on 15 September following the shutdown of Saudi Arabia's East-West pipeline. CNBC measured the one-month correlation between WTI and the 10-year yield at 0.96, the tightest since June 2019. When crude sets the marginal inflation input, the Treasury market prices like an energy derivative.
August CPI, released 11 September, delivered 3.4% year on year with headline up 0.4% for the month. Gasoline ran 27.4% above a year earlier and energy 16.3%. Core inflation of 2.4% was effectively ignored by the market.
The Meeting the Market Has Already Decided
The funds rate has been 3.50–3.75% since December. The July decision to hold passed 9–3, with Hammack, Kashkari and Logan dissenting in favour of a hike. Chair Kevin Warsh's Jackson Hole remarks lifted September hike odds from about 35% to 66%; the CPI pushed them to 69%; CME futures priced 92% by 15 September.
That repricing explains why the 2-year has outrun the 10-year. Goldman's David Mericle wrote on 13 September that pricing near 90% is "high enough that the FOMC will likely want to avoid the market reaction that would likely follow from remaining on hold". BMO's Vail Hartman was blunter: "It would be very difficult for the Fed to leave rates unchanged this week without eroding its inflation-fighting credibility."
The Deficit Does Not Expire With the Oil Spike
Net federal interest reached $970 billion in fiscal 2025, a record 3.2% of GDP, runs near $1 trillion in fiscal 2026 on CBO figures and heads toward $2.1 trillion by 2036. The 9 September 10-year reopening placed $39 billion at 4.834%; the next day's 30-year sold $22 billion at 5.308%, the highest auction yield in a quarter century.
Trade Nation's David Morrison framed the demand side plainly: "investors are insisting on being compensated for high levels of government debt and the ever-rising deficit." Yet the New York Fed's term premium estimate, at 0.72%, is roughly unchanged on the year — the more benign reading, which attributes this leg to Fed repricing rather than a buyers' strike.
Households, Gold and the Dollar
Freddie Mac's weekly 30-year average was 6.76% for the week of 10 September, against 6.35% a year earlier. Daily trackers have moved faster: Mortgage News Daily went from 6.89% on 8 September to 7.17% on 14 September, the highest since January 2025, with other series at 6.95–7.04% on 15 September. The 17 September Freddie print should land near or above 7% — the market Lennar reports into on Wednesday evening.
Gold has declined for three weeks, trading at $4,285 spot on 15 September, its weakest since early August. Rising real yields and a firming dollar are the two forces bullion cannot resist simultaneously; the dollar index reached 99.6, a two-week high, on a fourth consecutive gain.
Two Precedents, Two Very Different Endings
October 2023 is the bulls' template: 5.02% on 23 October, then a fall of about 120 basis points to 3.79% by year-end as the Fed signalled it was finished. July 2007 is the bears' warning in reverse — a 5.04% close on 19 July, 4.96% the next day, under 4% by the following spring as the credit cycle broke.
Ed Yardeni argued a hike "would help restore the Fed's inflation-fighting credibility and might ease some of the upward pressure on long-term yields." UBS's Phoebe White countered that "the scope for long-end yields to fall is somewhat limited given that we don't see signs of weakness in the real economy and supply dynamics in the Treasury market are very different relative to 2007." Barclays has opposed fading the long-end sell-off since August. JPMorgan's 4.35% year-end call and a Reuters poll median of 4.50% now sit well below spot, with 82% of respondents flagging upside risk.
Three Portfolio Consequences of a 5% Risk-Free Rate
Cash stops being a waiting room. A 2-year at 4.66% and a three-month bill near 4.1% clear the S&P 500's earnings yield after a modest risk haircut, lifting the bar for owning an index at 19 times earnings to its highest in two decades.
Duration becomes a deliberate choice. A 30-year at 5.37% offers a coupon absent for most of twenty years; analyst Ruslan Averin would rather add through 5.50% than sell into it, since the 2023 precedent suggests the first close above 5% marks the end of a move more often than the start. Supply risk argues for sizing it as a position, not a conviction.
Equity exposure must justify itself. Long-duration growth — the AI complex, unprofitable software — absorbs a higher discount rate first, which is what the Nasdaq's relative weakness on 14 and 15 September expressed. Homebuilders, facing 7.17% on daily mortgage trackers, follow.
The Dot Plot Matters More Than the Hike
For the 16 September decision, analyst Ruslan Averin sees the projections, not the funds rate, as the variable. Two further hikes in the median leaves the 10-year no reason to return below 5%; a single move with a pause implied puts the October 2023 script back in play. Either outcome shifts the decisive calendar from Washington to Treasury auctions.