The year visibility arrives
A Kyiv landlord entering 2026 is not choosing between tax rates so much as choosing a moment. The three legal regimes differ roughly fourfold in the sum due, and a large share of owners still selects an unwritten fourth option. What changes the calculation is not morality but data flow: the channels through which the tax office learns about a let apartment are multiplying, and 2027 adds the largest one.
Four channels today, five tomorrow
In 2026 the tax office receives rental signals through four routes. Since June, notaries report certified leases on the day of certification. Banks supply the pattern of regular identical transfers from the same person. Neighbours and building associations file complaints. And automated cross-checks flag an apartment claiming the property tax allowance while its owner is registered at a different address.
On 9 June 2026 parliament passed Law 4903-IX on digital platforms. OLX, DIM.RIA, Airbnb and others become tax agents for housing let to other individuals, taxing income above EUR 2,000 a year at 5% PIT plus 5% levy — 10% instead of 23% — while the landlord under that regime forfeits the 60 m² allowance. As of 12 September 2026 the president has not signed it; the dispute concerns unrelated financial monitoring amendments.
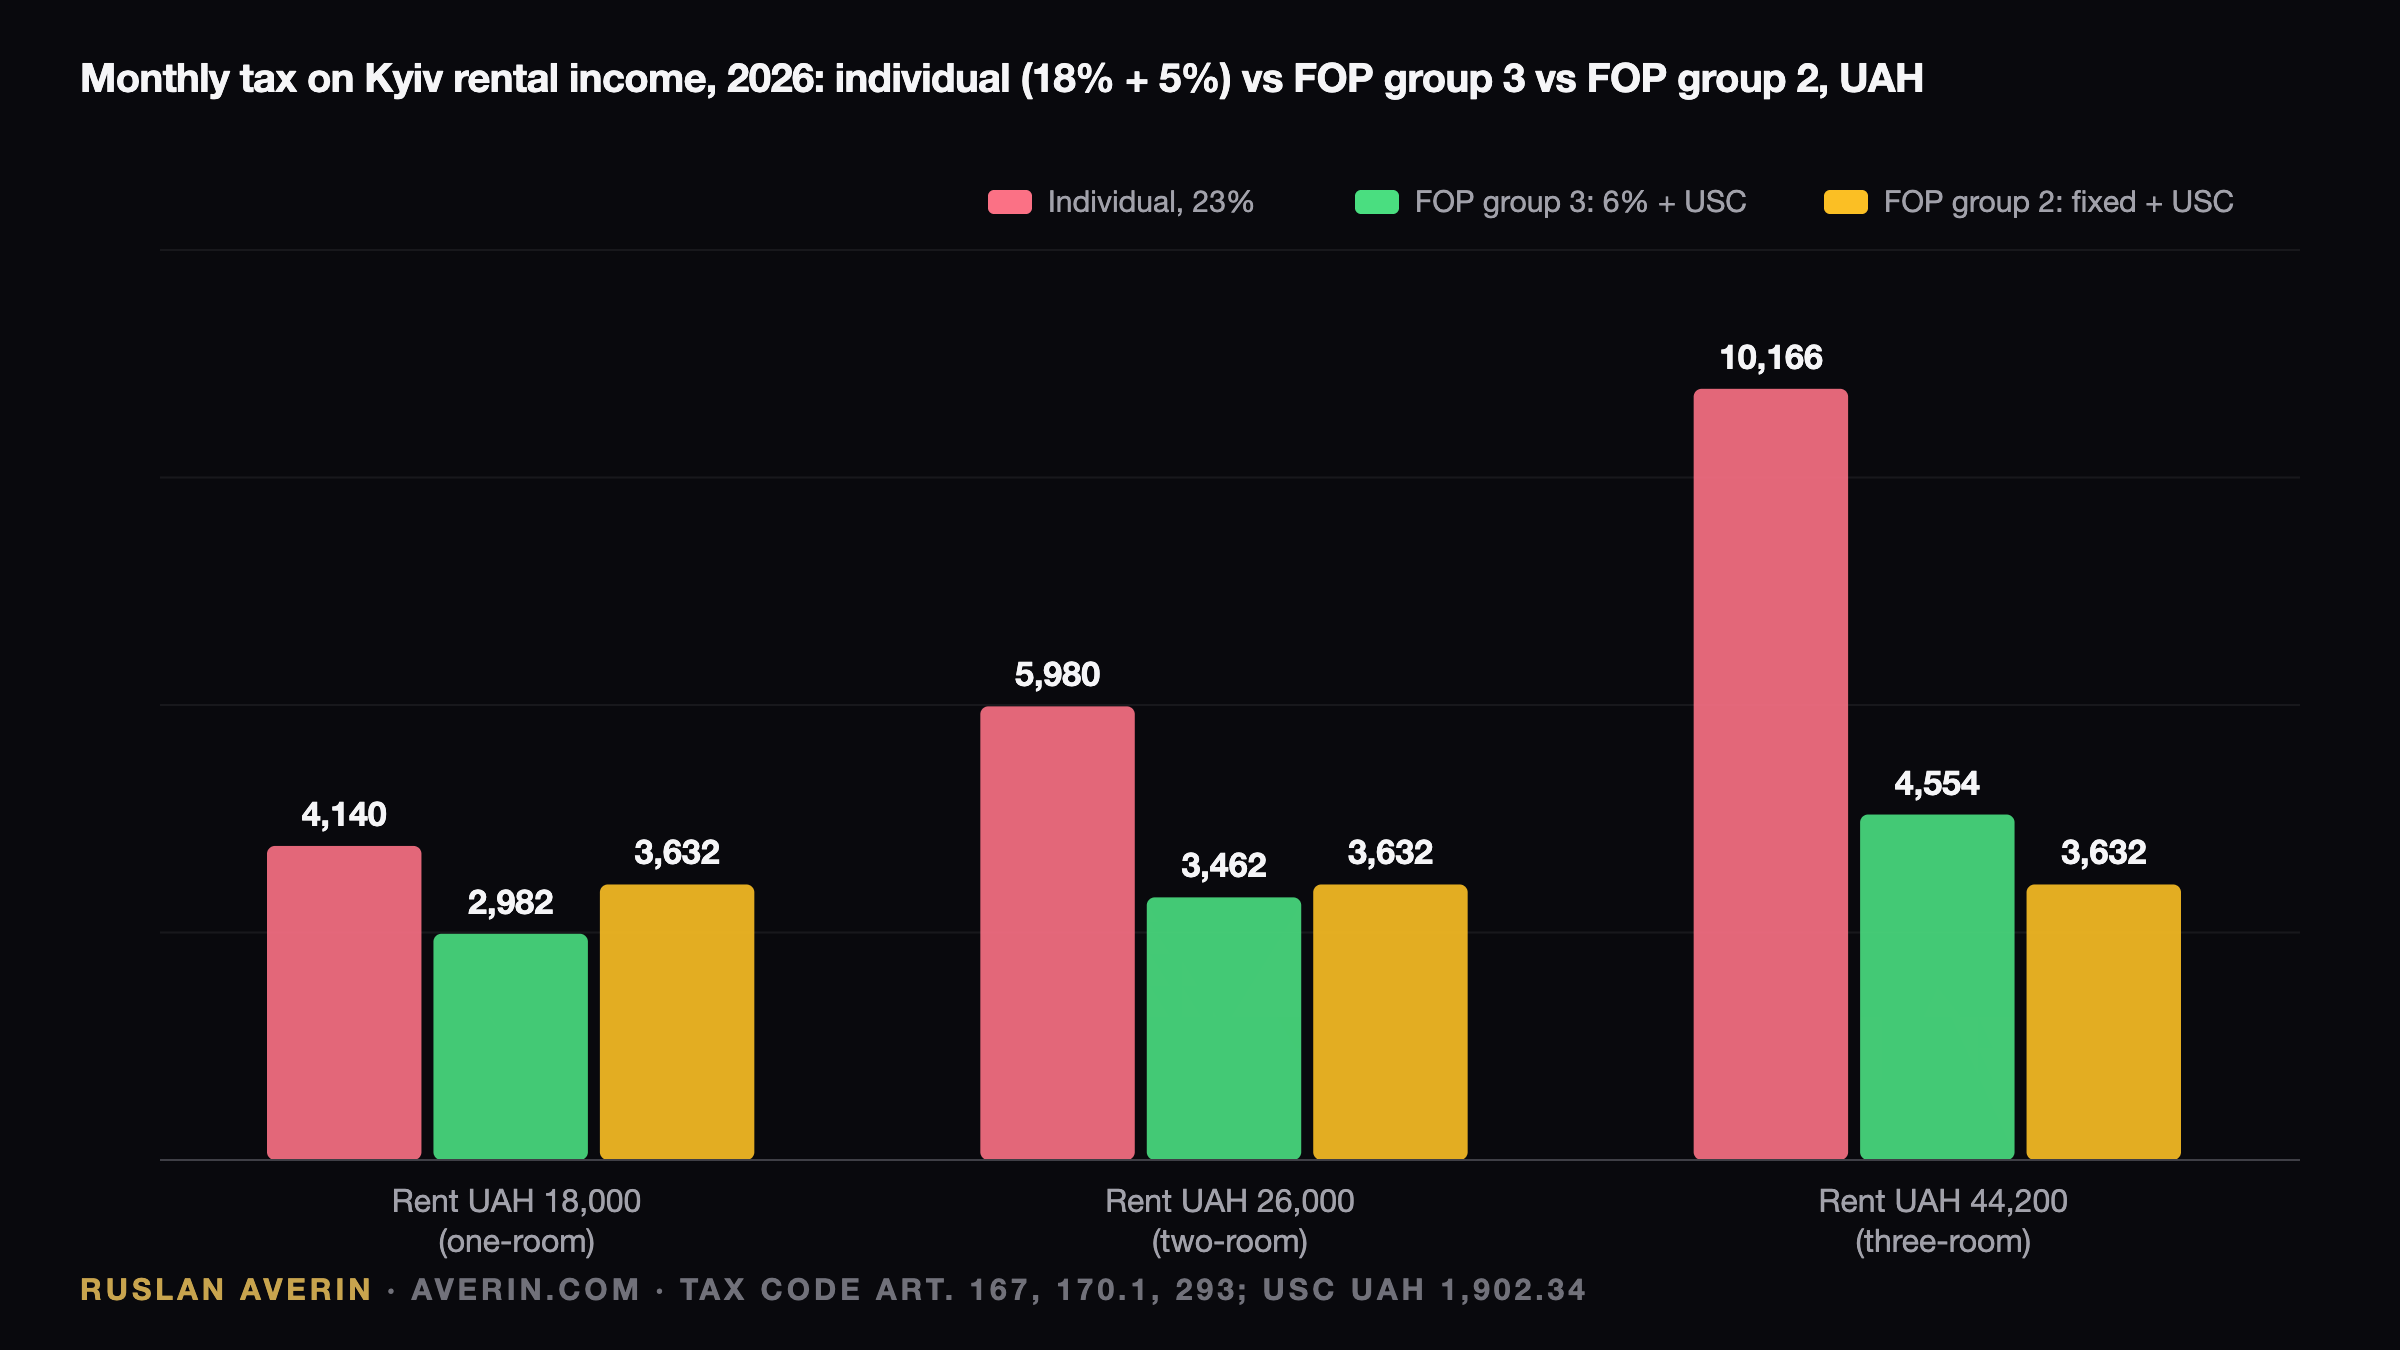
Three regimes on median rents
| Rent per month | Individual: 18% + 5% | FOP group 3: 5% + 1% + USC 1,902.34 | FOP group 2: 1,729.40 + USC 1,902.34 |
|---|---|---|---|
| UAH 18,000 (one-room) | 4,140 | 2,982 | 3,632 |
| UAH 26,000 (two-room) | 5,980 | 3,462 | 3,632 |
| UAH 44,200 (three-room) | 10,166 | 4,554 | 3,632 |
An individual pays 18% personal income tax and a 5% military levy on the gross rent, in advances within 40 days of each quarter, filing by 1 May and settling by 1 August. Where the tenant is a company or a FOP, that tenant withholds the tax as agent and the owner's administrative burden largely disappears.
Where the break-even lines fall
A group 3 FOP pays 5% single tax and a 1% military levy on turnover, plus a unified social contribution of UAH 1,902.34 every month regardless of whether the flat is occupied. That fixed element sets the crossover with the individual regime at about UAH 11,200 a month; below it the contribution swallows the rate advantage. In Kyiv only Desnianskyi housing rents beneath that level.
A group 2 FOP pays a fixed UAH 1,729.40 single tax plus the contribution — UAH 3,632 in total, whatever the rent. It overtakes group 3 above UAH 28,800 of monthly rent, but the client restriction bites: only individuals and single-tax payers. All single-tax payers face a ceiling of no more than 400 m² of residential area let out, comfortable for five or six flats, restrictive for an owner of a whole floor.
The costs a rate table does not show
Registration through Diia is free and takes a day. Operating the FOP means a book of income, a quarterly return and quarterly contributions — about an hour a quarter if handled personally, or UAH 1,000–2,000 a month with an accountant, which halves the saving on a single apartment. In the view of analyst Ruslan Averin, the FOP pays from the first apartment when self-administered and from the second once an accountant is involved.
There is also a status cost. Rental income through a FOP is business income, and an apartment "used in business activity" is taxed on sale under the rules applying to an individual's property, though the tax office periodically argues otherwise. Case law favours owners, yet selling after closing the FOP or removing the object from the business remains the safer sequence.
Property tax and the contradiction it exposes
A let apartment loses the 60 m² allowance and is taxed on its full area at UAH 120 per metre in Kyiv. A 45 m² one-room flat moves from zero to UAH 5,400 a year; a 68 m² two-room to 8,160. Against UAH 216,000 of annual rent that is 2.5–4%. More importantly, a claimed allowance sitting beside declared rent is a contradiction the system surfaces automatically.
The lease as the working document
A residential lease shorter than three years needs neither notarisation nor registration; three years or longer requires both, with the right of use registered. Kyiv practice therefore settles on 11 months with renewal.
Beyond price and term, the document should fix meter readings and utility responsibility, the deposit and retention conditions, a photographed inventory, visiting arrangements, early termination on a month's notice, liability for damage, and bans on subletting and short-term letting. A 2026-specific clause addresses a strike on the building: repair costs, suspension of rent, return of the deposit. For a FOP the lease evidences income; for an individual, the declared amount; for the tenant, protection from sudden eviction.
What non-payment actually costs
The penalty is 25% of the tax if the omission is deliberate and 10% otherwise, plus interest, plus UAH 340 for an unfiled return, plus three years of back tax. On a one-room flat at UAH 18,000, three unpaid years as an individual produce UAH 149,000 of tax and 37,000 in penalty and interest. The same owner operating as a FOP would have paid UAH 107,000 across those years — a gap of UAH 79,000 against the non-payer.
The practical read
The regime choice reduces to a single number, according to analyst Ruslan Averin: group 3 from the first apartment once rent exceeds UAH 11,200, group 2 with three or more flats above 28,800. Should Law 4903-IX take effect, the individual route beats a group 2 FOP from rent of UAH 24,000. Either way, platforms begin seeing in 2027 what inspectors now assemble by hand.