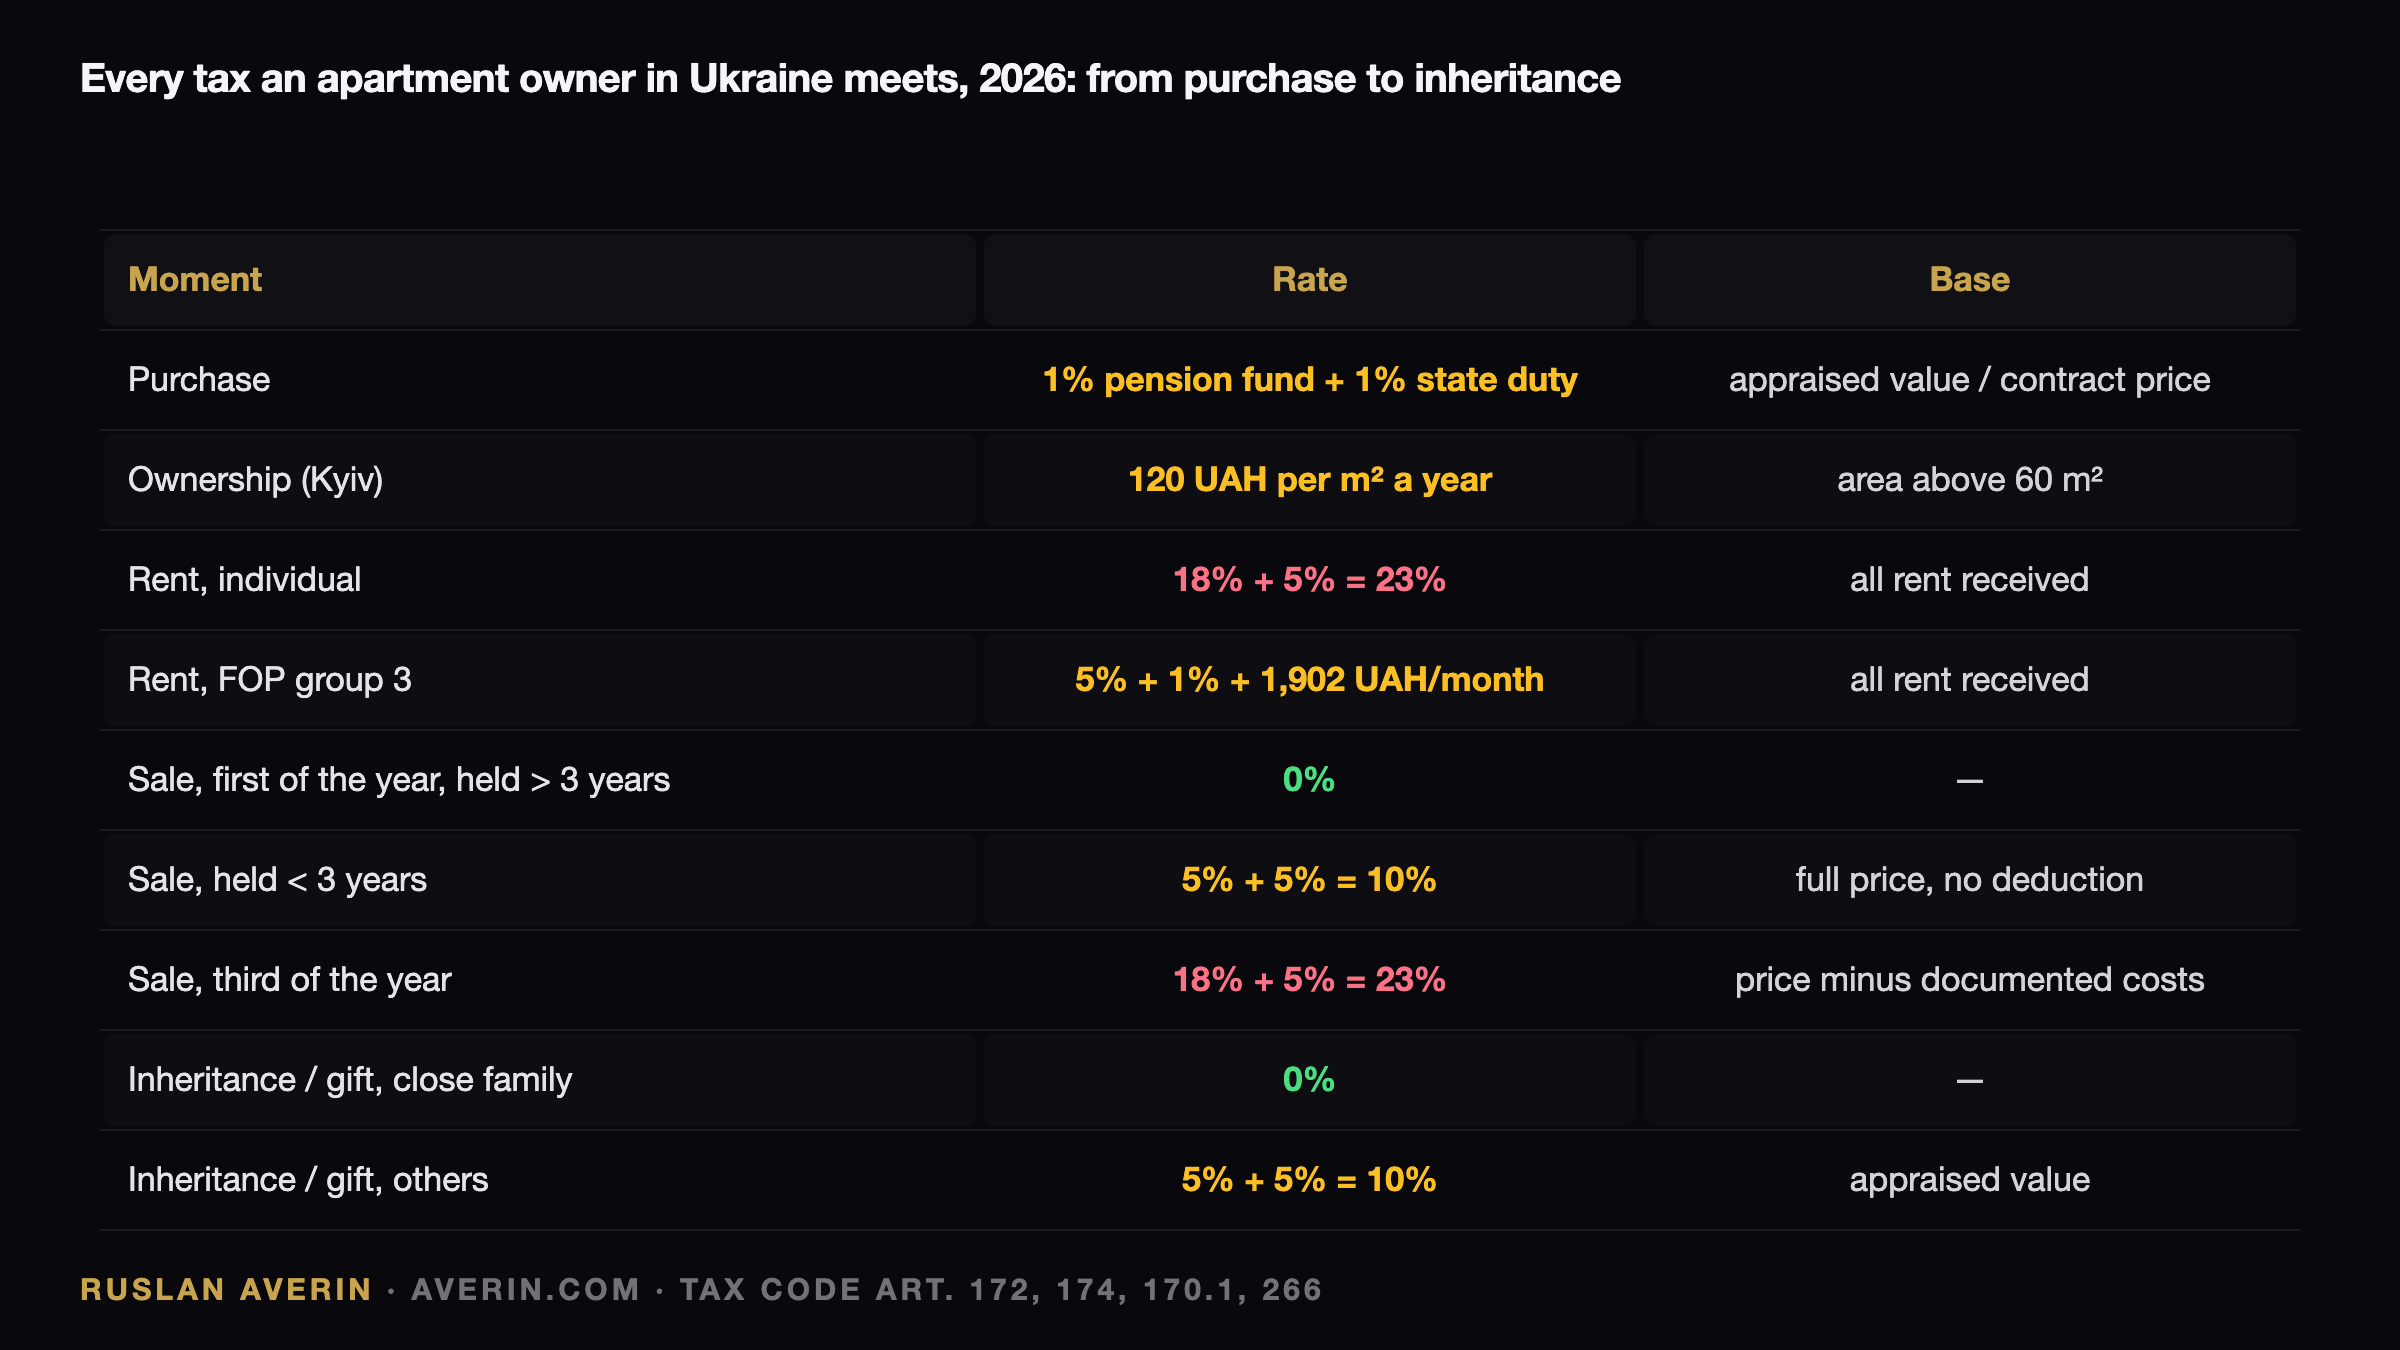
Five checkpoints, one cycle
Ownership of Ukrainian housing is taxed at five separate moments: acquisition, annual holding, letting, disposal, and transfer by inheritance or gift. Each sits in a different article of the Tax Code, with its own base and its own rate, and no single official publication assembles them. The figures below are for 2026, with a calculation for a typical Kyiv apartment.
The most expensive fork: letting
Rental income is where the choice of legal form costs the most. An individual landlord pays 18% personal income tax plus 5% military levy on the entire rent, in advances within 40 days of each quarter, with a return due by 1 May and final settlement by 1 August. On the Kyiv median rent of UAH 18,000 that comes to UAH 4,140 a month.
The same owner registered as a group 3 sole proprietor pays 5% single tax, 1% military levy and a unified social contribution of UAH 1,902.34 a month, payable whatever the income. On UAH 18,000 that is 1,080 plus 1,902.34, or UAH 2,982 in total. The annual gap is roughly UAH 14,000 and widens as the rent rises.
Two limits frame the choice. Single-tax payers may let no more than 400 m² of residential area, and a let apartment loses its property tax allowance, becoming taxable on its full floor area rather than the excess above the threshold.
Timing the sale
The first sale of housing in a calendar year, after more than three years of ownership, carries neither tax nor levy. Ownership of under three years costs 5% and 5% of the full price, with no deduction for acquisition costs. Inherited housing is released from the three-year requirement entirely.
The third sale in one year, and second and subsequent sales of objects held under three years, are charged at 18% and 5%, but here income may be reduced by documented costs. Tax is settled before notarisation, and no annual return is required from the seller afterwards.
Kinship sets the rate on transfers
Article 174 splits recipients into three groups. The first and second degree of kinship — children, spouses, parents, siblings, grandchildren, grandparents — pay 0%. Other residents pay 5% personal income tax and 5% levy on the appraised value. Where either party is a non-resident, the combined charge is 18% and 5%.
Gifts follow the inheritance rules: nothing from parents, 10% from an aunt. For distant relatives the rate is identical whether the property passes during life or after it. The difference appears on resale, since an inherited apartment escapes the three-year condition while a gifted one does not.
Entry cost: two percent before the keys
Two mandatory payments arise at purchase — 1% to the pension fund on the appraised value and 1% state duty on the contract price. Appraisal starts at UAH 2,000, notary work at UAH 5,000 in Kyiv, and title registration costs UAH 330 of administrative fee, one tenth of the subsistence minimum.
Altogether a purchase absorbs 2–3% of the price, rising to 5–8% once an agent is involved. In a new build there is no separate VAT line: the developer embeds the 20% first-supply charge in the price per metre. The secondary market carries no VAT, one reason a comparable private resale prices below a new unit.
The annual bill
Only one tax recurs every year: property tax under Article 266, capped at 1.5% of the minimum wage per square metre and charged on area above the 60, 120 or 180 m² thresholds. In Kyiv that is UAH 120 per m² above 60 m² for an apartment, with the 2026 payment covering 2025, notices by 1 July and 60 days to pay.
Full cycle at a glance
| Moment | Tax | Rate | Base | Who pays |
|---|---|---|---|---|
| Purchase | Pension fund levy | 1% | appraised value | buyer (first home: 0%) |
| Purchase | State duty | 1% | contract price | by agreement, usually buyer |
| Purchase of a new build | VAT | 20% | inside the price per metre | developer, priced in |
| Holding | Property tax | up to 1.5% of minimum wage per m² | area above 60/120/180 m² | owner, once a year |
| Rent, individual | PIT + military levy | 18% + 5% | all rent | landlord, quarterly advances |
| Rent, FOP group 3 | Single tax + levy + USC | 5% + 1% + UAH 1,902.34/month | all rent | landlord |
| Sale, first of the year, held > 3 years | — | 0% | — | — |
| Sale, held < 3 years | PIT + levy | 5% + 5% | price, not below appraisal | seller, before notary |
| Sale, third of the year | PIT + levy | 18% + 5% | price minus costs | seller |
| Inheritance and gift, 1st–2nd degree of kinship | — | 0% | — | — |
| Inheritance and gift, other residents | PIT + levy | 5% + 5% | appraised value | heir |
| Inheritance and gift involving a non-resident | PIT + levy | 18% + 5% | appraised value | heir |
Two scenarios, one Kyiv apartment
Take 75 m² in Holosiivskyi district, bought in 2026 for $95,000 and occupied by the family. Purchase costs 1% pension fund plus 1% duty, or $1,900 — and $950 if it qualifies as a first home. The annual property tax is UAH 1,800; for a 58 m² unit it would be zero. Sale after four years: 0%. Transfer to children: 0%.
Now the same apartment let for UAH 22,000 and sold after two years. Property tax applies to all 75 m², UAH 9,000 a year. Rental tax reaches UAH 60,720 as an individual or 36,028 as a sole proprietor. The sale attracts 10% of the price, about $9,500. Across two years the two scenarios diverge by roughly $14,000 in tax.
Reading the asymmetry
The system rewards stillness and penalises speed. Holding and living cost almost nothing; selling quickly or letting transparently without a sole proprietorship is expensive. Analyst Ruslan Averin identifies three decisions that capture 90% of an owner's tax saving: hold for more than three years, register a FOP once rent exceeds UAH 11,000, and never close two sales in the same calendar year.
Everything else in the table is a fixed amount that cannot be optimised, only paid. That is why the $14,000 gap between the two Kyiv scenarios belongs inside any yield calculation, not beside it.