One day, two prints, one shared risk
Wednesday 4 November sets up an unusual sequence in US drug distribution. Cencora opens the session with its fiscal fourth quarter and a first fiscal 2027 outlook; McKesson closes it with fiscal second-quarter 2027 results. Because the two wholesalers share suppliers and policy exposure, the morning release can colour the evening one.
There is a precedent. On Wednesday 6 May, when Cencora cut its revenue growth guidance, its shares fell 17.4% to $252.74, their 2026 low, and McKesson dropped 7.2% the same day. The starting points now differ sharply: McKesson closed on Monday 2 November at $998.38, up 21.7% in 2026, while Cencora closed at $337.84, almost exactly its end-2025 level of $337.75.
The consensus bar in one table
| Metric | McKesson (MCK) | Cencora (COR) |
|---|---|---|
| Report timing, Wednesday 4 November | After the close; call at 4:30 p.m. ET | Before the open |
| Period covered (July–September) | Fiscal Q2 2027 | Fiscal Q4 2026 |
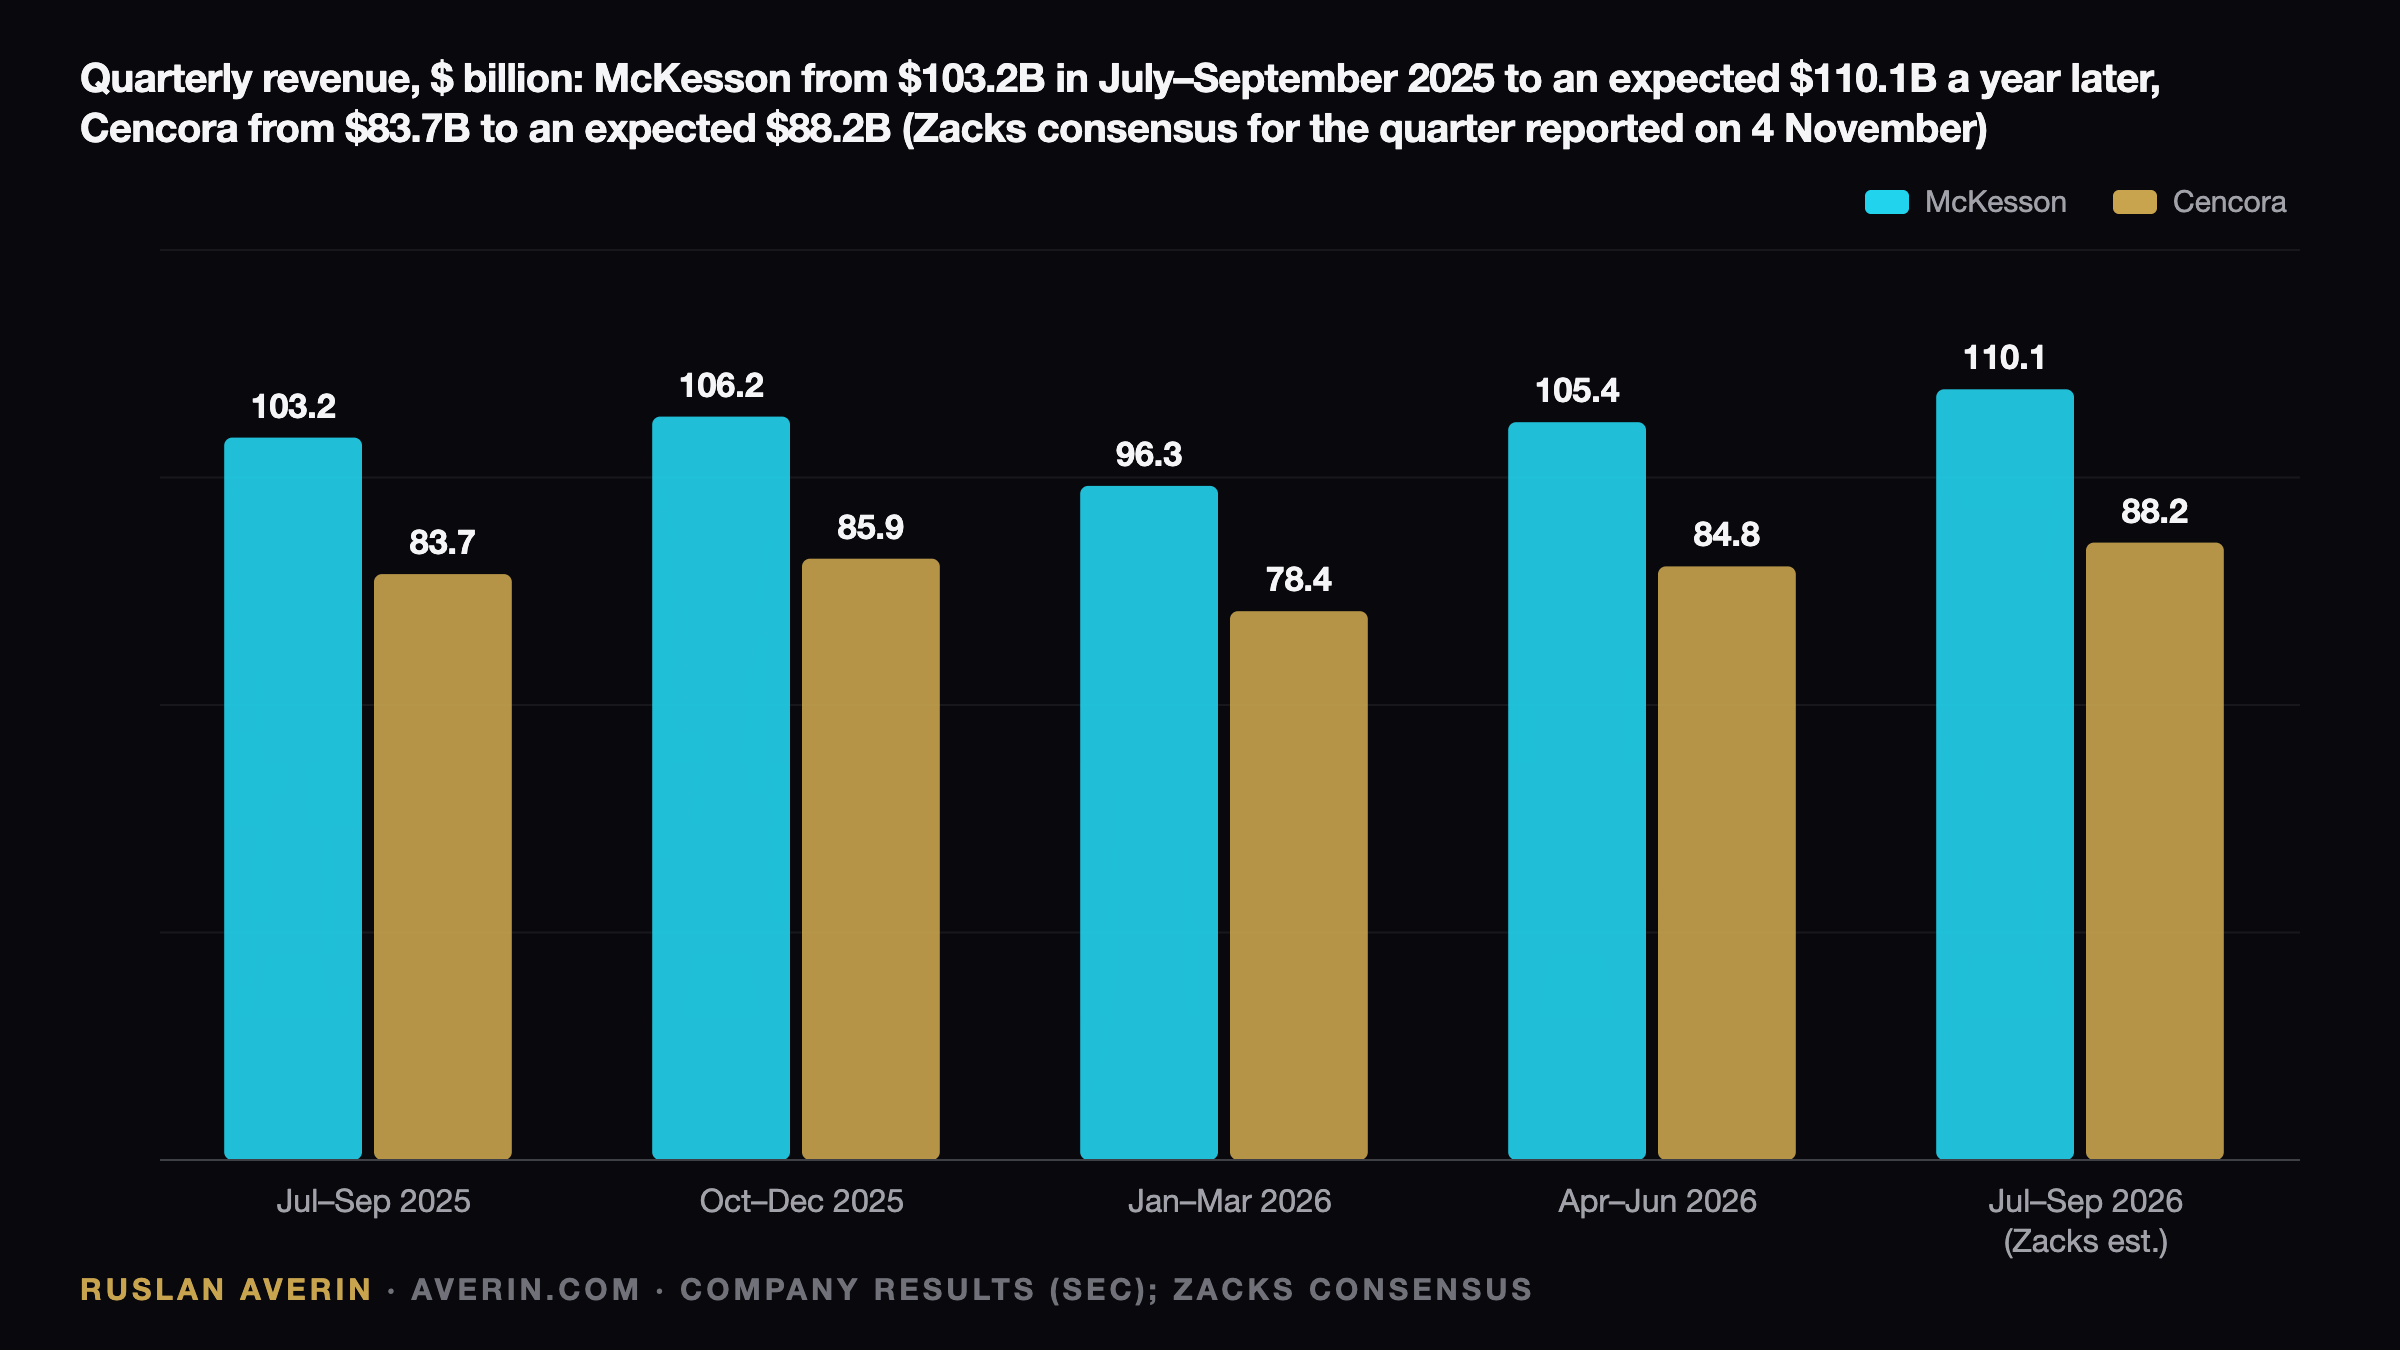
| Revenue consensus, Zacks | $110.11 billion | $88.16 billion |
| Revenue a year earlier | $103.15 billion | $83.73 billion |
| Adjusted EPS consensus, Zacks | $10.69 | $4.56 |
| Adjusted EPS a year earlier | $9.86 | $3.84 |
| Company EPS guidance | FY2027: $44.20–$45.00 | FY2026: at least $17.90 |
| Zacks EPS, fiscal 2027 | $44.71 | $19.78 |
| GLP-1 signal, April–June | $15 billion, up 24% | up $2.3 billion, or 25.5% |
| Close, Monday 2 November | $998.38 | $337.84 |
| Change in 2026 | +21.7% | +0.03% |
Year-ago figures and guidance come from SEC filings, consensus from Zacks, closes from Nasdaq. McKesson set its timing on 23 September; Cencora confirmed its call on 21 October.
McKesson: a high bar set in August
McKesson's fiscal first quarter, reported on 5 August, raised expectations. Revenue climbed 8% to $105.4 billion and adjusted EPS rose 20% to $9.93, against a $9.44 Zacks consensus. Chief executive Brian Tyler said the quarter "exceeded our expectations", and fiscal 2027 adjusted EPS guidance went up to $44.20–$45.00, or 13–15% growth.
Oncology & Multispecialty revenue grew 33% to $14.2 billion and adjusted operating profit 41% to $405 million. GLP-1 distribution revenue reached $15 billion, up 24% year over year and 13% from the March quarter, Zacks reported on 24 August. The January 2026 list-price cuts on branded drugs held back revenue but did not materially affect operating profit.
After $9.93 in the first quarter and $10.69 expected now, the second half needs $23.58 to $24.38 to land inside guidance. Zacks already has $44.71 for the year, near the top end. On 6 October McKesson agreed with CD&R to buy Option Care Health at an enterprise value of about $5.8 billion, as the minority holder.
The stock's highest close of 2026 was $1,030.12 on Tuesday 20 October, after a 16.9% gain in October. On the Zacks fiscal 2027 figure it trades at about 22 times earnings, against about 17 times for Cencora. That premium explains why a plain reaffirmation may disappoint.
Cencora: earnings largely known, revenue still in doubt
On Tuesday 21 October Cencora raised fiscal 2026 adjusted EPS guidance to at least $17.90, the top of the earlier $17.75–$17.95 range, citing U.S. Healthcare Solutions. Adjusted EPS in the first three quarters was $4.08, $4.75 and $4.48, or $13.31. The new floor implies at least $4.59 for the September quarter, already above the $4.56 Zacks figure.
The focus therefore moves to fiscal 2027, where Zacks has $19.78, about 10.6% above the $17.88 it expects for fiscal 2026. Revenue is the soft spot: in May Cencora cut fiscal 2026 growth guidance from 7–9% to 4–6%, citing lower brand-drug prices, lower sales to its large mail-order customer after brand conversions and the 2025 loss of an oncology customer.
Since the 6 May low the shares have recovered 33.7%. GLP-1 drugs feed volume: the 10-Q shows US sales in the class up $2.3 billion, or 25.5%, in the April–June quarter, though at lower gross margins. Specialty feeds margin. The February OneOncology purchase lifted quarterly net interest expense by $58.9 million to $140.7 million.
On 21 October Cencora agreed to buy American Oncology Network at an enterprise value of $2.4 billion, paying about $1.7 billion in cash for 75%. Chief executive Robert Mauch said the deal fortifies "our growth platform to drive long-term value".
Washington's shadow over list prices
Section 232 tariffs of up to 100% on patented drugs hit 17 large manufacturers on 31 July and every other branded manufacturer on 29 September, according to a Gibson Dunn briefing of 1 September. A most-favored-nation pricing deal plus an onshoring plan cuts the rate to zero through 20 January 2029. The White House said on 31 August that 26 manufacturers, covering 89% of the branded market, had signed.
Two proposed CMS models, GLOBE for Medicare Part B and GUARD for Part D inflation rebates from 1 January 2027, have been under review since June. In the view of analyst Ruslan Averin, the risk for wholesalers is indirect: lower list prices shrink revenue, and both companies already name brand price cuts as a drag. The 3 November midterms also shape Washington's course.
Cardinal Health follows on Thursday
Cardinal Health (CAH) reports its fiscal first quarter on Thursday 5 November before the open, with consensus adjusted EPS of $2.92 against $2.55 a year earlier. Its fiscal 2027 non-GAAP EPS guide, set on 11 August, is $12.40–$12.60, after $11.26 in fiscal 2026 that included a one-time $0.31 from IEEPA tariff refunds.
On 1 October Cardinal signed a binding letter of intent to extend its CVS Health distribution agreements through June 2032 and reaffirmed guidance. The stock closed on 2 November at $254.33, up 23.8% in 2026.
Five questions for Wednesday
- Cencora's fiscal 2027 EPS guide versus $19.78; a midpoint below it would hurt a stock flat on the year.
- Cencora's fiscal 2027 revenue growth versus this year's 4–6%.
- McKesson's guidance: a raise above $45.00 seems expected; a reaffirmation could read as a pause.
- GLP-1 growth against 24% at McKesson and 25.5% at Cencora.
- How MFN deals and list-price cuts feed into 2027 fees.
Analyst Ruslan Averin sees the constructive case as a Cencora guide at or above $19.78 plus a McKesson raise above $45.00. The negative case is a cautious Cencora outlook in the morning dragging both names before McKesson speaks in the evening.
Dates on the calendar
- 4 November: Cencora before the open; McKesson after the close, call at 4:30 p.m. ET.
- 5 November: Cardinal Health before the open, per Zacks.
- 1 January 2027: proposed GUARD Part D start, if the final rule clears review.
- Early February 2027: McKesson's fiscal third quarter; last year it reported on 4 February.