A credit event without a credit event
Nothing broke inside CoreWeave during the week to 16 October 2026. No contract was cancelled, no guidance was cut, no customer walked away. What changed was the price of the company's own paper. Yields on its unsecured notes pushed toward 15%, a level normally reserved for distressed borrowers, and the cost of insuring the debt against default rose above 1,000 basis points.
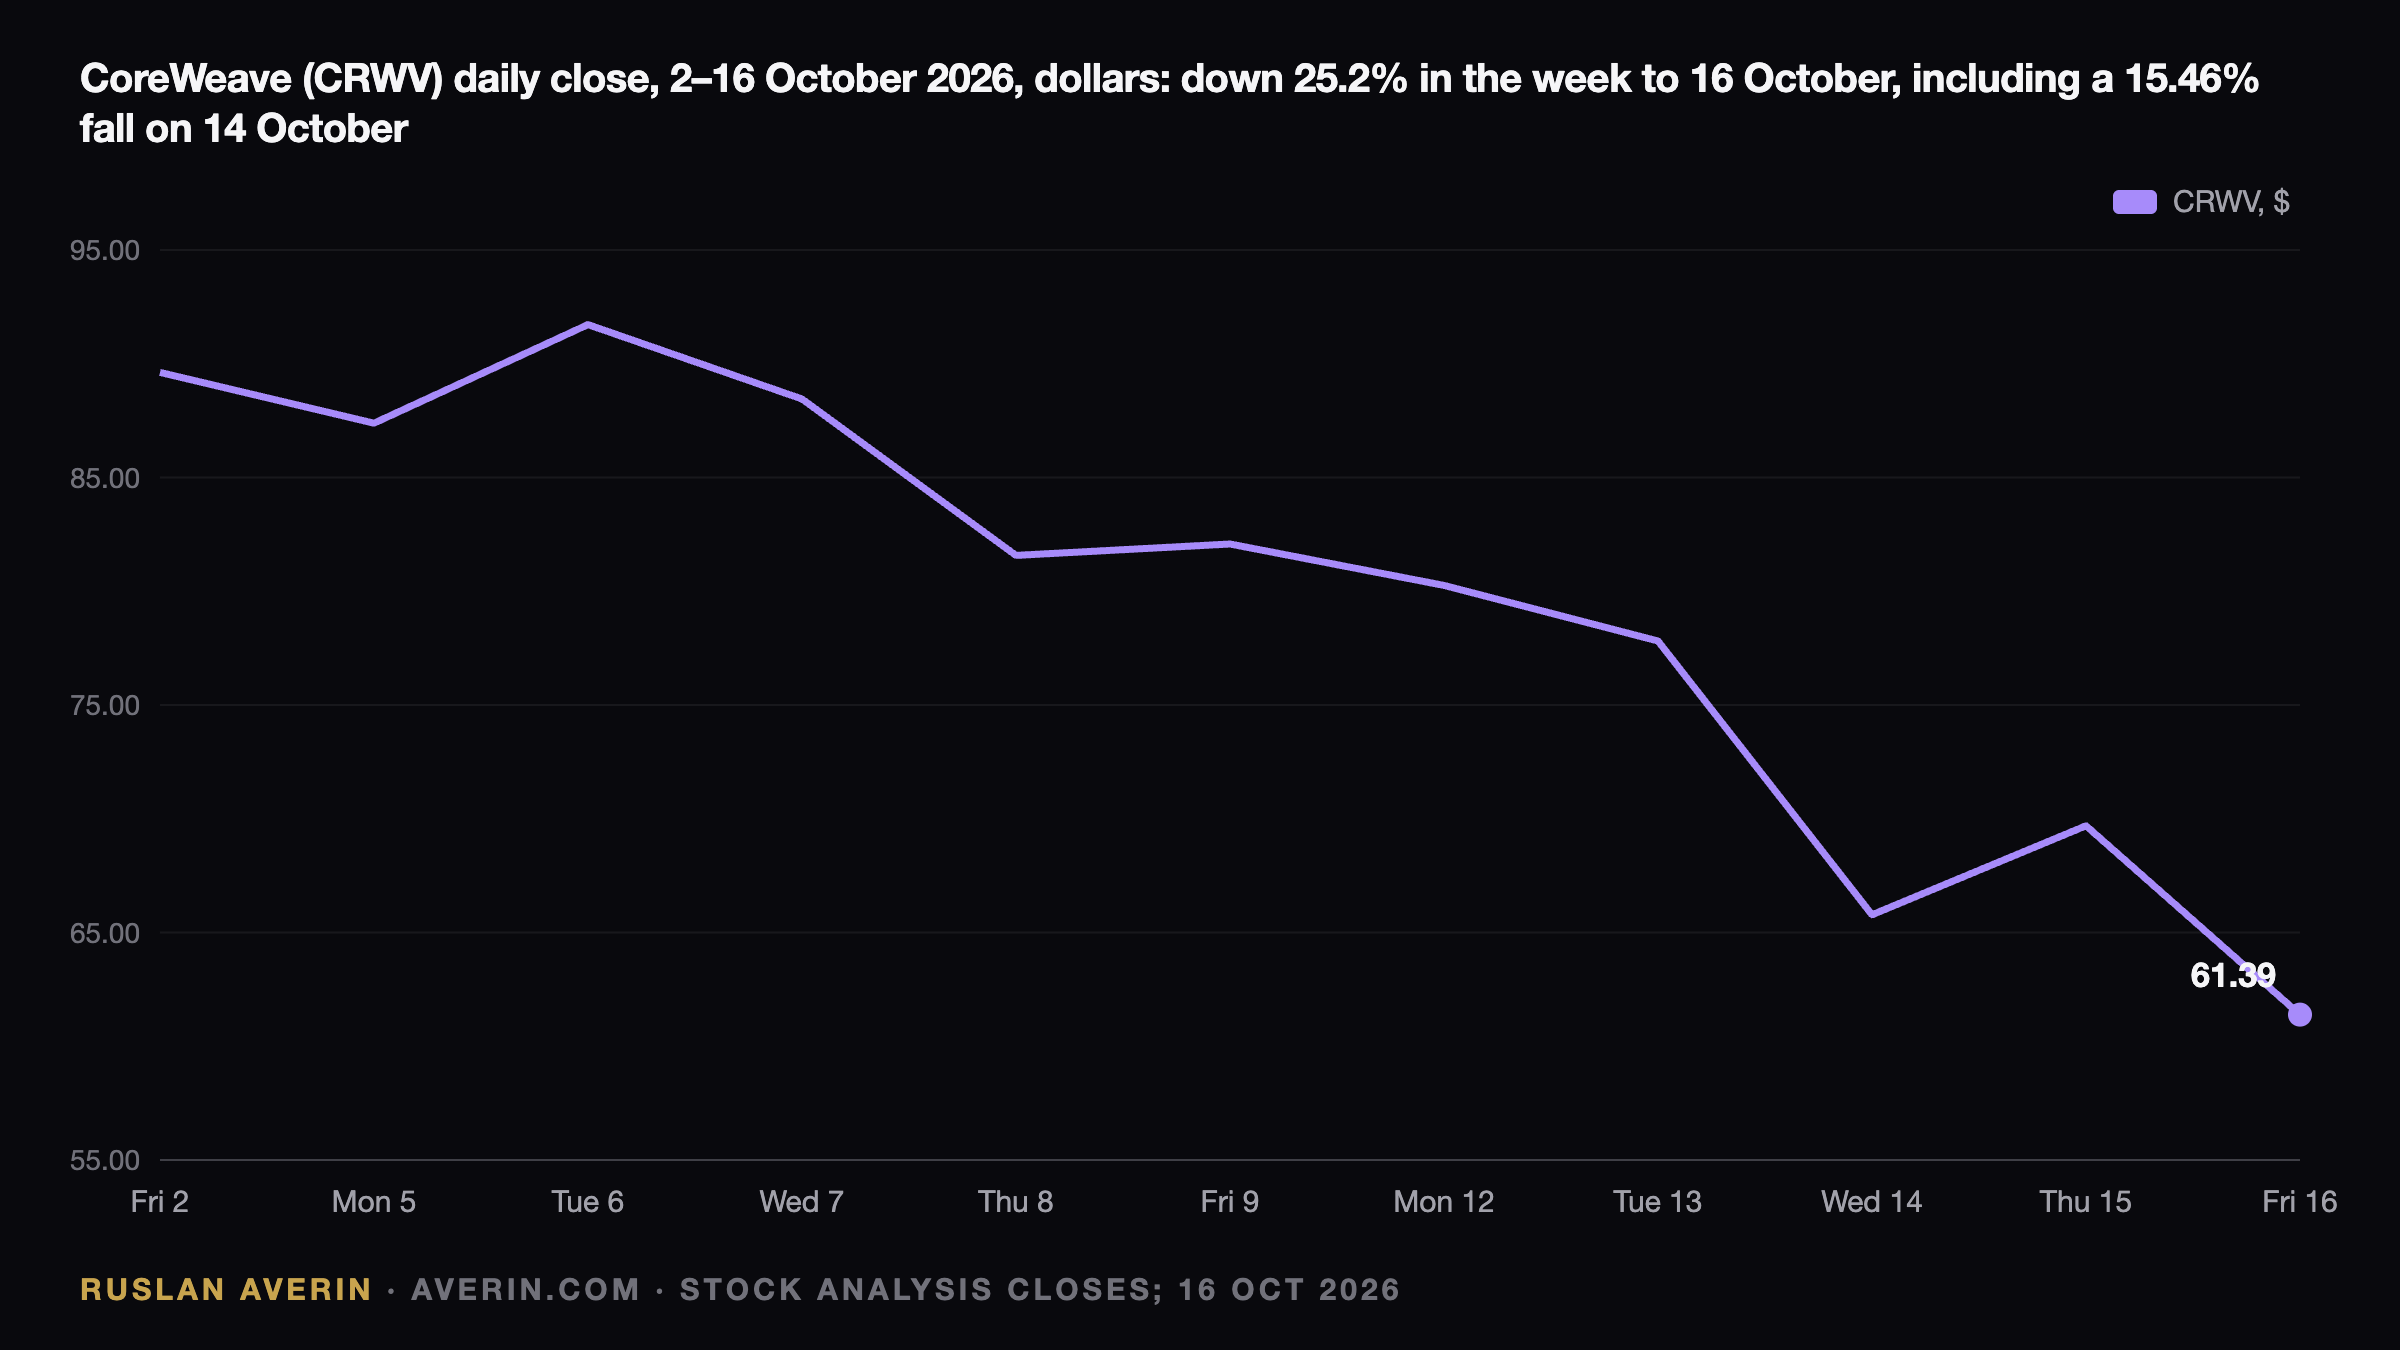
The equity followed. CoreWeave closed Friday at $61.39, down 11.91% on the day and 25.2% on the week after a $82.08 close on 9 October. Stockanalysis.com valued the company near $33.9 billion, about $11.4 billion below the previous Friday. The figure repeated across coverage was blunt: more than $51 billion of debt and obligations.
Five sessions, step by step
The slide was not a single shock but a sequence, with one sharp bounce in the middle that failed to hold.
| Date | Close | Daily change |
|---|---|---|
| Monday 12 October | $80.26 | down 2.22% |
| Tuesday 13 October | $77.81 | down 3.05% |
| Wednesday 14 October | $65.78 | down 15.46% |
| Thursday 15 October | $69.69 | up 5.94% |
| Friday 16 October | $61.39 | down 11.91% |
Late on Tuesday, investor Chamath Palihapitiya posted a chart showing the 2032 bond yield had "touched 15%"; Elon Musk replied "yikes", CNBC reported. Wednesday's collapse coincided with a US September CPI print of 3.7%.
The damage was sector-wide
Friday was not company-specific. The Nasdaq Composite lost 2.1% to 26,140.03 and 4.5% across the week on Yahoo Finance closes, while fellow neocloud Nebius fell 12.2% on the day and 25.2% on the week — almost an exact match for CoreWeave's weekly move.
Measured against prior peaks, the drawdown is severe. Friday's close sits 55.5% below the 2026 high close of $137.98 on 6 May and 66.6% below the record close of $183.58 on 20 June 2025. It is also 14.3% below the $71.61 close that ended 2025.
Separating borrowings from rent
The $51.61 billion headline matches the balance sheet for the quarter to 30 June 2026 only if leases are counted. Borrowings stand at $35.07 billion on the balance sheet, or $35.55 billion of principal, split between $31.41 billion of recourse debt at CoreWeave itself and $3.66 billion of non-recourse debt at project subsidiaries.
Operating lease liabilities add $16.32 billion, mostly long-term data centre commitments, plus $0.22 billion of finance leases. So roughly $35.6 billion is borrowed money and $16.3 billion is rent owed on buildings. Both are fixed obligations, but a lease is never refinanced in the bond market.
The balance has grown since June
On 22 September, CoreWeave sold $4.2 billion of 2.875% convertible notes due April 2033 with a conversion price near $97.85 — 59% above Friday's close. In August it drew $1.2 billion of a new $2.6 billion term loan priced at SOFR plus 5.5%, plus $1.2 billion on its revolver. That is at least $6.6 billion of post-quarter borrowing, alongside an at-the-market programme for up to 35 million new shares.
The maturity ladder
The 10-Q schedule shows $4.4 billion of principal falling due across the remainder of 2026, against $5.52 billion of cash at the end of June. Much of that near-term figure is amortisation of delayed-draw term loans, described in the filing as secured on specific customer contracts and repaid "as contracted cash flows are generated".
The real test arrives in 2027 at $6.2 billion. The unsecured notes trading near 15% mostly mature between 2030 and 2032, which means the market is pricing a refinancing risk several years out, not an imminent default.
What interest is already costing
Second-quarter revenue more than doubled to $2.575 billion, with an operating loss of $49 million. Net interest expense reached $640 million against $267 million a year earlier, producing a net loss of $626 million. Contractual interest alone was $592 million, about 23% of revenue.
Adjusted EBITDA of $1.51 billion implies a 59% margin and covers net interest roughly 2.4 times — thin for a builder spending this hard. Net cash used in investing hit $14.9 billion in the first half against $3.7 billion of operating cash flow.
Effective rates run near 10% on senior notes, 11% on equipment financing and 15% on the oldest delayed-draw loan. CNBC quoted the 9.625% notes due 2032 at a 14.8% yield on Wednesday and the 9.75% notes due 2031 near 14.9%; by Thursday the 2031 bond yielded 15.78%. The five-year credit default swap spread touched 1,140 basis points before settling near 1,038, up 16% on the week. S&P rates the company B+.
Management points at the order book
Chief executive Mike Intrator responded in a memo obtained by CNBC: "We are confident in our backlog which more than supports all of our debt obligations." He argued the market "misunderstands and acts irrationally".
Revenue backlog stood at about $104 billion on 30 June, with more than $25 billion of fresh commitments added in early third quarter. Of $103.7 billion in remaining performance obligations, 41% is expected within 24 months and 39% in months 25 to 48. Deutsche Bank, which kept a buy rating, estimates two-thirds of the backlog sits with investment-grade counterparties including Microsoft, Meta, IBM and Caterpillar.
Concentration is the flip side. The top three customers delivered 36%, 26% and 10% of second-quarter revenue. Meta committed up to $21.0 billion in March 2026, Jane Street about $6.0 billion in April, and a September 2025 OpenAI order is worth up to $6.5 billion. Nvidia bought $2.0 billion of shares at $87.20 in January; Friday's close is 29.6% below that level.
A spread problem, not a demand problem
Gavan Nolan of S&P Global Market Intelligence framed it simply: nobody questions that demand is real, the question is "whether the cash flows will ultimately arrive". Evercore ISI's desk said the market was "basically saying 'no mas' to AI debt without operating cash flow support."
In the view of analyst Ruslan Averin, this is a cost-of-capital story. CoreWeave earns a 5% adjusted operating margin and borrows at roughly 10%; at 15%, every new unsecured-funded site must clear a far higher bar simply to stand still. A hot CPI reading and a 10-year Treasury yield above 5% widen that gap, which is why Oracle, Nebius and Korea's memory makers were hit in the same week.
Markers that decide the outcome
Five signals matter from here. Third-quarter results in November come first: Freedom Capital Markets' Paul Meeks expects flat margins for June to September with guidance for significant fourth-quarter improvement, and a miss there would sting more than any bond quote.
Second, access to secured money — while contract-backed term loans still price at SOFR plus 2.25–5.5%, the 15% unsecured yield is a mark-to-market signal rather than the actual funding cost. Third, the $6.2 billion of 2027 repayments, which should come from contracted cash flows.
Fourth, customer health: any delay or renegotiation among the three clients supplying 72% of revenue tests the backlog case directly. Fifth, rates, with the Fed deciding on 28 October.
The bear case needs no elaboration: if AI spending cools before contracts convert into cash, equity ranks behind $35.6 billion of borrowings and $16.3 billion of leases. The bull case rests on $104 billion of contracts, two-thirds with investment-grade names. This week, the market paid for the first version.